Bending Spoons Hunts Fallen Unicorns. Most of Its Growth Is Bought.
Bending Spoons' revenue grew 126% in Q2 2026. Organic growth was 3%. Miro is the next test of that acquisition model.
 Vincent JiangSeptember 11, 2026 · 2 min read
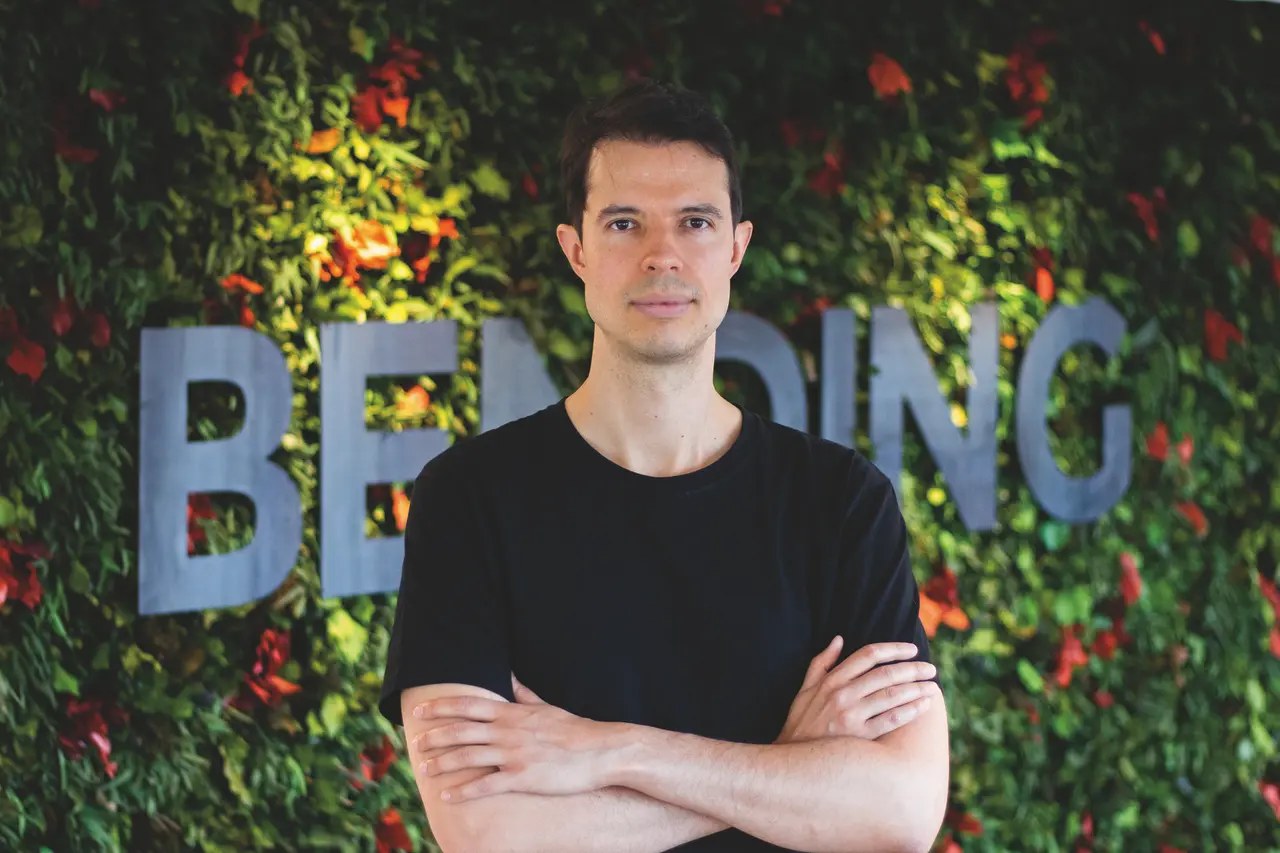
From $17.5 billion to the exit
Andrey Khusid's Miro reached a $17.5 billion valuation in January 2022.1
The September 10 agreement with Bending Spoons implies an equity value of about $1.79 billion, nearly 90% lower.1,2
Buying a place in the workflow
Luca Ferrari's company announced the Airtable deal in August and completed it September 4. Miro would follow a purchase that already put another workplace tool under the same owner.3,4
Miro reports around $600 million in annual recurring revenue, nearly 90% from business and enterprise customers. Those teams have work embedded in the product, giving the next owner relationships it would otherwise have to build.2
The cost of a new owner
Ferrari says he prioritizes predictable businesses that his team can substantially improve.5
That transformation can hurt. Bending Spoons planned to cut 75% of WeTransfer's staff in September 2024.6 Evernote's 2025 revenue growth came from higher spending per subscriber, partly offset by fewer subscribers.10
These precedents give Miro's workers and customers reason to examine the integration plan closely, and to read the cost story management tells about them carefully.
The growth behind the headlines
Bending Spoons reported $704 million in second-quarter 2026 revenue, up 126% from a year earlier. Organic revenue growth was 3%.7,8
The organic measure compares the same businesses across matched periods, including estimated revenue before acquisition. It is a better test of growth within the portfolio than the total's leap after adding businesses.7
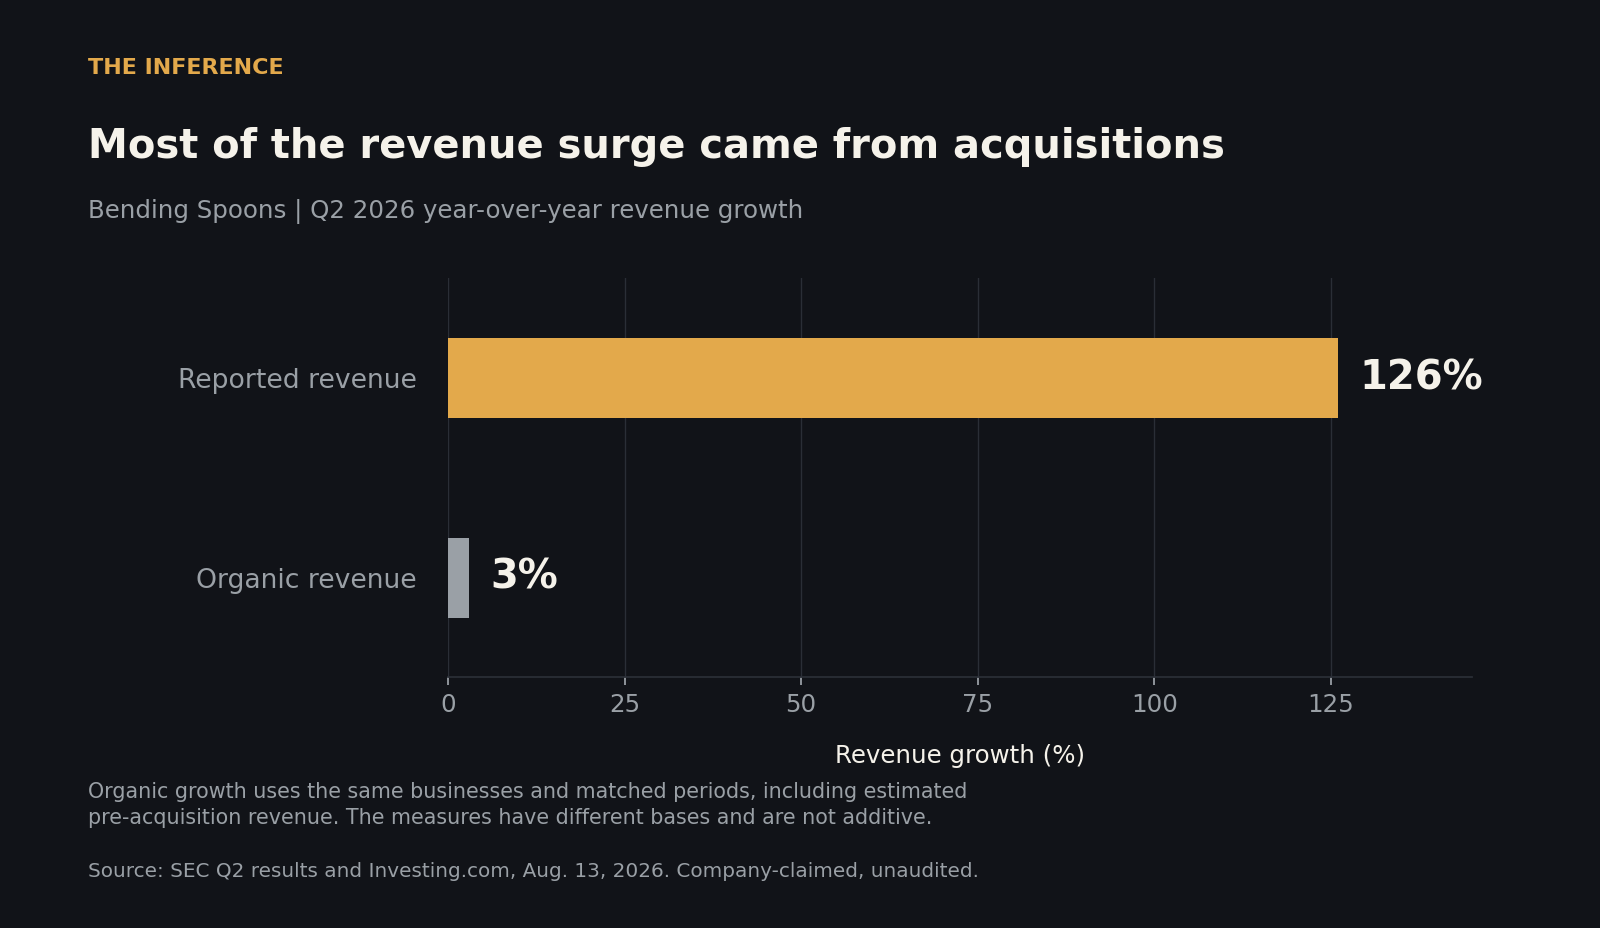
Acquisitions account for most of the expansion. That makes access to new deals and the ability to integrate them central to the growth story.7,8
Rebuilding can be real
Ferrari cited more than 70 product improvements across AOL, Eventbrite and Vimeo in the second quarter. Bending Spoons also reported $240 million in operating income.7,9
Better engineering and tighter costs can sustain useful software. The unresolved question is how much customers benefit alongside the owner.
Watch the first renewal
Miro's deal is expected to close in the fourth quarter, pending approvals. Watch subsequent pricing, customer retention, product reliability and organic growth.2
The next renewal will test whether Bending Spoons bought customer loyalty or merely the cost of leaving.
How this brief was made
01Gathered & sourced346 channels · 1,864 articles▾
Agents swept 346 channels and ingested 1,864 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated10 claims · 13 data feeds▾
Every one of 10 load-bearing claims was checked against primary sources, with 13 live data feeds reconciling the figures and charts.
- 1TechCrunch report on Miro's $17.5B round, Jan 5 2022 (company-claimed valuation; historical round corroborated by SiliconANGLE).
- 2Dow Jones via MarketScreener on the Miro agreement, Sep 10 2026 (company-claimed ARR and customer mix; implied equity value includes net cash, and the Q4 closing remains conditional).
- 3Reuters via MarketScreener on the Airtable terms, Aug 4 2026 (the $1.285B enterprise value and roughly $2.25B implied equity value are different measures).
- 4SEC filing, Airtable closing announcement, Sep 4 2026 (primary record of completion; it does not restate final consideration).
- 5Axios interview with Luca Ferrari, Jul 1 2026 (single-source executive interview; management intent, not established product outcomes).
- 6TechCrunch on the WeTransfer restructuring, Sep 8 2024 (company-confirmed historical plan; no equivalent Miro cuts have been announced).
- 7SEC filing, Q2 2026 results and metric definitions, Aug 13 2026 (company-claimed and unaudited; a filing is not an SEC endorsement).
- 8Investing.com Q2 earnings coverage, Aug 13 2026 (editor-reviewed, AI-assisted report; figures checked against the filing, and its erroneous IPO-quarter description is excluded).
- 9The Motley Fool transcript of the Aug 13 earnings call, Aug 20 2026 (company-claimed product improvements from speaker text; no independent product audit).
- 10Forbes operating profile of Bending Spoons, Jul 1 2026 (reported price increases and company-claimed subscriber and revenue directions).
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Confidential tips
Know something about this story? We protect our sources. Reach the editor directly, or read our guide to sharing securely.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.