Lenders want 9.95% from SharonAI. Analysts still see the stock at $105.
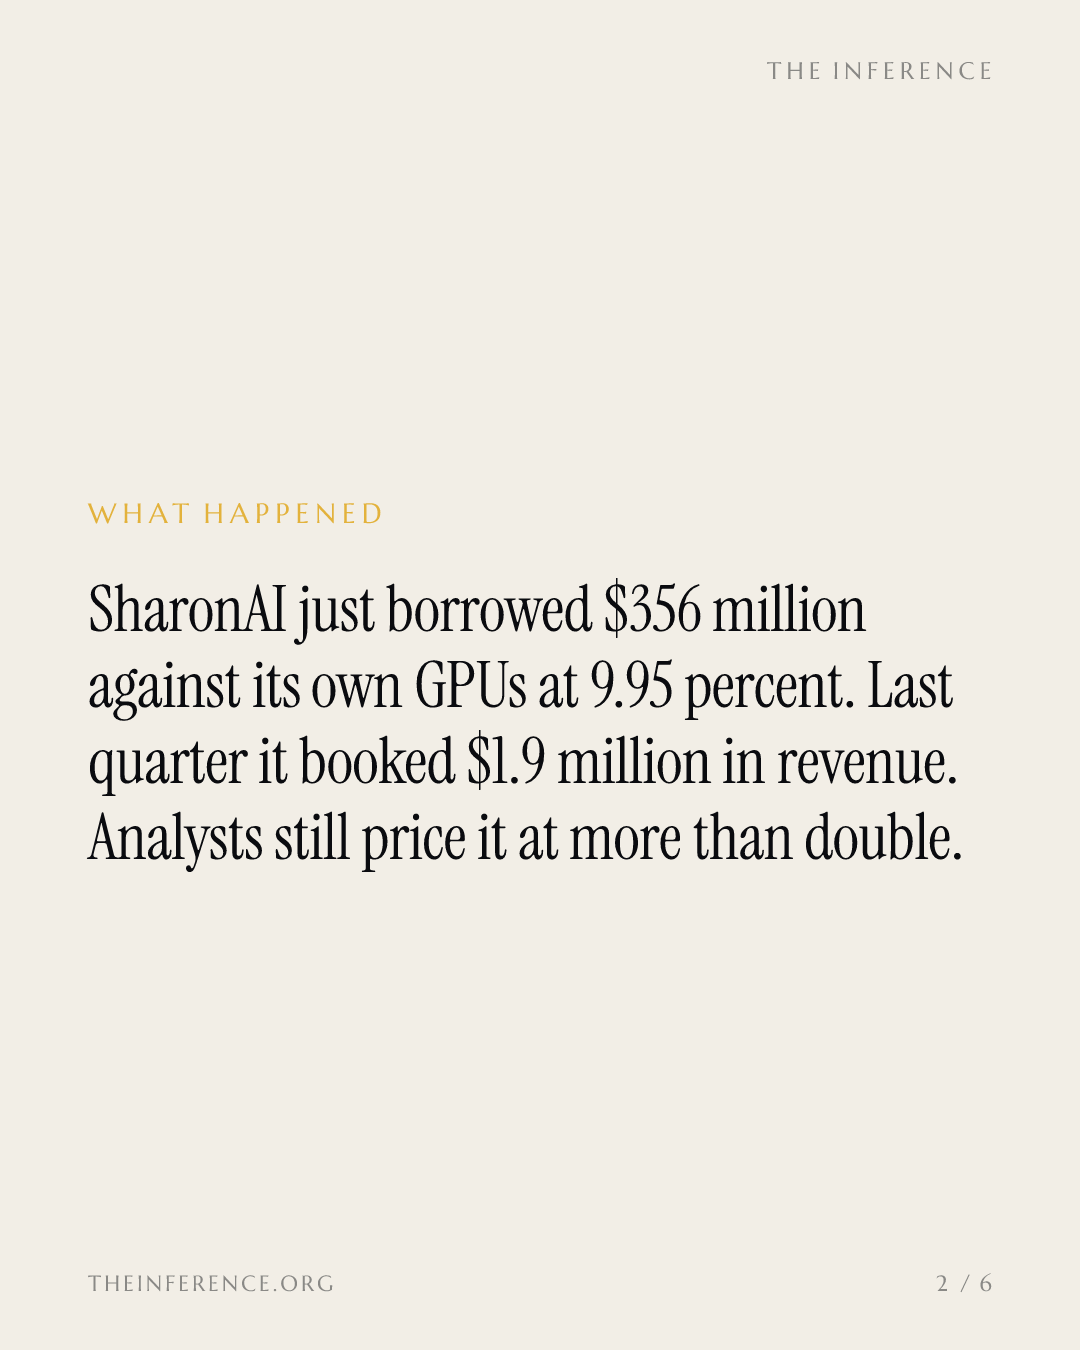
SharonAI just borrowed $356 million against its GPUs at 9.95 percent while collecting $1.9 million of quarterly revenue. Six analysts still carry a $105 mean target on the $49.85 stock.
 Vincent Jiang · 3 min read
Two prices for the same GPUs
SharonAI printed two prices this week. On 1 October the Australian neocloud (Nasdaq: SHAZ) closed its first GPU-backed loan: $356 million, senior secured, at a fixed 9.95 percent, fees on top 12. Goldman Sachs and select private credit funds are in the syndicate 3. The equity file reads differently. Six analysts carry a mean target of $105 on a stock that closed 1 October at $49.85, up 2,523 percent since 1 January 1.
Two markets, one company, a 110 percent gap between price and pitch, on an equity worth roughly $1.8 billion 45.
What 9.95 percent says
The loan sits in a special purpose vehicle secured by the GPUs themselves and the cash flows of the contracts they serve, arranged by Jarden Australia and described as the first of a series meant to fund more than 68,000 Nvidia GPUs by mid-2027 36. It stacks on $700 million of convertible notes due 2032 from June's $1.6 billion round, part of $2.6 billion raised in ten months 3.
Fully drawn, 9.95 percent on $356 million is roughly $8.9 million a quarter in interest before fees. Recognized revenue last quarter was $1.9 million, 74 percent below consensus, and $2.2 million for the whole first half 78. The $430.4 million net loss was nearly all a $400.4 million non-cash mark on the notes, a loss that exists because the share price rose 8.
Read the rate as a rule, not a one-off: 9.95 percent secured, before fees, is about what AI-compute credit costs at the fringe of the build, and it is the gauge to hold against any neocloud equity pitch trading like a winner.
What the $105 says
The bull case has receipts: $8.8 billion of contracted total value, including a six-year, $4.9 billion Nvidia collaboration whose floor pricing, management says, lets lenders "bank the guaranteed revenues in their models," plus $1.86 billion of cash and a first positive adjusted-EBITDA quarter at $591,000 89.
First material revenue is guided for the fourth quarter of 2026, and consensus has followed the guide: $25.3 million expected in Q3, then $88.6 million in Q4 79.
Revenue must jump 46-fold by Q4 to reach consensus
- Revenue
- Estimate
Data
| Revenue | |
|---|---|
| Q2 2026 (reported) | $1.9 |
| Q3 2026 (est.) (estimate) | $25.3 |
| Q4 2026 (est.) (estimate) | $88.6 |
The tape is warier. The stock fell 8.7 percent over the five sessions into the loan, with short interest of 9.19 percent, per Benzinga's quote data 14. Cantor Fitzgerald cut its target to $109 the day after earnings, B. Riley initiated at $124 in July, and Northland went to $95 on 18 September 10.
Benzinga's own consensus average sits at $85.60 10, and MarketScreener's calendar alone records a 20 September addition to the S&P Global BMI index, the kind of inclusion that puts index funds on the buyer side of a falling tape 1.
Every target and consensus average sits far above the $49.85 price
- Estimate
Data
| Value | |
|---|---|
| B. Riley (July) (estimate) | $124 |
| Cantor Fitzgerald (estimate) | $109 |
| Mean of six analysts (estimate) | $105 |
| Northland (18 Sep.) (estimate) | $95 |
| Benzinga consensus avg. (estimate) | $85.6 |
| SHAZ close, 1 Oct. | $49.85 |
The tell lands in November
The interest clock runs whether the GPUs bill or not. Next reading: the earnings report estimated for 15 November, then the fourth-quarter print that management itself frames as the moment contracted revenue becomes recognized 910. If the ramp arrives, 9.95 percent was cheap money and $105 looks sober. If it slips, the lenders hold the chips and the contracts, and the analysts' clients hold the rest. One desk priced the GPUs. The other priced the story.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.