Tata's Besi partnership is a study, not an order, and Besi trades at 74x
Tata Electronics put a Dutch equipment maker's name on its $3 billion Assam packaging plant this week. The memorandum commits studies and staff training, not tools, and Besi's 74.3x earnings multiple leaves no room for a memorandum to stay one.
 Vincent Jiang · 3 min read
The verbs are assess and evaluate
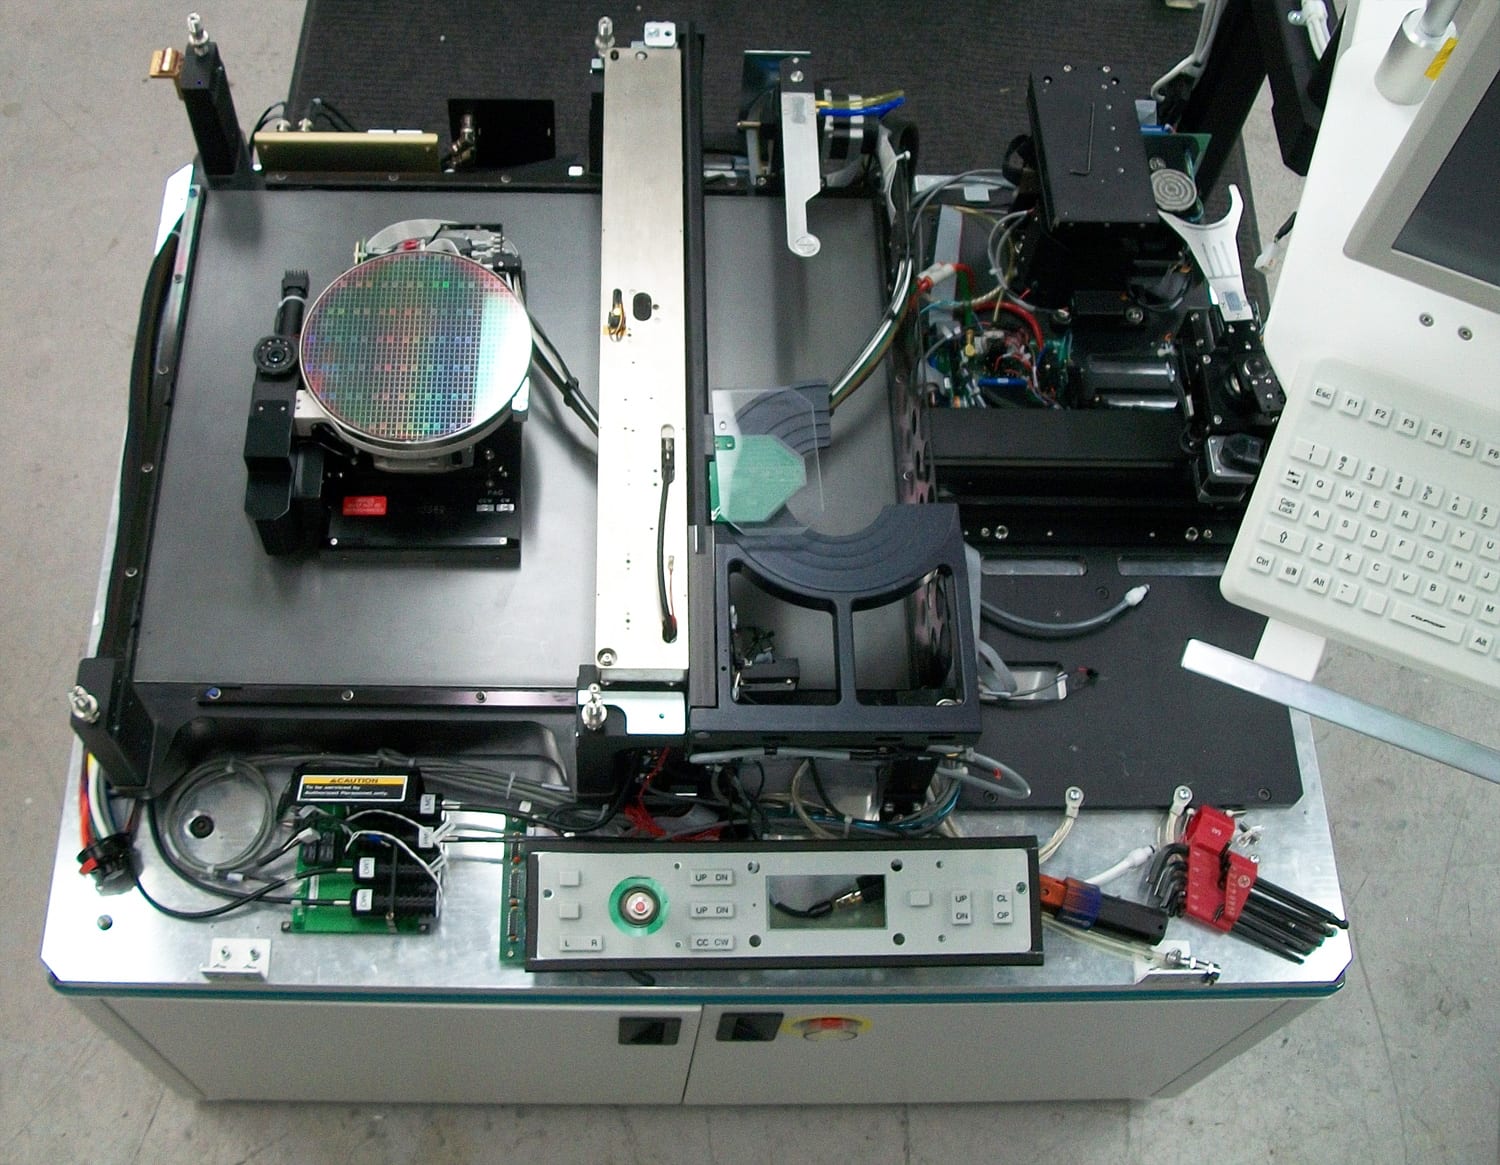
Tata Electronics and Besi signed a memorandum of understanding on 29 September to strengthen advanced packaging at Jagiroad in Assam, site of India's first indigenous packaging plant and a Tata investment of about $3 billion 1. Read the release as a contract and it announces a study, not a purchase: the partners will "assess opportunities" in India's equipment-support ecosystem, Besi will "evaluate initiatives" in training and certifying Tata staff, and the text carries no order value, no tool count and no delivery date 1. The trade press's daily updates filed it under ecosystem progress all the same 2.
Seven handshakes in under two weeks
Tata's own newsroom shows the cadence. Six partnership announcements landed across 17 and 18 September alone, from Enomoto and Sumitomo Chemical to L&T Semiconductor, and Besi is the seventh handshake in under two weeks 3. Each one banks credibility for Jagiroad: a plant costing ₹27,000 crore, designed for up to 48 million chips a day and 15,000 direct jobs, with production targeted inside the fiscal year ending March 2027 41.
The multiple pays for conversion
Besi's side of the ledger is thinner. Its investor-relations release list, as of 1 October, still tops out at the 23 July second-quarter results; there is no Besi release on Assam 5. What Besi has put out is an order book: Q2 orders of €292.9 million, up 128.8 percent year on year, with AI-linked demand about 60 percent of system orders in early 2026, and a June decision to lift long-term revenue targets to €1.7 billion to €2.2 billion 678. At €191.9 the shares trade at 74.3x earnings against peers at 40.5x, after a 34.5 percent slide over 90 days, and the most-followed bull model calls them 36 percent undervalued at €300.36 7. As The Inference noted on 27 September, when Besi's system orders rose 129 percent and its stock had fallen 46 percent, the trade is conversion: the multiple needs new geographies to become booked orders. The MoU does not do that.
Besi's 74.3x P/E is nearly double the peer average and well above its own bull case's fair ratio
- Estimate
Data
| Value | |
|---|---|
| Besi (BESI.AS) | 74.3x |
| Bull-case fair ratio (estimate) (estimate) | 51x |
| Peer average | 40.5x |
The bull case is not empty
The bulls stand on shipped metal, not promises: Q2 revenue rose 68.7 percent to €249.9 million at a 65.7 percent gross margin, carried by hybrid bonding, photonics and datacenter applications 6. The open question is narrower than either camp admits: what a signature in Assam adds to a book that is already doubling.
The test lands 22 October
The next evidence is dated. Besi releases its 2026 third-quarter results on 22 October 9. Until a Jagiroad tool order appears in that book, the only money committed in this story is Tata's. Tata bought credibility; Besi's shareholders are being asked to pay for conversion.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.