Accelevation paid its sponsor $299 million pre-IPO, then drew $400 million of bank debt; stock below $18
Two weeks after pricing below its marketed range, the data center equipment maker is funding its next leg with $400 million of bank debt and future share sales, having paid its pre-IPO owners a $299 million distribution before listing. Today it begins paying ownership awards to more than 1,800 workers.
 Richard Tang · 4 min read
On October 9, nine days into public life, Accelevation drew $400 million of bank debt: a $250 million term loan plus $150 million from a new revolver, replacing the credit lines its IPO proceeds had just repaid 1. The next leg of this data center buildout is funded by lenders, not by the offering.
Bank debt and the sellers' exit dwarf the company's own raise
Data
| Gross proceeds | |
|---|---|
| Bank debt drawn 9 Oct | $400M |
| Sellers' gross IPO proceeds | $360M |
| Company's gross raise | $180M |
Today, October 16, the Miamisburg, Ohio company begins paying ownership awards to more than 1,800 employees 2. Its shares, around $13.69, sit about a quarter below the $18 issue price 3.
The sponsor cashed out twice before the market opened
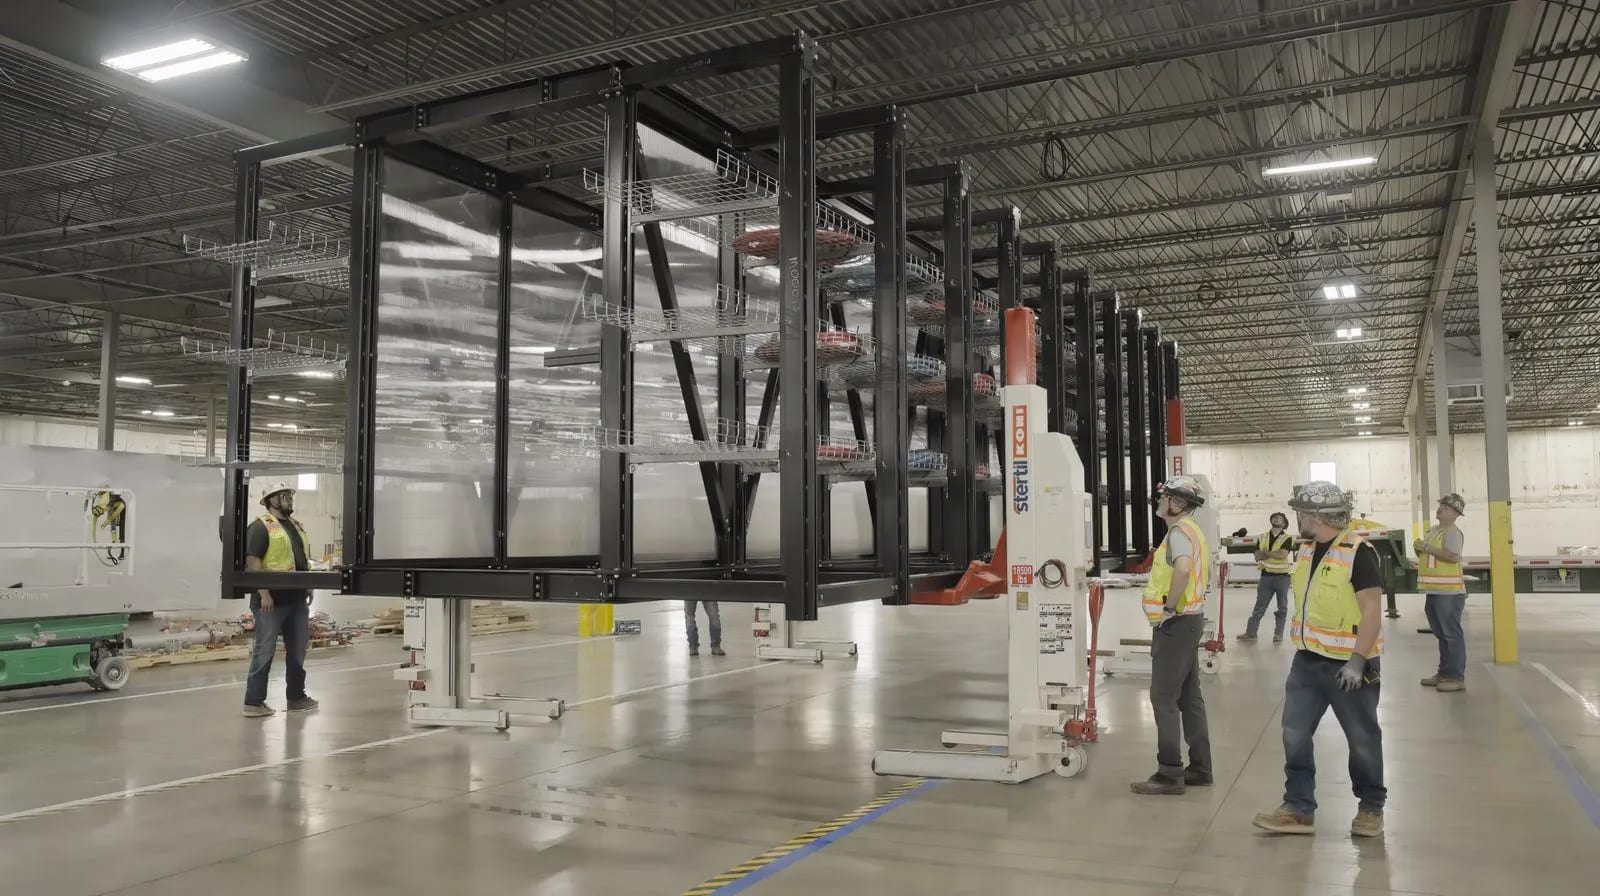
Accelevation builds the power, cooling and structural systems that turn a bare data center shell into "white space", the hall where the servers live, and ships them factory-built 4. For hyperscale customers, that fit-out is the bottleneck: first-half revenue rose 176% to $437.5 million, and backlog more than tripled to $1.11 billion 45.
The financing ran the other way. In June the company borrowed $346 million of incremental term loans, primarily to fund a $299 million distribution to its pre-IPO owners 4. At the September 30 offering, holders affiliated with its private equity sponsor, Olympus Partners, sold 20 million of the 30 million shares 4.
Public buyers paid less than private ones
The deal priced at $18, 10% below the bottom of its marketed range, and Olympus still holds about 85% of the votes 45. The sellers also supplied the banks' 4.5 million-share over-allotment option, the extra shares underwriters may buy to cover excess demand, and sold 2.8 million of those within days 34. The company kept $171 million before expenses, all of it routed to debt repayment 4.
Private money is paying more for the same boom: investors valued Crusoe$26.61B — Crusoe, private, latest valuation $26.61B, a builder of AI compute capacity, at $30.9 billion in September 6. The public discount tracks where the money went, toward repayments and a sponsor exit rather than new capacity 5.
Bank debt and the sellers' exit dwarf the company's own raise
Data
| Value | |
|---|---|
| Bank debt drawn on 9 Oct | $400M |
| Sellers' gross IPO proceeds | $360M |
| Company's gross IPO raise | $180M |
The next leg of the buildout is bank money, and cheaper
The new facilities, led by Bank of America−0.60% — Bank of America, down 0.60 percent today, run to 2031: a $250 million term loan plus a $400 million revolver, $150 million of it drawn at closing 1. Pricing starts at term SOFR, the floating-rate benchmark, plus 2.25%, stepping down as leverage falls 1.
Refinancing cuts the borrowing spread from up to 5.25 points over SOFR to 2.25
- From
- To
Data
| From | To | Change | |
|---|---|---|---|
| Old MidCap facilities | 4.50 pts over SOFR | 5.25 pts over SOFR | +16.7% |
| New facilities | 2.25 pts over SOFR | 2.25 pts over SOFR | 0.0% |
The MidCap facilities the deal replaced cost 4.50 to 5.25 points over the same benchmark 7. Chief Financial Officer Ken Krause called the refinancing cheaper capital with room to keep investing 7. The undrawn $250 million of the revolver is now the growth budget, because the offering never was 1.
Ownership reaches the shop floor, funded by future share sales
Built Together is the part of the AI boom worth copying: cash, 401(k) retirement contributions and restricted stock units expected to reach $100,000 to $250,000 per eligible employee over two years, entry-level manufacturing staff included 2. "Higher wages can improve lives, but ownership changes futures," said Chief Executive Michael Rubiera 2.
The program was written into the January 2025 Olympus investment, not added for the listing 2. Later awards, though, arrive only with future equity transactions, subject to market conditions 2: the share sales that fund capacity also fund the workers' second year.
A tax receivable agreement, standard in private-equity listings, will also pay Olympus-controlled entities 85% of the listing's tax savings, up to $589.8 million 4. Rubiera has bought about $3.7 million of stock since the debut; the Olympus fund sold $360 million of it 8.
The first outside marks open on October 24
No analyst ratings cover the stock yet 3. The prospectus runs through October 24, its 25th day, after which the underwriting banks' analysts typically launch coverage 4. Their first marks must weigh two customers that produced 61.2% of last year's direct revenue against first-half free cash flow of negative $15.8 million 45.
The sponsor has been paid twice and keeps control. The lenders who funded October's draw, the public holders sitting below water, and the employees whose second-year awards depend on the next share sale now carry the risk of a buildout that burns cash while it grows.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.