AeroVironment is down 43% despite a record $1.5 billion backlog and a $464.8 million Army laser win
AVAV closed October 7 at $138.45, down 43% for the year on a $7.16B market cap, just above the $135.20 low it touched this week. Restated accounts, a disclosed material weakness and a terminated $1.7B Space Force contract are outweighing record backlog: the stock trades on trust, not demand.
 Vincent Jiang · 3 min read
A quiet newsroom, a loud tape
AeroVironment's newsroom has published nothing since its September 9 earnings release 1. The stock has not been quiet. AVAV touched a 52-week low of $135.20 this week and closed October 7 at $138.45, down 43% for the year and two-thirds below its $417.86 high, on a $7.16B market cap 2. The question is not whether the company is winning work. It is whether anyone believes the filings.
The demand ledger
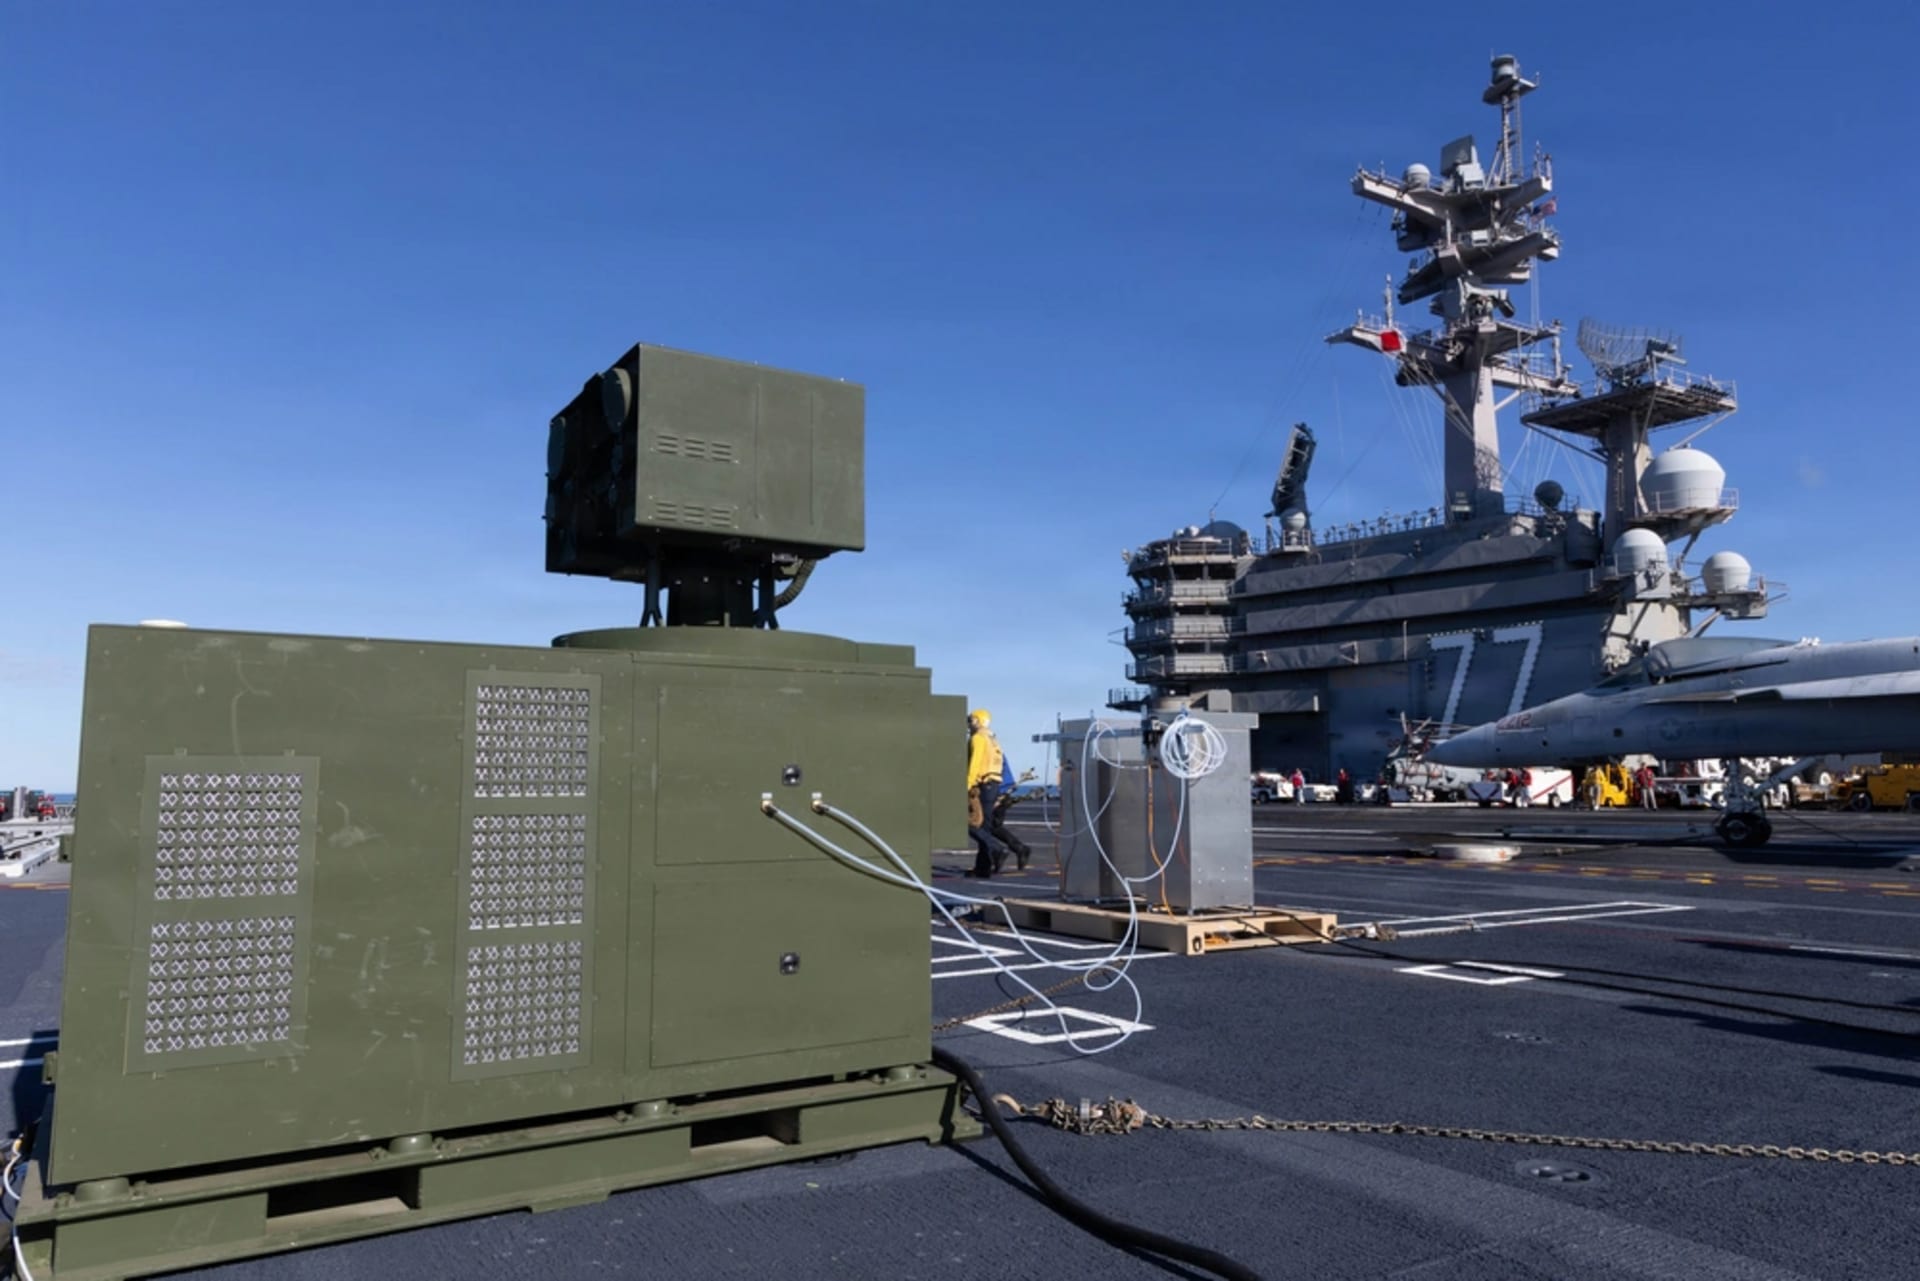
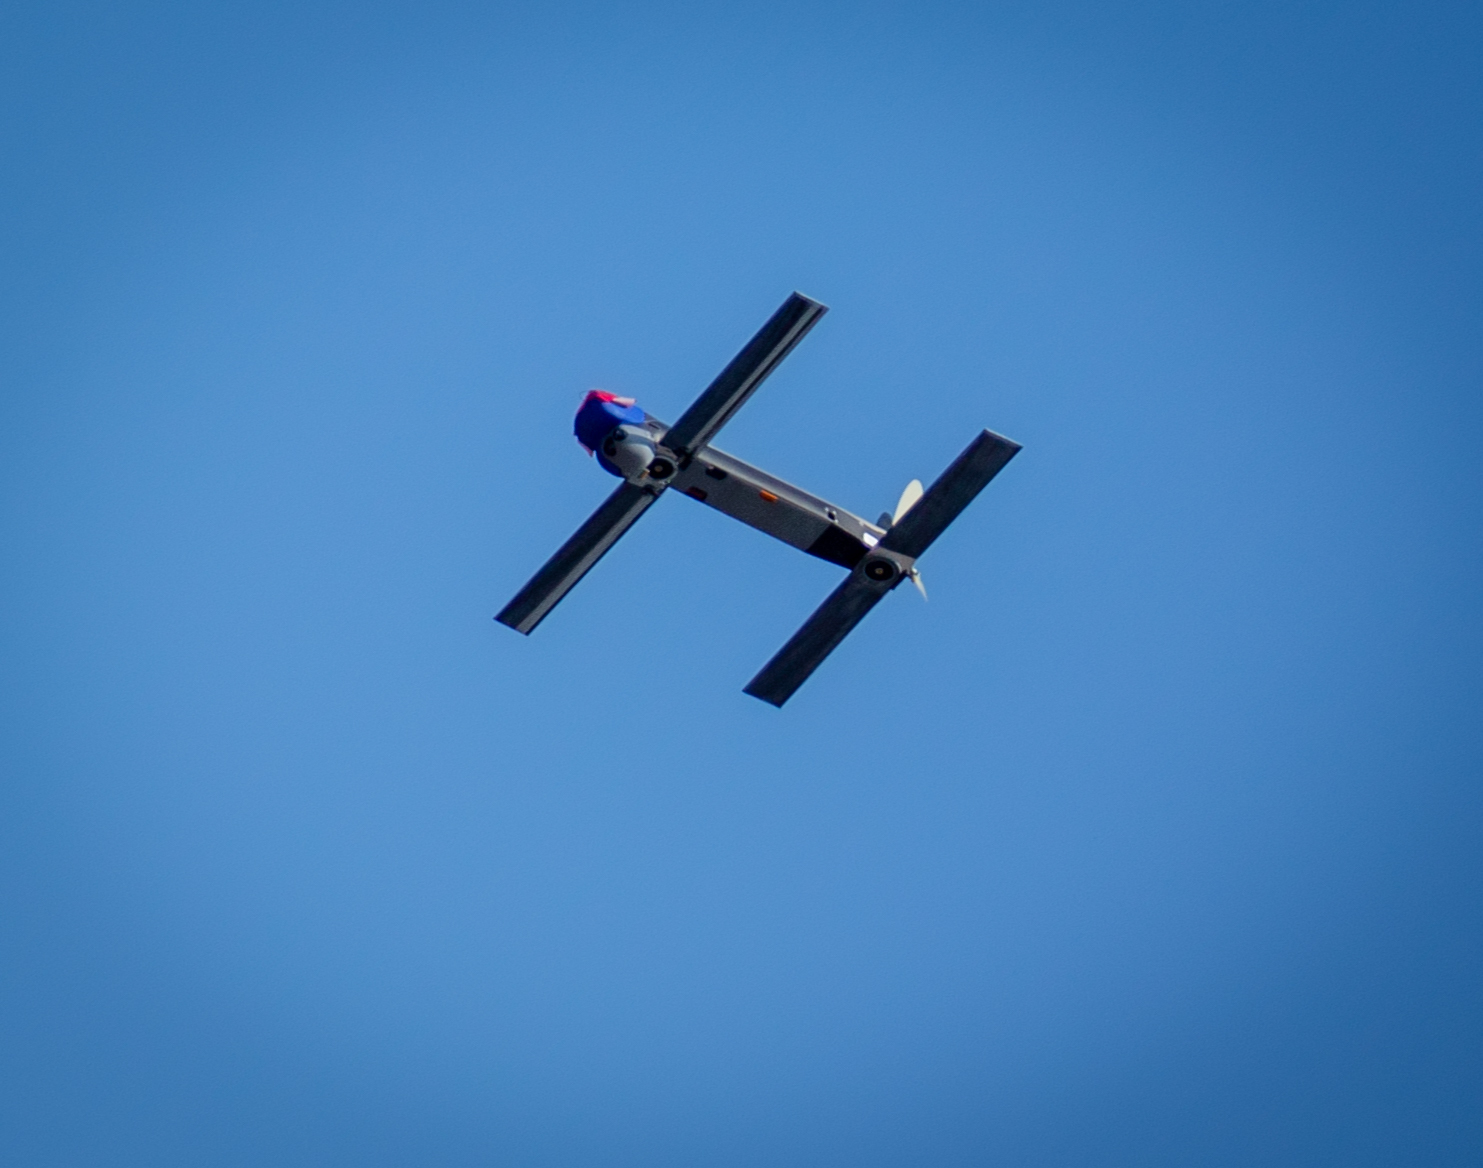
Since August 20 the announcements have stacked up: a Greek industrial venture through AV Eagle, a $100M Southern California campus, a $51M Army order for Switchblade 600 loitering munitions, three autonomous helicopters for NASA's SkyFall Mars mission, and a first international LOCUST order 1. The centerpiece landed September 2: $464.8M from the Army to field dozens of 30-kilowatt LOCUST X3 lasers on JLTVs, which AV calls the first US production contract for directed energy 3.
Fiscal Q1, ended August 1, posted record revenue of $480.5M, up 6%, on record funded backlog of $1.5B, up 37% 4. The quarter booked $0.7B of orders, a 1.4 book-to-bill 45.
Quarterly revenue stepped up in mid-2025 and has run between $408M and $642M since
Data
| Revenue | |
|---|---|
| Q3 '23 | $180.82M |
| Q4 '23 | $186.58M |
| Q1 '24 | $196.98M |
| Q2 '24 | $189.48M |
| Q3 '24 | $188.46M |
| Q4 '24 | $167.64M |
| Q1 '25 | $275.05M |
| Q2 '25 | $454.68M |
| Q3 '25 | $472.51M |
| Q4 '25 | $408.05M |
| Q1 '26 | $641.62M |
| Q2 '26 | $480.49M |
The trust ledger
The other ledger belongs to the SEC. A June 22 filing restated the quarter ended January 31: operating loss understated by $89.4M, net loss by $87.3M, because the Space unit's goodwill-impairment math omitted goodwill allocated from acquired deferred taxes 6. The trigger was the Space Force's termination for convenience of the estimated $1.7B SCAR antenna contract 7. The same filing disclosed a newly identified material weakness in internal controls, and securities class actions now target what executives said about the program 68.
Fiscal 2026 closed with a $265M net loss on $241M of goodwill impairment 4. Governance churned around it: both directors who joined as Arlington Capital designees resigned June 17, and audit-committee member Stephen Page retired at term end in September; every filing cites no disagreement 69.
The defense: clean books fell harder
Kratos is down 45% this year with no restatement and no lawsuits 2. Red Cat is down 23% 2. The JEDI drone ETF sits up 0.9% while SPY gained 14% 2.
Clean books fell harder: the drone derating runs past one restatement
Data
| Year-to-date change | |
|---|---|
| Kratos | -45% |
| AeroVironment | -43% |
| Red Cat | -23% |
| JEDI drone ETF | 0.9% |
| SPY | 14% |
The derating is sector-wide, and only AVAV adds litigation and an open material weakness on top. No source splits the discount between sector and company damage; both ledgers are being marked down at once.
The verdict watch
Three dates price the gap: SCAR white papers due October 15, the fiscal Q2 print in early December, and prototype installation awards expected in early 2027 10. AV says it will re-bid SCAR with a redesigned BADGER antenna on commercial terms 10. Last year's Q2 report landed December 9 11. Between them run the slower tests: class-action resolution, controls remediation, and LOCUST deliveries turning the $464.8M award into revenue. Backlog is counted in dollars. The discount is counted in credibility.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.