Amkor's 10-day slide to $41.82 prices Nvidia's $1.5 billion as a prepayment, not committed revenue
Ten straight lower closes have run into a best-ever second quarter, a Nvidia prepayment and a bigger Arizona campus plan. The gap between Amkor's filings and its share price sits in the footnotes, and third-quarter results on October 26 will price it.
 Richard Tang · 3 min read
Amkor Technology−6.02% — Amkor Technology, down 6.02 percent today, which assembles and tests other companies' chips, closed at $41.82 on Friday, its tenth straight lower session 1. Ten falling sessions have erased about $3.5 billion of market value 1. The S&P 500 slipped 0.8% over the same stretch 1, so the repricing is Amkor's own, and the footnotes in its filings are the likeliest reason.
The boom is in the filings
Amkor's June quarter was its best second quarter on record, $1.9 billion in sales with net income more than tripling 2. Management guides the September quarter to $1.95–2.05 billion in sales, an 18.5–19.5% gross margin and $0.72–0.82 in earnings per share 2. Computing, the data-center end market, is guided to grow about 30% from the prior quarter on AI demand and a server-processor packaging ramp 2.
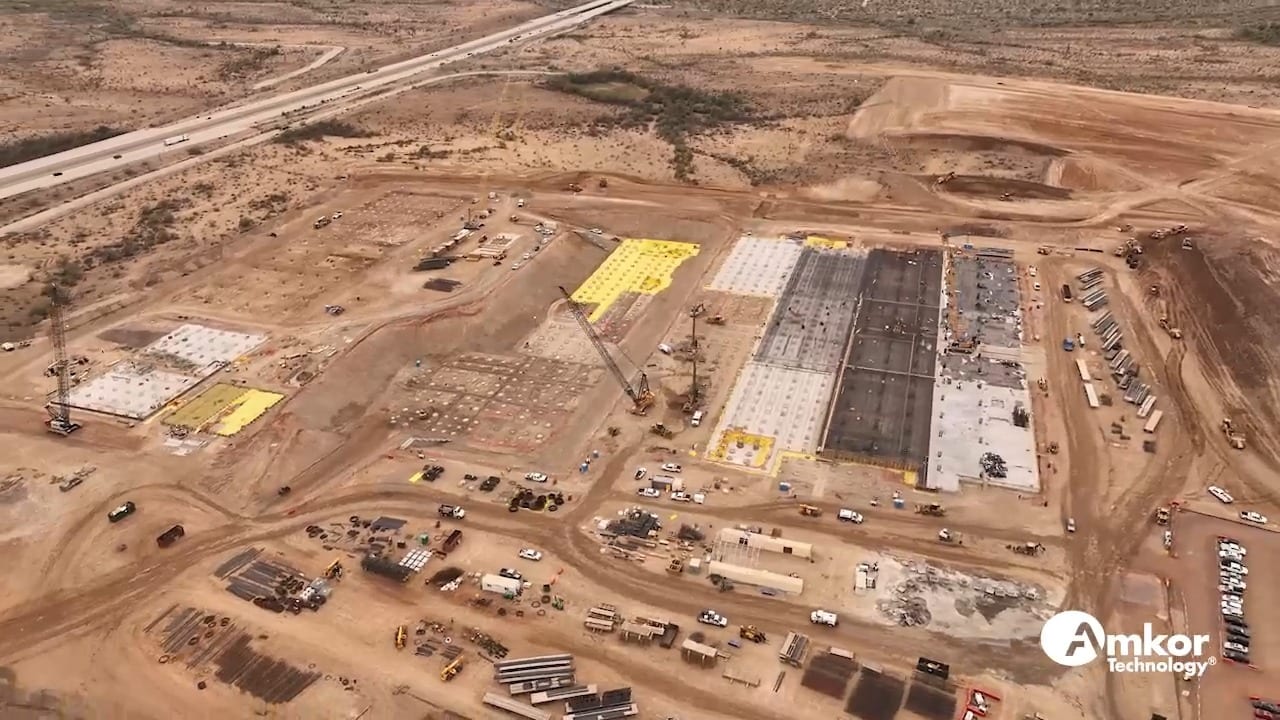
The deal flow matches. In July, a multiyear Nvidia packaging partnership lifted Amkor's shares 17% in after-hours trading 3. June brought a ten-year packaging framework with TSMC−2.33% — TSMC, down 2.33 percent today, the world's largest contract chipmaker 2. September raised the plan for the Arizona packaging campus to about $12 billion 4.
Q2 2026 was Amkor's best second quarter, not its best quarter
Data
| Net sales | |
|---|---|
| Q3 '23 | $1.82B |
| Q4 '23 | $1.75B |
| Q1 '24 | $1.37B |
| Q2 '24 | $1.46B |
| Q3 '24 | $1.86B |
| Q4 '24 | $1.63B |
| Q1 '25 | $1.32B |
| Q2 '25 | $1.51B |
| Q3 '25 | $1.99B |
| Q4 '25 | $1.89B |
| Q1 '26 | $1.69B |
| Q2 '26 | $1.9B |
Every boom headline has a footnote
Two weeks of selling suggest investors have read the footnotes. Nvidia's−1.59% — Nvidia, down 1.59 percent today $1.5 billion is a prepayment, expected from 2027 and returned as US services rather than committed revenue 2. The TSMC framework is capacity and ecosystem, not named wafer dollars 2. The earnings release's own caution flags the absence of backlog or short-term customer commitments 2.
The customer mix adds weight. Smartphones and tablets are still the largest end market at 42% of sales 2, and Android volumes fell 20% last quarter on memory-supply shortages 2.
Smartphones are still Amkor's largest end market
- Communications (smartphones, tablets)4242%
- Computing (data center, PC, storage)2222%
- Automotive, industrial and other2222%
- Consumer1414%
Data
| Slice | Value | Share |
|---|---|---|
| Communications (smartphones, tablets) | 42 | 42% |
| Computing (data center, PC, storage) | 22 | 22% |
| Automotive, industrial and other | 22 | 22% |
| Consumer | 14 | 14% |
The cash ledger leans the same way. Amkor guides 2026 capital spending to $2.5–3.0 billion 2. First-half operating cash flow was $382 million 2.
Insiders sold $992 million of stock over the past year with no purchases reported 6, a total swollen by the founding Kim family's February share sale 2. Even after the fall, GuruFocus still calls the shares 17% overvalued 6.
The bull case has evidence too
ChipMOS−5.96% — ChipMOS, down 5.96 percent today, a Taiwanese packaging peer, posted record third-quarter revenue on October 8 as AI demand outran memory supply 7. Its shares still fell 4.8% on Friday 8. Trefis, which tallied Amkor's streak, notes the company's revenue growth sits above its sector median and its earnings multiple below it, and argues the business looks sturdier than the stock 1.
Retail traders are picking the other side of the insiders' exits. On the forum Stocktwits, 6,404 accounts follow the ticker, the sentiment gauge reads bullish, and the most-liked recent posts are buying the dip 9.
Amkor reports third-quarter results on October 26 2. If Computing grows near its guided pace and gross margin lands at the top of the guided range, this slide was the market being early. If it misses, the discount has further to run. Nvidia paying years ahead says the buildout is real; the unfinished step is turning committed capacity into collected cash, and the results will measure it.
More about NVIDIA
NVDA · Fiscal Q2 2027Revenue rose 106% to $96.2B, 92.5% of it from Data Center, “driven by the ramp of our Blackwell Ultra infrastructure”. Gains on equity stakes of $7.8B lifted net income to $59.7B.
Show as a table
| Line | Value |
|---|---|
| Revenue | $96.2B |
| Gross margin | 75.0% |
| Operating margin | 66.2% |
| Net income | $59.7B |
| Hyperscale | $48.7B |
| AI clouds & enterprise | $40.3B |
| Data Center | $89.0B |
| Edge Computing | $7.2B |
| Gross profit | $72.1B |
| Cost of revenue | $24.1B |
| Other income | $7.8B |
| Operating income | $63.7B |
| Operating expenses | $8.4B |
| Tax | $11.8B |
| R&D | $7.1B |
| SG&A | $1.4B |
Deepdive
AI-generated from this story and its cited sources. Not investment advice.