Axon's Customers Face a Costly Exit. Shareholders Face an Expensive Entry.
The moat is real: fourteen petabytes of police evidence do not move for free. The entry price assumes that moat compounds cash at 87 times.
 Vincent Jiangsix-minute read
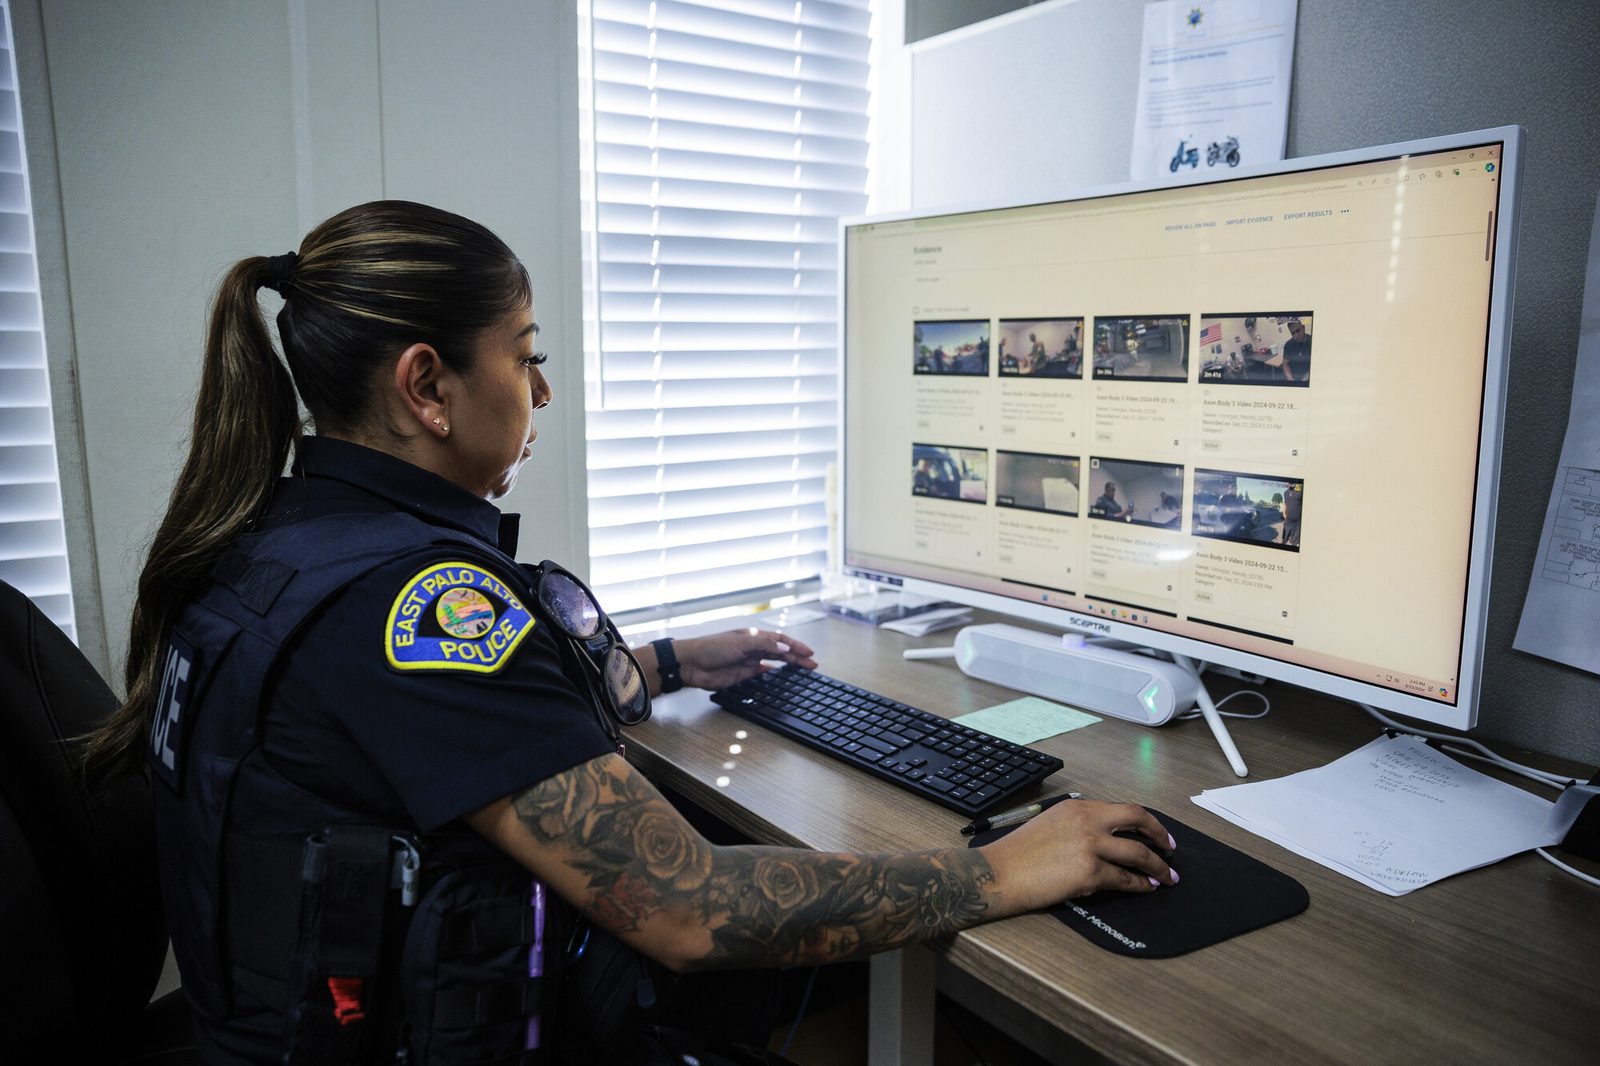
The memo that priced the exit
In May, Los Angeles budget chief Matthew Szabo sent the city's budget committee an analysis of a proposed ten-year Axon+2.39% — Axon, up 2.39 percent today renewal. The package cost $221.3 million including tax.1
Walking away would mean replacing equipment, retraining people and moving years of police evidence.1
Eighty-seven times the cash
That is a valuable position for a vendor. At the September 11 closing price, Axon's equity was worth approximately $39 billion, or 87 times management's expected 2026 free cash flow.5,3,4
The tension is whether a business this difficult to replace can grow into a price this demanding.
The latest results show considerable momentum. The August 5 release reported second-quarter revenue growth of 35%, annual recurring revenue growth of 39% and net revenue retention of 126%.2 That last measure tracks recurring software, support and warranty revenue from existing customers. It is evidence that Axon can sell more into accounts it already has, although it does not isolate AI's contribution.
The moat is the migration
The commercial mechanism starts with the camera and continues long after an officer removes it. Recordings need storage, classification, controlled access, redaction and sharing with investigators and prosecutors. Each additional task gives an incumbent another opportunity to earn recurring revenue. A department replacing the camera must think about the evidence system around it.
Los Angeles makes that dependency tangible. Its memo describes more than 14 petabytes of evidence, docks across 40 facilities and equipment in over 1,600 vehicles. It also says the city owns its data and negotiated free export.1
Those rights matter. But removing an export charge does not perform the migration, preserve the working relationships between records or train the next shift.
The workload keeps accumulating. Atlanta's city auditor counted more than 753,000 body-camera videos uploaded during the first ten months of 2024, under a ten-year agreement covering equipment and services across several departments.6 Records generated today create work beyond the original encounter. That does not establish that every additional software module earns its fee.
Competition still exists. Motorola Solutions offers cameras, digital evidence management, transcription, redaction and prosecutor sharing, and an agency can compare alternative systems.7 The advantage rests in the cost and risk of replacing an installed workflow, reinforced by useful integration. Calling every feature unique would misunderstand the moat.
Fifty-six minutes, and a trial that could not find them
AI gives Axon another way to monetize that position. Draft One turns body-camera audio and officer context into a draft narrative, which an officer must review.8 The agency already has the recording and the vendor relationship. That distribution advantage is substantial. The customer, however, buys a completed, accountable report, and the work between an initial draft and that outcome determines the return.
A historical contract shows how modest the required benefit can be. East Palo Alto's July 2024 procurement packet quoted Draft One at $70.52 per user per month.9 Assume, for illustration, that usable officer time is worth $75 an hour. The license alone would cover its cost with about 56 minutes of net time saved monthly, before transcription, training and other implementation costs. That is a capacity calculation, not automatic payroll savings, and the quote is not a universal current price.
But the word “net” has to survive measurement. A preregistered Manchester, New Hampshire experiment involving 85 officers and 755 reports found no statistically significant reduction in report-completion time.10 It studied an early version at one agency, and assignment to access did not mean use on every report. The finding does not prove the product cannot help. It does show why faster narrative generation cannot be substituted for measured improvement in the whole task.
Permission also limits the addressable workload. Hillsborough County's sheriff introduced Draft One in February 2026 for non-criminal calls only, requiring substantive edits and deputy approval.11 A tool licensed across an agency may initially be usable on only part of its work. Adoption, eligible reports and actual time recovered are different measurements.
The officer and the software vendor do not control every decision. In September 2024, King County prosecutor Dan Clark told police chiefs his office would not accept AI-assisted narratives.12 In California today, the law requires AI disclosure, officer verification, retention of the first draft and an audit trail.13 Those obligations belong inside the productivity calculation.
Axon has adapted: its prosecutor guidance says US agencies gained original-draft retention in December 2025.14 An established supplier that can implement these requirements may strengthen its position. Compliance is therefore both an operating cost and a potential advantage over a less integrated competitor.
For shareholders, the corresponding test is cash per share. Software and services revenue grew 36% in the second quarter, while that segment's gross margin fell from 75.6% to 71.3%.2 Management attributes pressure to services and newer offerings; it says software-only margins remain above 80%. Implementation work can create valuable future subscriptions, but it consumes resources today.
The bookings headline also needs interpretation. The $15.1 billion of future contracted bookings compares with $9.8 billion of remaining performance obligations under revenue-accounting rules.2,3 The broader measure includes arrangements those rules exclude. Treating every booked dollar as equally certain future revenue would overstate the visibility.
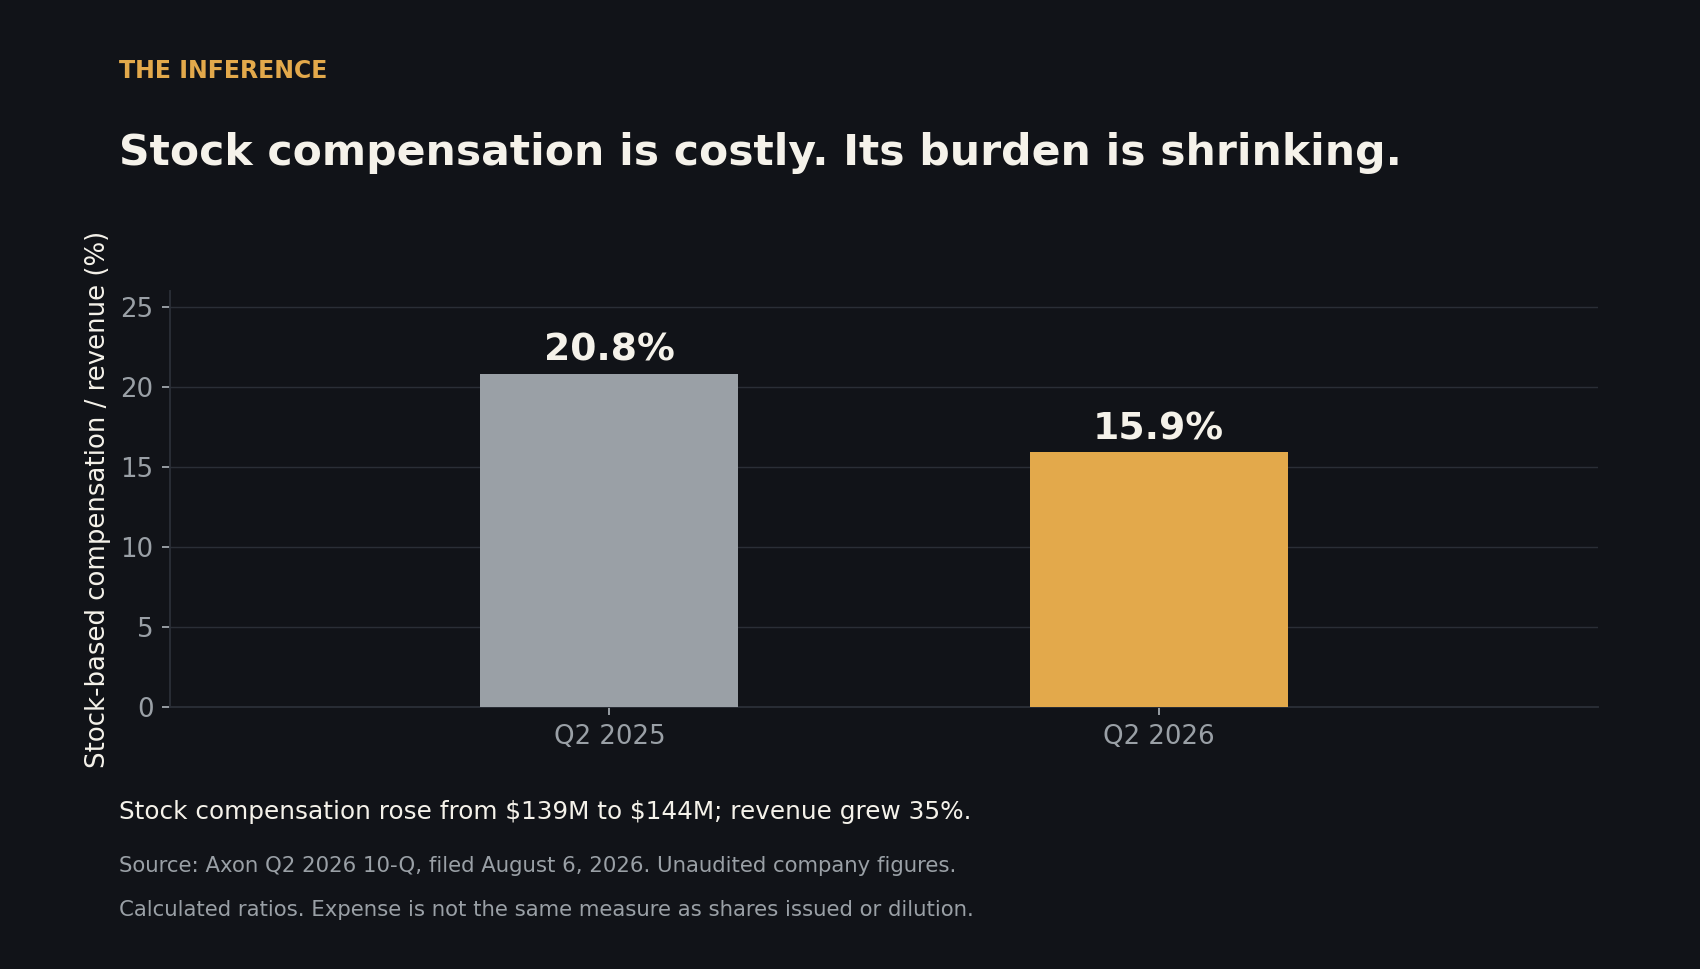
Compensation is expensive, but its direction is improving. Quarterly stock-based compensation increased from $139 million to $144 million while revenue grew much faster. The cost fell from 20.8% to 15.9% of sales, calculated from the filing.3 Excluding it can help compare operating trends; it cannot make the ownership transferred to employees economically free.
A moat protects the company's economics, not the shareholder's entry price.
That distinction becomes uncomfortable in a simple valuation exercise. Use the September 11 close of $479.34, July's reported share count and management's $450 million 2026 free-cash-flow expectation. Assume five years of growth, 2% annual share dilution and a terminal valuation of 30 times free cash flow. These are scenario assumptions, not forecasts or a price target.5,3,4
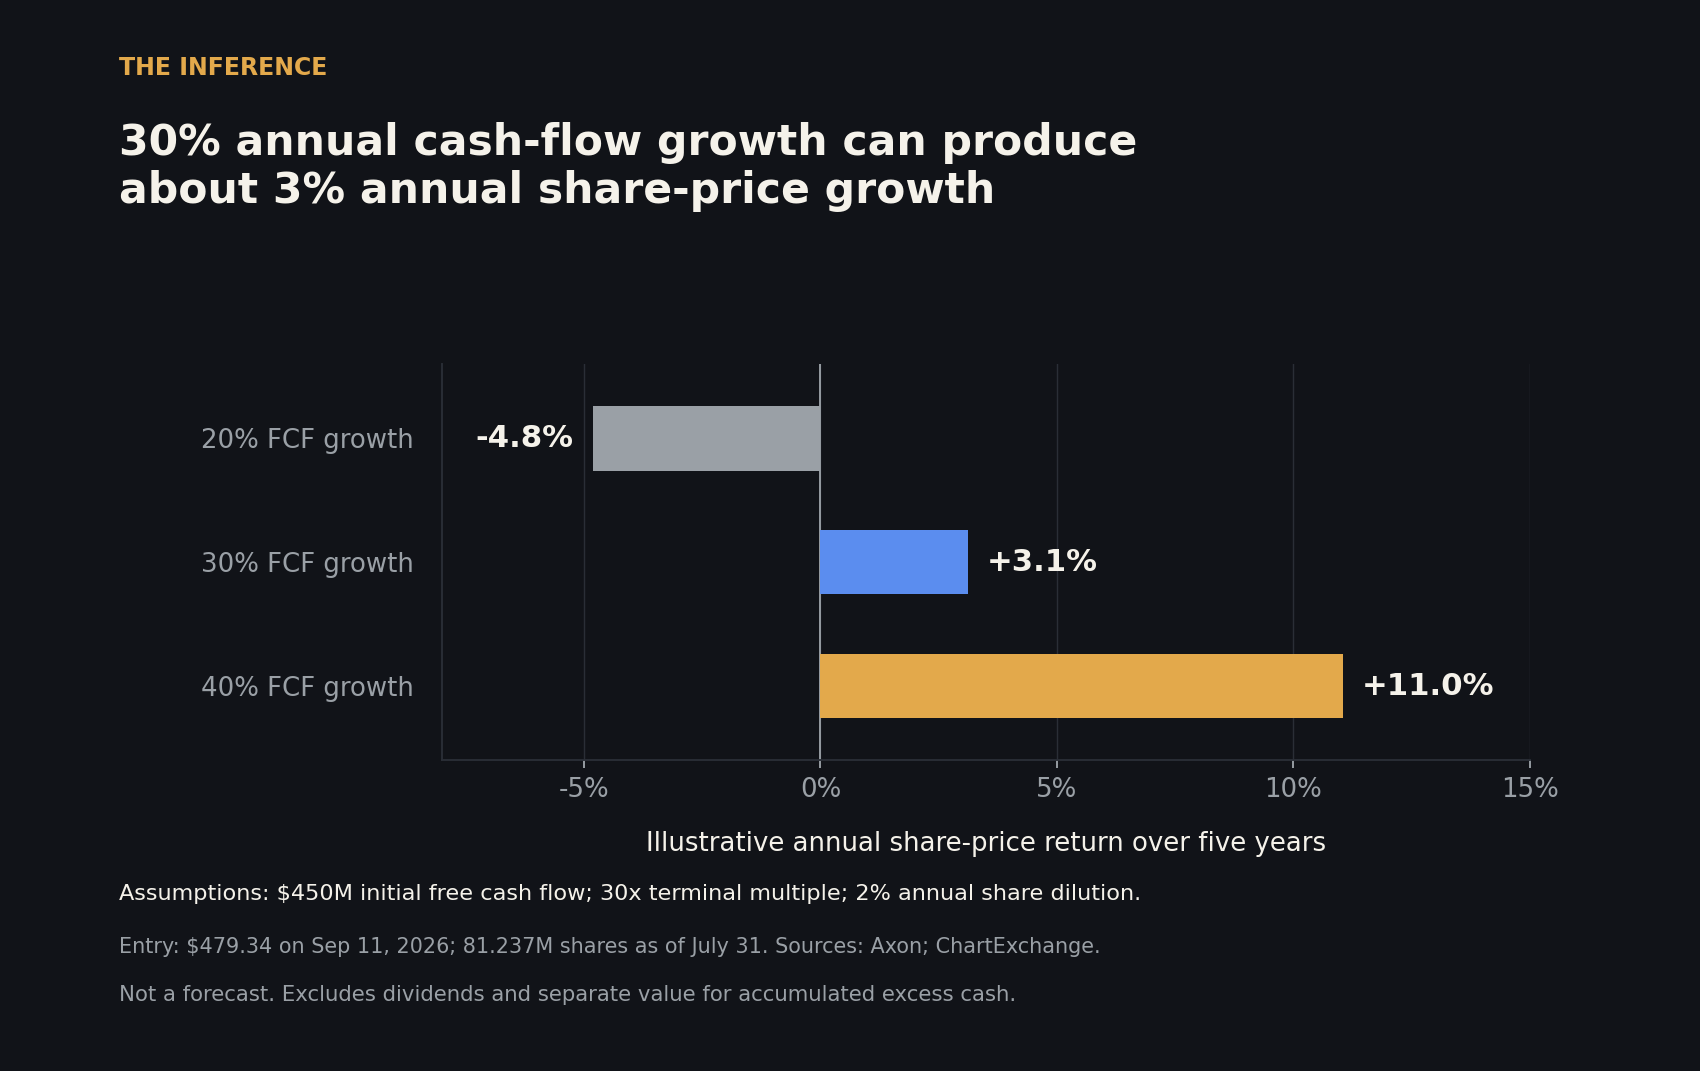
At 30% annual cash-flow growth, the modeled annual share-price return is only about 3%. At 40% growth, it reaches about 11%. Faster cash conversion, less dilution or a higher exit multiple would improve the result. It shows the burden of the entry price, rather than a complete valuation.
The bull case compounds longer than the model
The strongest bullish case deserves respect. An installed customer can buy more software without repeating the entire original deployment. Upfront equipment and implementation costs can precede years of recurring revenue. Modest time savings could justify AI fees, and the shrinking compensation burden shows revenue growth beginning to spread some costs over a larger base.2,3 A five-year model can also undervalue a business that compounds for much longer.
The evidence supports that possibility. It does not settle the rate of cash growth available to each share.
Watch cash per share, not bookings
Management expects cash generation to concentrate in the fourth quarter; the first half's negative free cash flow should therefore be assessed against that promised recovery.4,3 The immediate tests are the year-end cash result, dilution and whether expanding services lead to durable software margins.
For the next results, put cash per share beside the bookings headline.
Get Robotics & Defense by email, free
Robots, self-driving vehicles, drones and AI in defense. In our daily email, every weekday.
Reader comments
0 comments