Chinese tools were one reason Hua Hong came in ¥1.26bn under budget; Hwatsing wants ¥3.8bn
A 27 September STAR filing shows Hua Hong finished its 8-inch upgrade ¥1.257 billion under its ¥2 billion allocation, with a higher share of Chinese equipment one stated reason, and is steering about ¥5.5 billion into a $6.95 billion Wuxi line. Days later, the toolmaker whose catalogue matches the replaced tools won Shanghai's nod to ask shareholders for up to ¥3.80 billion.
 Vincent Jiang · 3 min read
The nod, and the filing that explains it
Hwatsing Technology, China's leading producer of chemical mechanical polishing equipment 5, won the Shanghai bourse's nod on 1 October to file documents for a private placement of up to ¥3.80 billion in A-shares; the underwriting summary is filed 23. Four days earlier, a STAR Market disclosure from Hua Hong, the country's second-largest contract chipmaker, showed the demand side: an 8-inch upgrade that closed about ¥1.257 billion under its ¥2 billion allocation, with a higher share of purchases from Chinese equipment suppliers named as one reason 14.
The savings are going straight to Wuxi
Hua Hong is redirecting about ¥2.5 billion left over from the upgrade and a research project, plus ¥3 billion raised above target, roughly ¥5.5 billion in all, into Wuxi Phase III: a $6.95 billion 12-inch specialty line rated at 55,000 wafers a month, due to begin operations by the end of 2027 1.
The project sits in a joint venture with the state Big Fund's Hua Xin vehicle: Hua Hong and its Shanghai subsidiary are putting in $2.1 billion for a controlling 51% of $4.2 billion in funding 4. The hurry is real, with second-quarter revenue at a record $717.5 million, up 26.8%, and fabs running at 103% utilisation 47.
The overlap no filing names
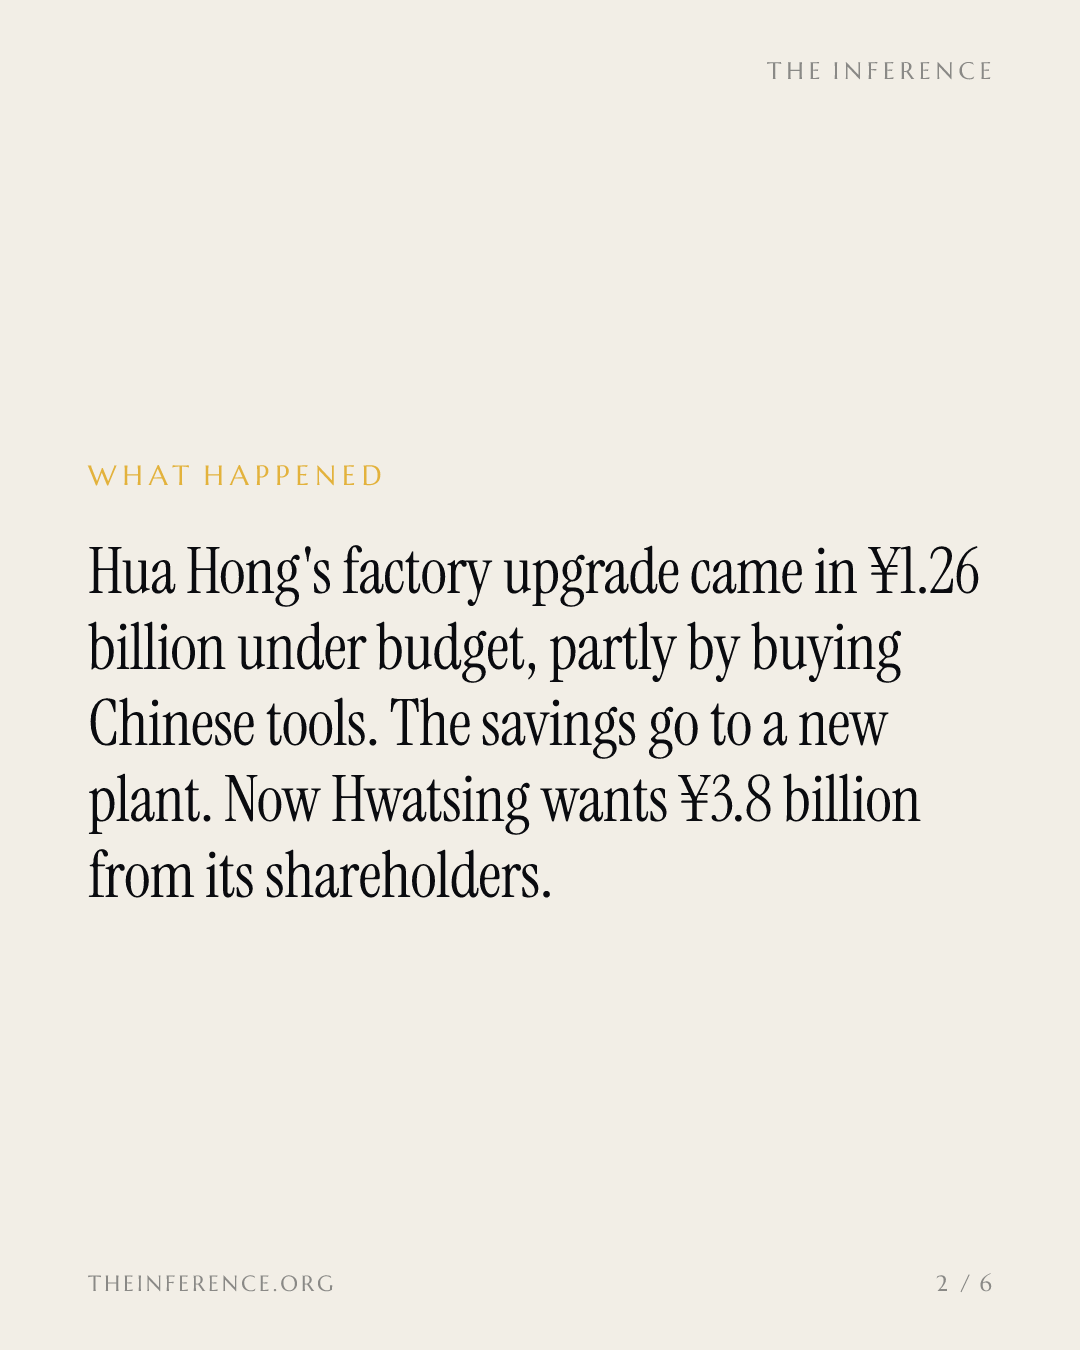
Neither filing names Hua Hong's suppliers, and nothing fetched here ties Hwatsing to that fab. What the record shows is a catalogue match: Hua Hong replaced dry etching, thin-film deposition, ion implantation, wet cleaning, CMP and metrology tools 1; Hwatsing sells CMP, implant, wet-processing and thinning tools 2. It drove most of China's rise in global CMP share, from about 1.5% in 2022 to almost 11% in 2023, and shipped its 1,000th system in April 5.
Hwatsing's ¥3.8bn ask is 63 times the buyback it just closed
Data
| Value | |
|---|---|
| Hua Hong funds to Wuxi Phase III | ¥5.5B |
| Hwatsing placement ask | ¥3.8B |
| Hua Hong 8-inch under-spend | ¥1.26B |
| Hwatsing buyback | ¥0.0602B |
Cheap for the fab, thin for the toolmaker
The bargain shows up in Hwatsing's own margins. In 2025 revenue reached ¥4,648 million while net income barely moved at ¥1,084 million 6; the first half of 2026 repeats the shape, revenue up 36%, attributable profit up 11% 2. The placement would fund capacity, wafer reclamation services and high-end tool development 5, after a Hong Kong listing plan was scrapped in April 2. In China's substitution drive, the fab banks the discount and the toolmaker's shareholders advance the capital.
Hwatsing's revenue is compounding; its profit is not
- Revenue
- Net income
Data
| Revenue | Net income | |
|---|---|---|
| 2021 | ¥804.88M | ¥198.28M |
| 2022 | ¥1,648.84M | ¥501.6M |
| 2023 | ¥2,507.99M | ¥723.75M |
| 2024 | ¥3,406.23M | ¥1,023.41M |
| 2025 | ¥4,648.23M | ¥1,083.72M |
Holders pay ¥227.43; bulls point to 35% self-sufficiency
Holders are asked to fund it at ¥227.43, up 112% this year, weeks after a buyback that bought 0.09% of the company for ¥60.22 million 2; the ask is roughly 63 times that outlay. The bulls have material: six analysts carry a mean buy and a ¥264.80 average target 2, and Hua Hong's chairman said in May he saw no impact from US export controls on Wuxi procurement 4. Tool self-sufficiency is near 35% 5. What the bull case cannot answer is whether profit ever follows the revenue.
The reading on 31 October
Third-quarter results land on 31 October 2, the first test of whether net income catches up. The placement's pricing against ¥227.43 2, and the Wuxi tool orders that follow, will name who actually collected the substitution premium.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.