ChronoScale Promises $1 Billion in AI Revenue on $71.6 Million of Booked Sales
ChronoScale, Applied Digital's cloud business folded into an exoskeleton maker's Nasdaq listing in May, says contracts now "provide for" $1 billion of annualized run-rate revenue by Q3 2027. The same release defines that figure as one quarter of contract revenue multiplied by four, "not a forecast," and conditions it on capital the company has not raised.
 Vincent Jiang · 2 min read
A billion-dollar AI year, announced from an exoskeleton listing
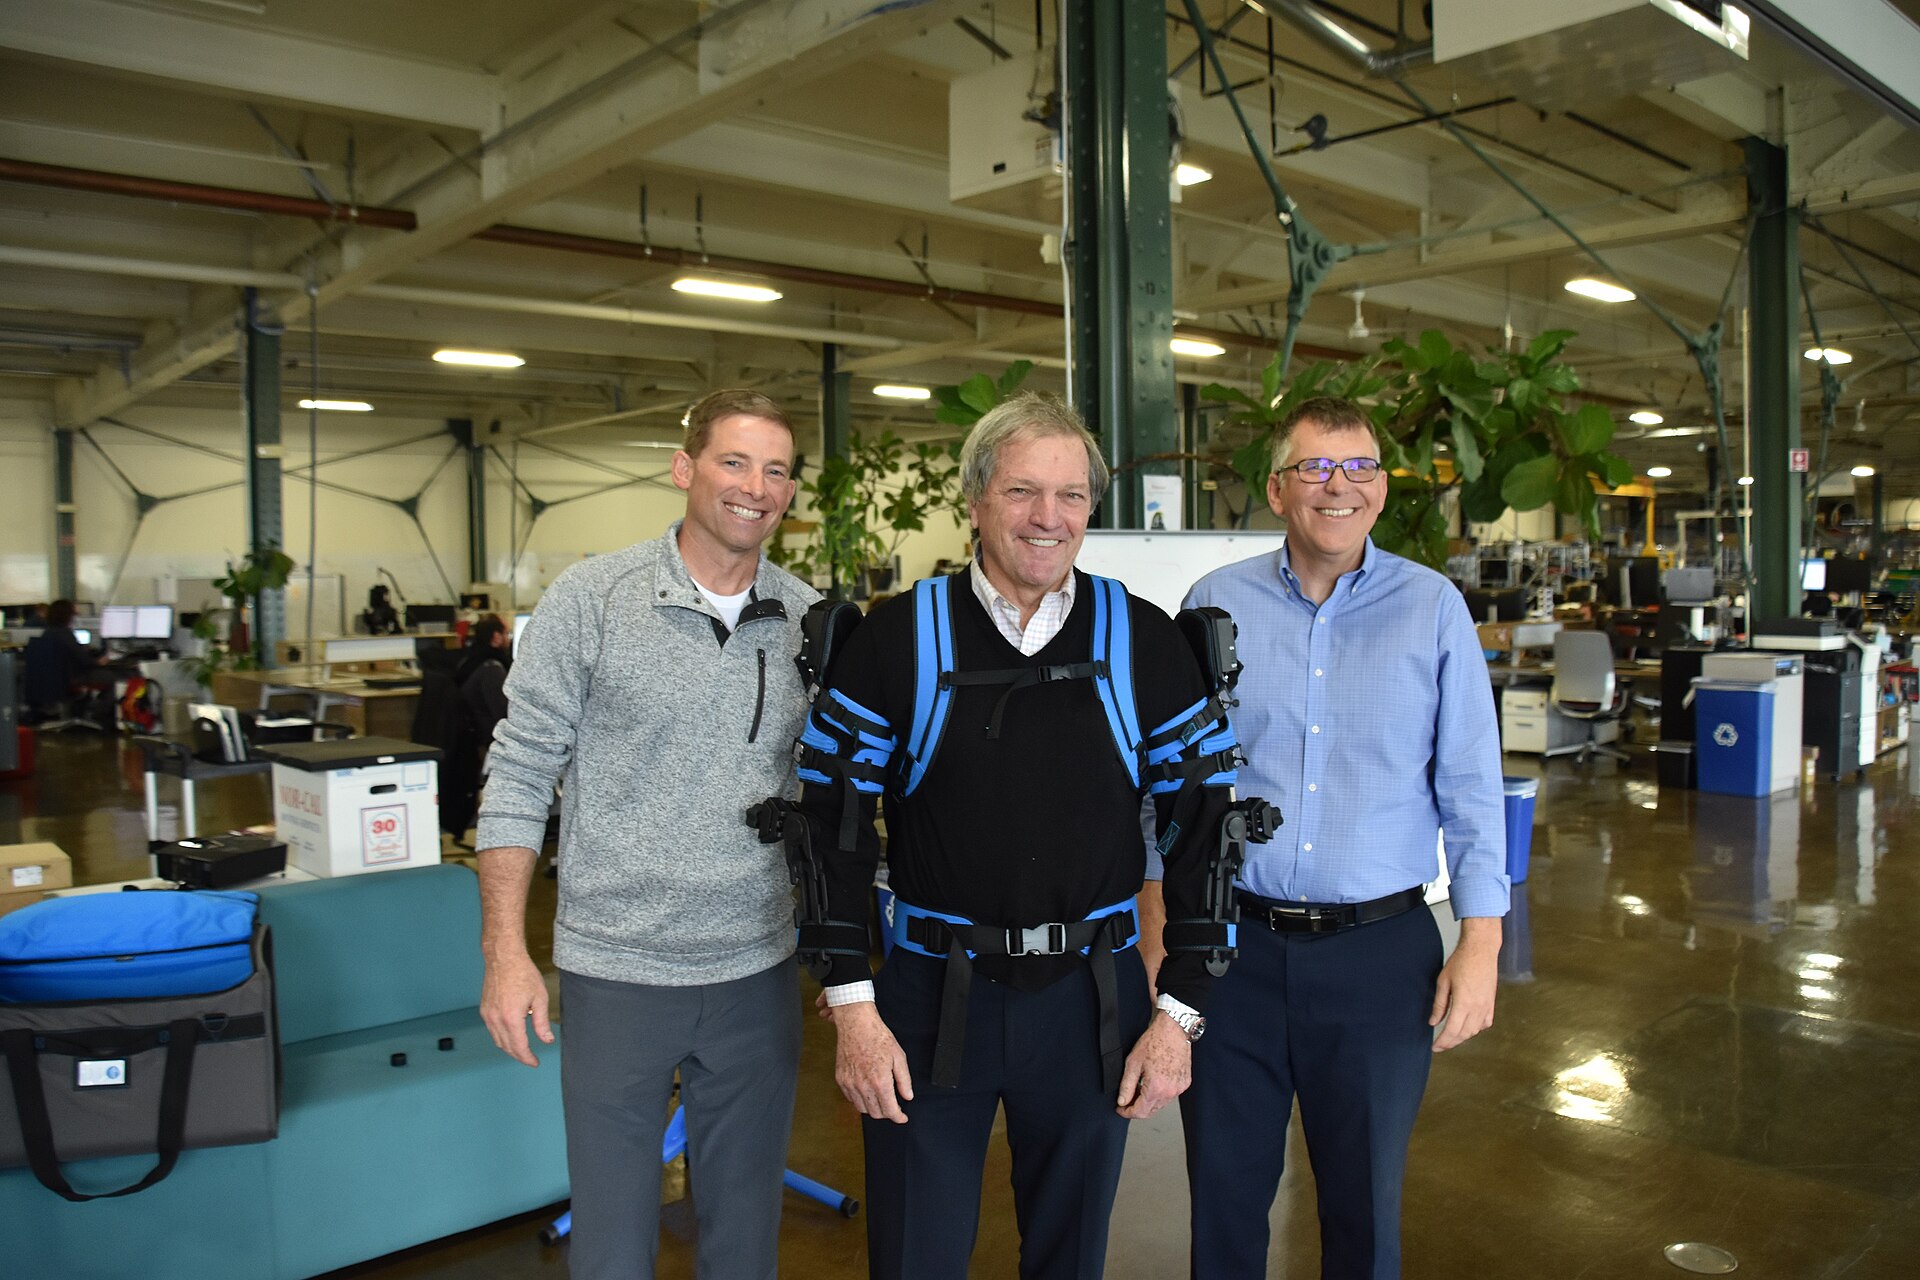
On 1 October, ChronoScale Holdings said two AI infrastructure agreements, together with existing contracts, "provide for" $1 billion of annualized run-rate revenue by calendar Q3 2027 1. The stock closed that day at $19.37, up 124.19 percent for the year 4. Five months ago this listing made exoskeletons: ChronoScale is Applied Digital's cloud business, merged into EKSO Bionics in May, and its market profile still files 86 employees under Advanced Medical Equipment and Technology 24.
Index money is already inside
Passive funds were drafted in when the stock joined five Russell indexes on 28 and 29 June 4. Sell-side coverage is one analyst: Northland initiated on 18 September at Outperform, target $32 3. Market value now stands near $2.8 billion 7.
The billion is defined in a footnote
Annualized run-rate, the release explains, is a non-GAAP operating metric: revenue recognized under contracts in one quarter, multiplied by four, "based on current assumptions and not a forecast of revenue for any specific reporting period" 1. Achievement is conditioned on deployment, power, equipment and "the Company's ability to access capital on acceptable terms" 1. The visible financing is a secured promissory note from B. Riley Commercial Capital, first amended 16 September, terms not disclosed in public filings reached for this piece 4.
Booked revenue: $71.6 million, one customer
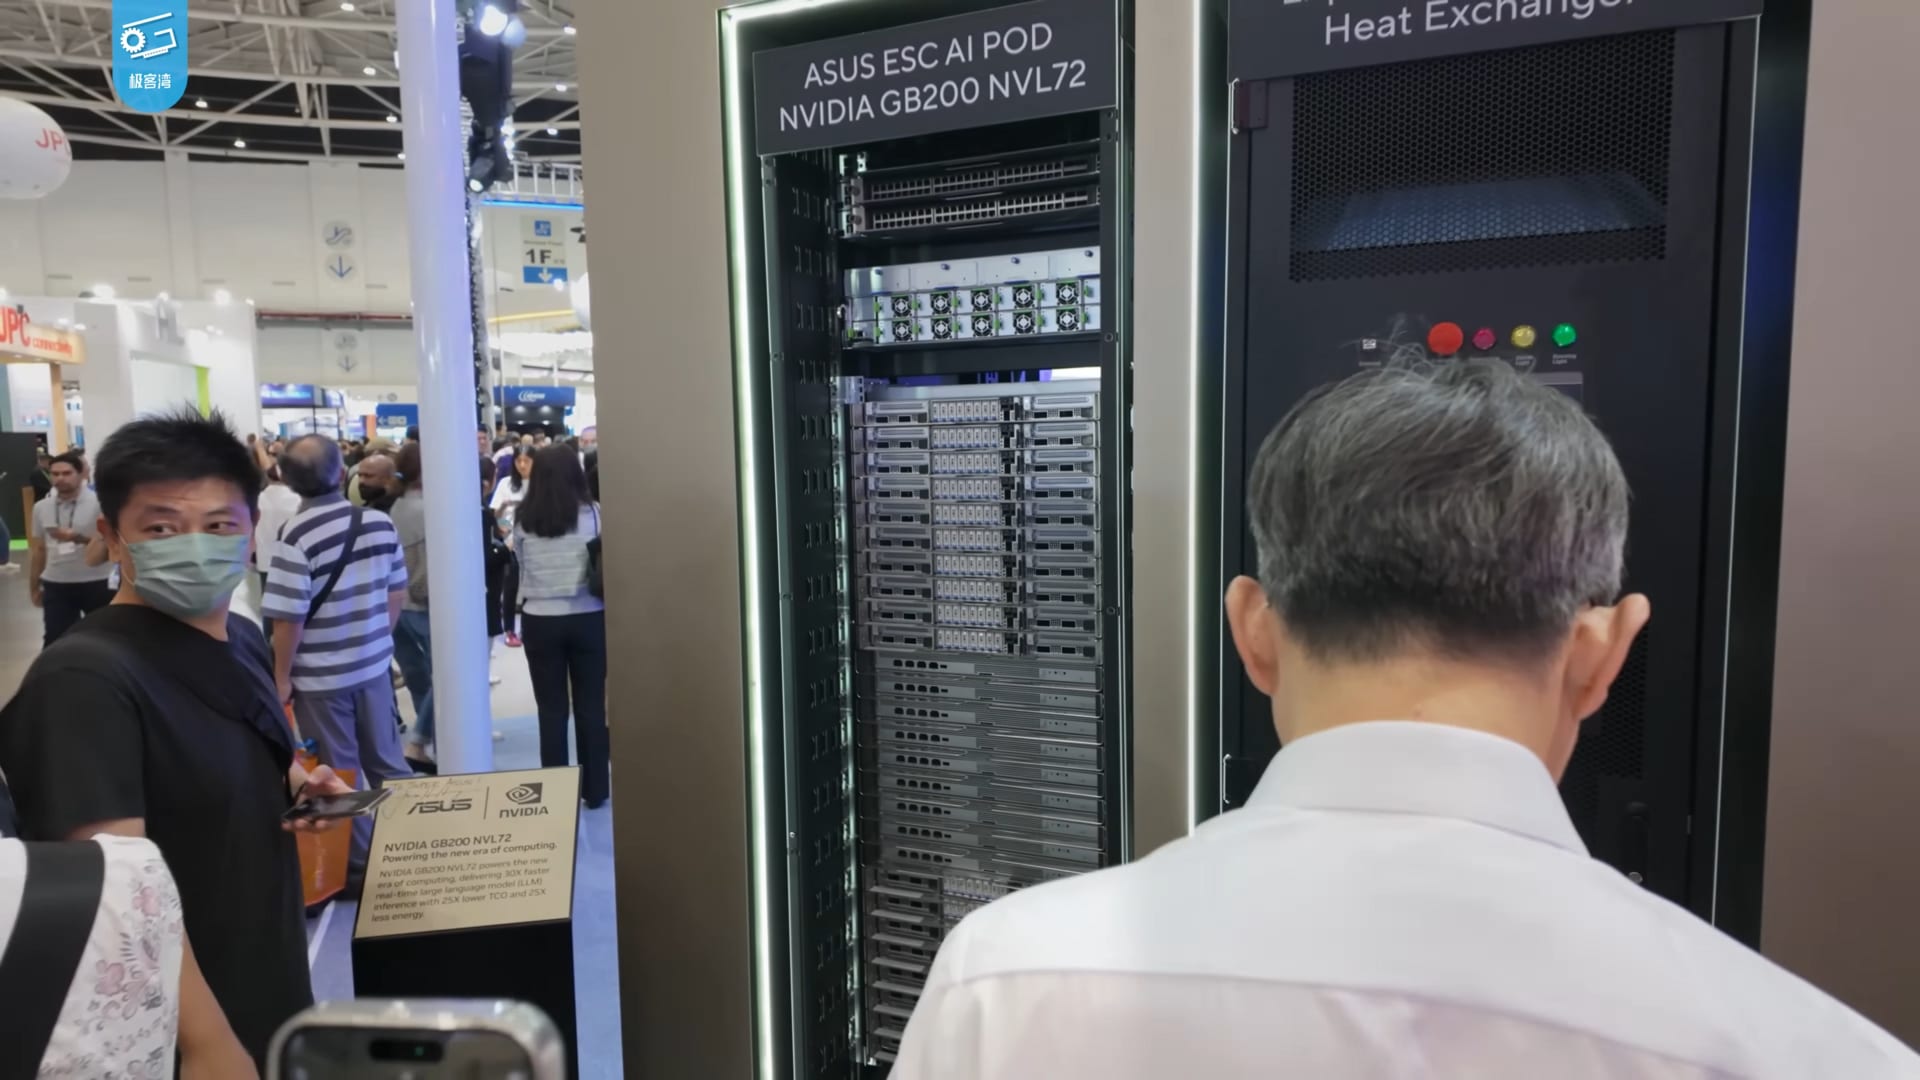
For fiscal 2026, ended 31 May, ChronoScale reported revenue of $71.6 million and a net loss of about $50.3 million, most of it from a single customer, Together AI 2. The Microsoft partnership of 27 August is a planned 50-megawatt deployment on NVIDIA GB300 NVL72 racks, targeted for completion by Q1 2027, with no project pricing or committed revenue disclosed 56.
The market pays $2.8 billion for $71.6 million of booked revenue
- Estimate
Data
| Value | |
|---|---|
| Market value, 3 Oct 2026 | $2,800M |
| Contracted run-rate target, Q3 2027 (estimate) | $1,000M |
| FY2026 booked revenue | $71.6M |
The bull case, stated fairly
There is real recurring revenue, and Microsoft, NVIDIA and Nutanix are engaged by name 25. Northland's $32 target implies two-thirds upside 3, and short interest of 12.3 percent of float as of 14 August is squeeze fuel 6. None of it prices the Microsoft work or funds the GPUs, which the release itself concedes 1.
The tell is the financing
Watch for an equity raise or project debt sized for 50 megawatts of GB300s, and for commissioning milestones at the Microsoft build against its Q1 2027 target 26. The checklist for any AI-pivot microcap is short: does the release define its run-rate, disclose contract value, name its capital. ChronoScale did one of three.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.