Dell is up 347% as its $192 billion guide passes the memory bill to customers; Micron sees tightness to 2028
Dell closed October 6 at $571.75, up 347 percent for the year, with Mizuho at a $650 target. The guide underneath carries a price leg: Dell's own operating chief ties part of the lift to memory costs passed through to buyers, and Micron says memory stays tight through 2028.
 Vincent Jiang · 3 min read
October is repricing September's words
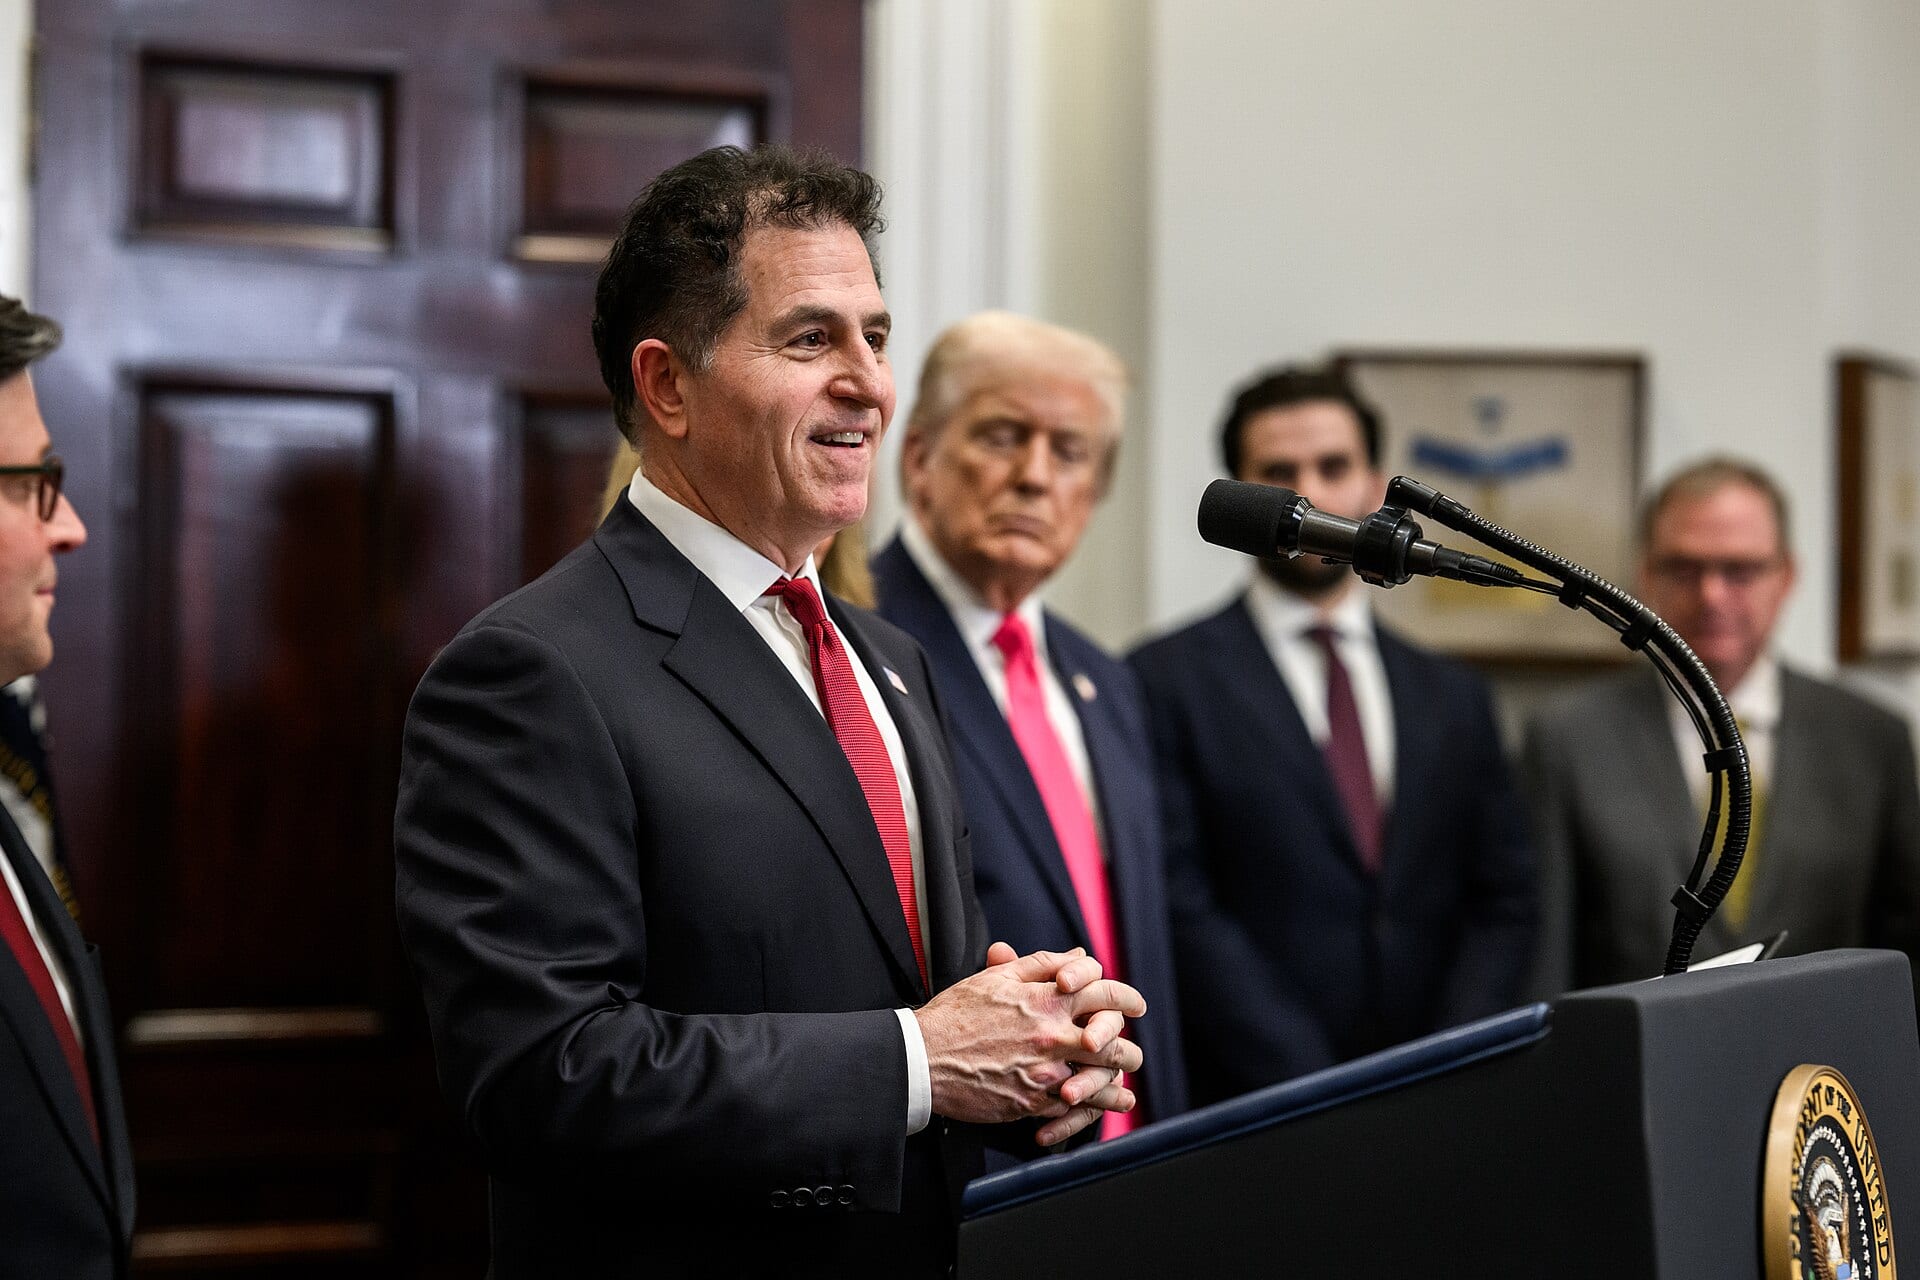
Dell closed at $571.75 on October 6, up 347 percent for the year and close to its $588.40 high, after Mizuho's Vijay Rakesh lifted his price target to $650 from $600 1. The target rests on a September 1 print: $60.9 billion of AI server orders in a quarter, a $95 billion backlog, a $192 billion fiscal 2027 guide 1. The fine print is Dell's own: operating chief Jeff Clarke attributed part of the revenue strength to price adjustments stemming from rising input costs 2.
The quarter's headline comparison, $60.9 billion of AI orders against $47.0 billion of total revenue 13, says demand outruns supply. Clarke's line adds the other half: some of what customers pay is the memory squeeze itself, repriced and passed along 2.
The guide has a price leg as surely as a volume leg
The margin record shows the pass-through arriving. The infrastructure segment's operating margin hit 15 percent, up from 10.5 percent the prior quarter, on what Dell calls disciplined pricing despite substantial inflation in memory component costs 4. Clarke's list of constrained parts begins with DRAM and NAND 3.
Micron expects memory and storage to be much tighter in calendar 2027 and 2028 than in 2026, with more than 75 percent of its fiscal 2027 output already committed 5. The guide lifted to $192 billion of revenue and $25.50 of adjusted EPS, from $165 to 169 billion and $17.90 2, was written inside that market.
Earnings are arriving before the cash
Net income more than tripled to $4.13 billion, from $1.16 billion a year earlier 2, while operating cash flow fell to $2.2 billion from $2.5 billion 4. Inventories have doubled since January to $21.3 billion, and the financing arm's receivables climbed to $20.4 billion from $14.3 billion; adjusted free cash flow, with that lending added back, was $8.1 billion 4. Growth this shape consumes cash before it produces it.
Revenue doubled while operating cash flow stayed flat
- Revenue
- Operating cash flow
Data
| Revenue | Operating cash flow | |
|---|---|---|
| Q3 '24 | $24.4B | $1.6B |
| Q4 '24 | $23.9B | $0.6B |
| Q1 '25 | $23.4B | $2.8B |
| Q2 '25 | $29.8B | $2.5B |
| Q3 '25 | $27B | $1.2B |
| Q4 '25 | $33.4B | $4.7B |
| Q1 '26 | $43.8B | $4.1B |
| Q2 '26 | $47B | $2.2B |
Gross margin fell as AI servers scaled, then recovered as pricing caught up
Data
| Gross margin | |
|---|---|
| FQ3 '25 | 22% |
| FQ4 '25 | 23.7% |
| FQ1 '26 | 21.1% |
| FQ2 '26 | 18.3% |
| FQ3 '26 | 20.7% |
| FQ4 '26 | 20.2% |
| FQ1 '27 | 17.8% |
| FQ2 '27 | 20.9% |
The backlog is priced in 2026 memory
Pass-through protects the margin on what ships; the exposure sits in what has not. The backlog's named customers include Iren, the cloud infrastructure provider behind a $1.6 billion hardware order, signed in a market Micron says only gets tighter 25. TD Cowen, at Hold with a $550 target, says the backlog leans on major neocloud customers and calls memory constraints a 2027 risk 6. Morgan Stanley, Equal-Weight at $511, calls Dell clearly out-executing and still prefers HPE 6. Retail sentiment on Stocktwits reads bearish 6, and Silver Lake's $1.07 billion of third-quarter selling fits a 2013-vintage fund exiting on schedule more than a verdict 7.
What the next print settles
The third-quarter guide calls for $49.0 billion of revenue and $6.50 in adjusted EPS, against street expectations of $41.42 billion and $4.49 2, with roughly $19 billion of AI server revenue versus the $16.4 billion shipped last quarter 3. The $74 billion full-year AI target needs almost $21 billion a quarter from here 4. Dell has not published the split between units and price inside its $192 billion, and that omission is the tell.
The Q3 guide sits far above the street on both lines
- Dell guide
- Street
Data
| Dell guide | Street | |
|---|---|---|
| Revenue | $49 | $41.42 |
| Adjusted EPS | $6.5 | $4.49 |
If units stall while price carries the guide, the market is paying a growth multiple for a component invoice. The computers are real. So is the memory bill inside them.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.