FICO's $10 mortgage toll just met its 99-cent rival on the same grid
FHFA is folding VantageScore into the single pricing grid behind every conventional mortgage, with no start date. FICO slid 18% in premarket trade as TransUnion locked the rival score at 99 cents through 2028.
 Vincent Jiang · 3 min read
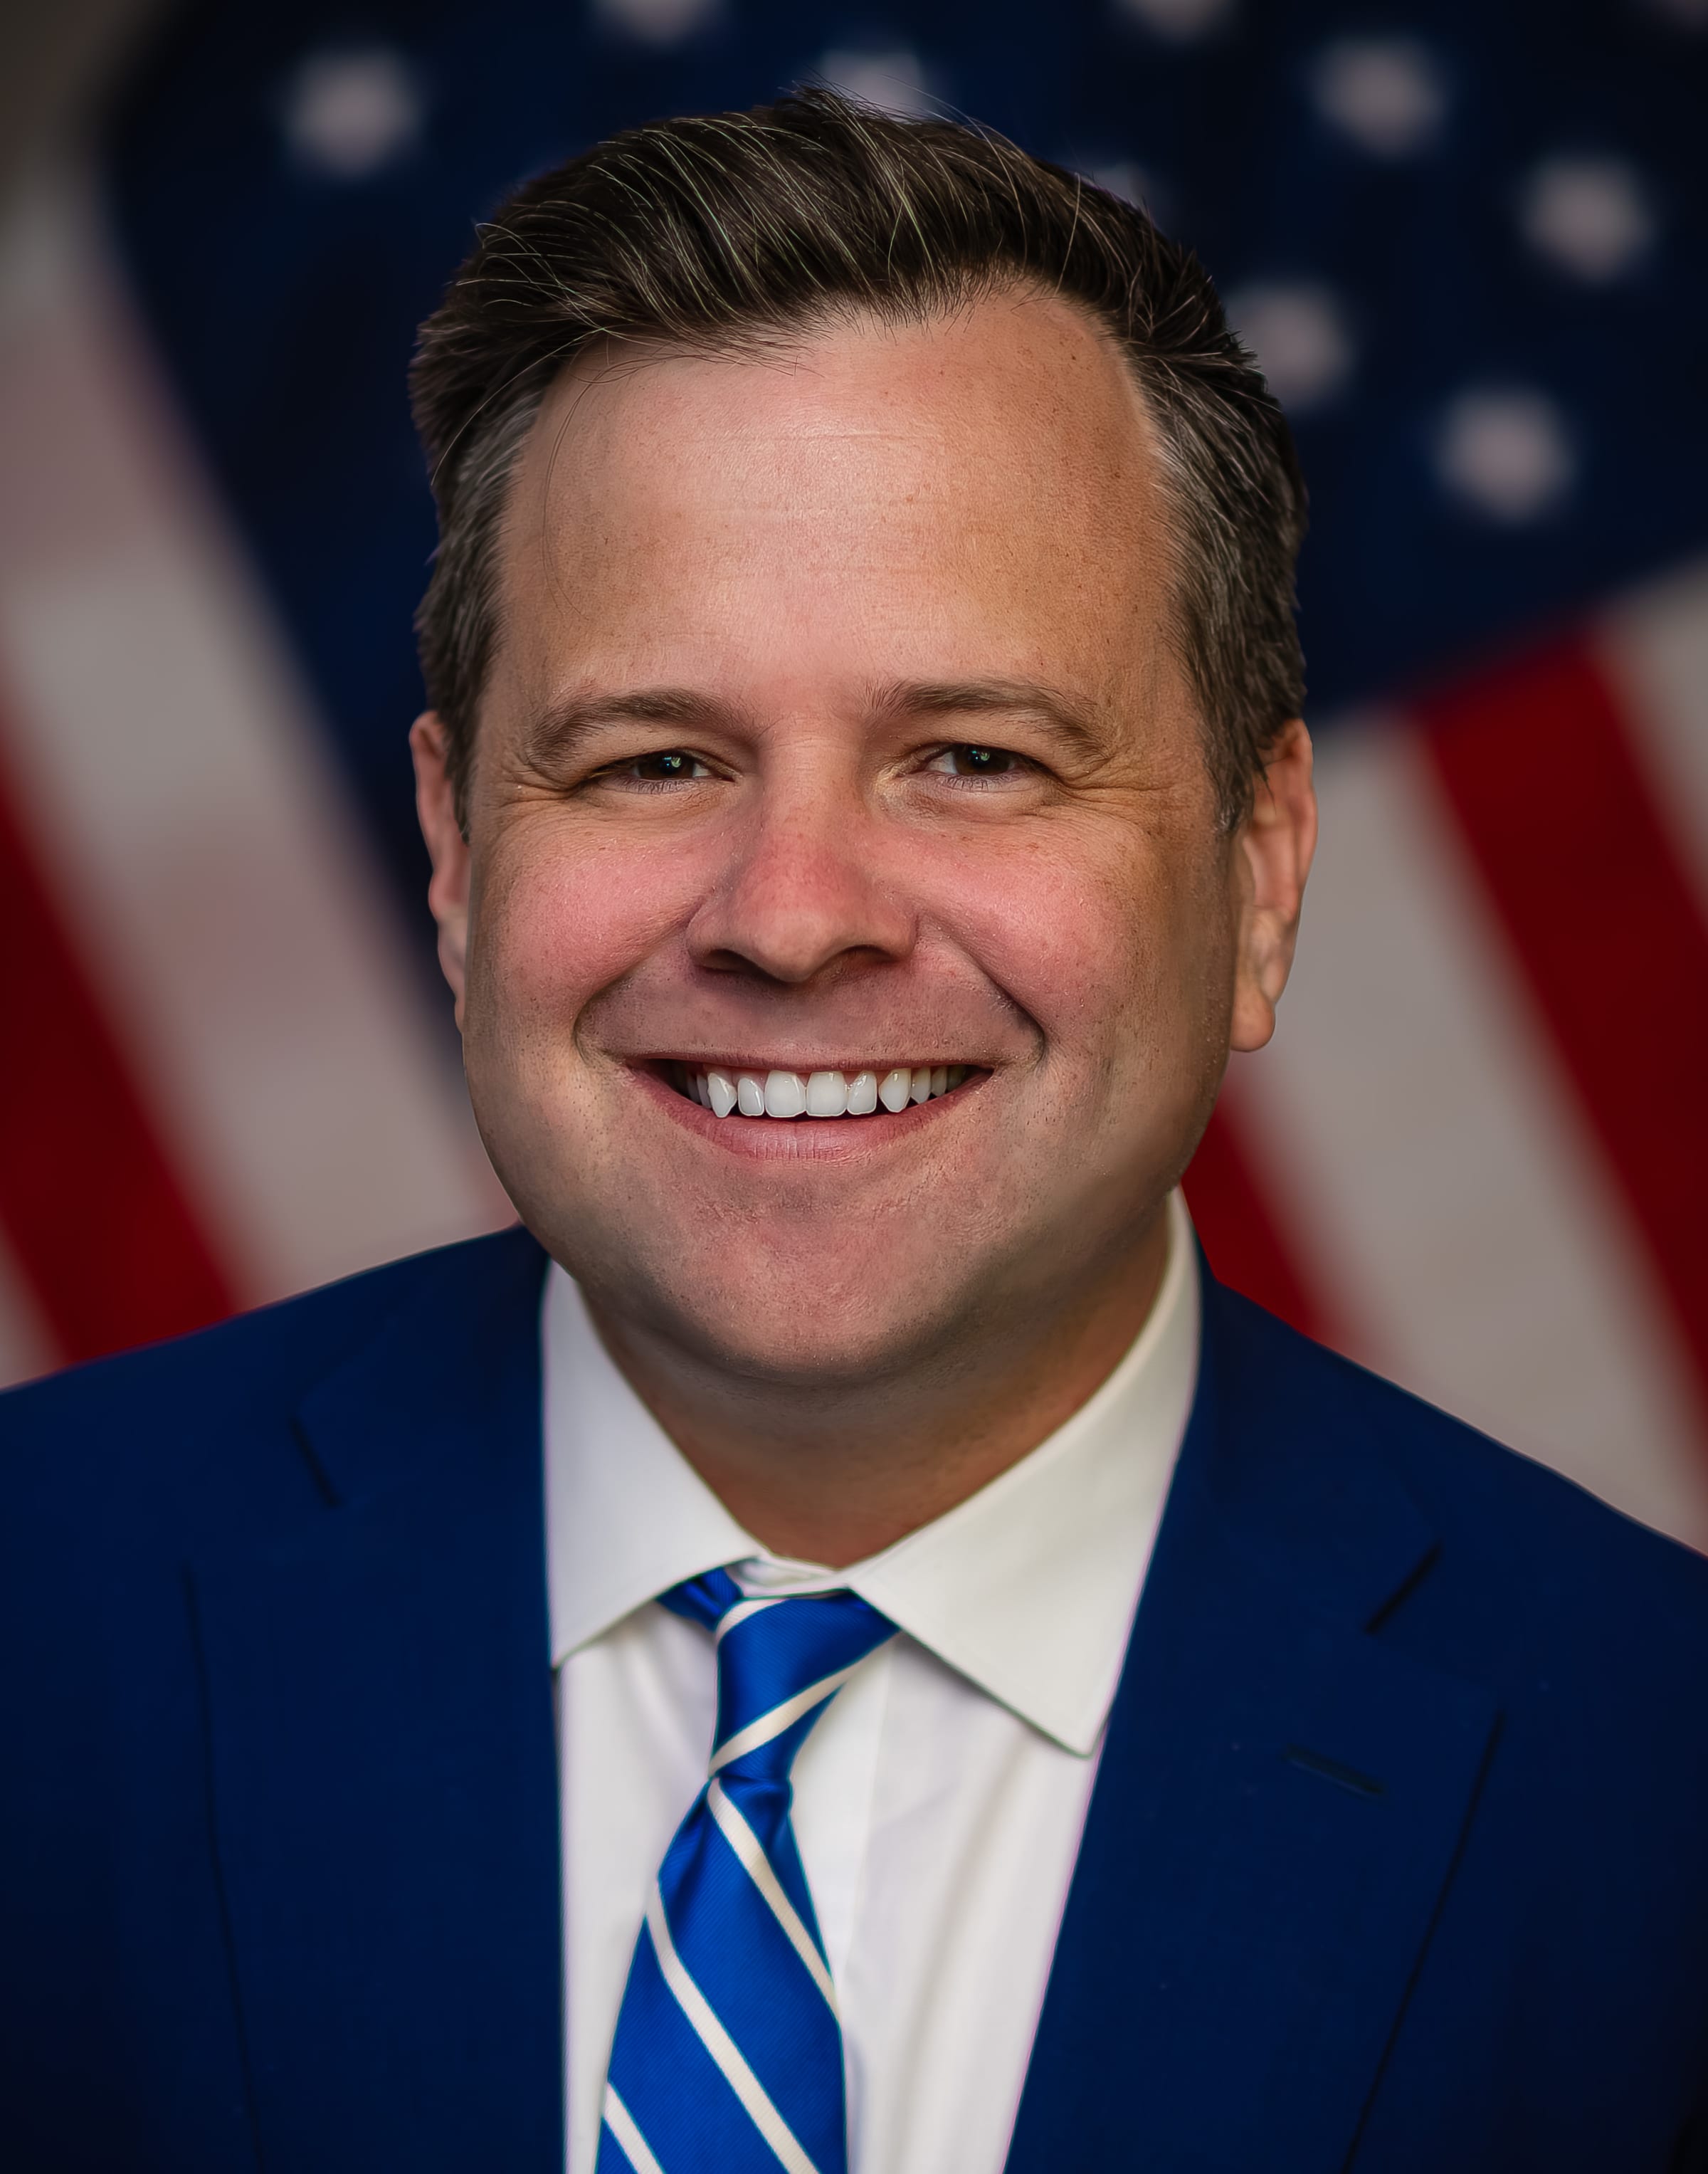
Monday evening, FHFA director Bill Pulte posted on X that Fannie Mae and Freddie Mac will merge their two pricing matrices into one grid carrying VantageScore alongside FICO Classic 1. That grid sets the loan-level price adjustments, the risk fees behind a conventional mortgage's rate, and Classic FICO stood alone on it 1. FICO fell 8% after hours 1 and 18% in Tuesday premarket trade 2.
No start date came with the announcement 1. Pulte called the old two-grid structure one that "makes zero sense" and said lender and consumer feedback drove the change 1. Seeking Alpha pinned Tuesday's premarket slide on TransUnion's price lock rather than the grid alone 4.
Under a month unwound thirty-one years
Since 1995 no loan reached either enterprise without a FICO score 3. On 9 March the three bureaus that own VantageScore 4 cut its mortgage price to 99 cents, free alongside a FICO purchase 3. On 3 September Pulte ordered both enterprises to approve every lender for the rival score, citing a 1,800% FICO price rise since 2020 5. FICO closed 5 September at $932.26, down 16.7% in a day 3.
That crash was chapter one, mapped in our 28 September piece "Why FICO fell 17% in a day and kept falling". Tuesday brought chapter two on three fronts.
TransUnion froze the 99-cent price through December 2028 6. Rocket Mortgage made VantageScore its preferred score on all eligible loans 2. FHA set 1 January 2027 for accepting VantageScore collateral 6.
The moat was the grid, not the math
What ended Monday was not a scoring contest but a routing rule. That rule let FICO lift its mortgage score from $4.95 in 2025 to $10 in 2026 3. By the June quarter, mortgage originations were 71% of business-to-business Scores revenue, up from 53% a year earlier, and that line grew 97% 3. Operating margin reached 58.2% in the March quarter, from the mid-40s through 2025 7. The moat was never the math; it was the grid.
Fair Isaac's operating margin stepped up as the toll doubled
Data
| Operating margin | |
|---|---|
| Q3 '24 | 43.4% |
| Q4 '24 | 40.8% |
| Q1 '25 | 49.3% |
| Q2 '25 | 48.9% |
| Q3 '25 | 46% |
| Q4 '25 | 45.7% |
| Q1 '26 | 58.2% |
| Q2 '26 | 53.8% |
Hold the toll or defend the volume
FICO's published prices already span both exits. Direct licence: $10 a score, or $4.95 plus $33 per closing. Score 10T: 99 cents, with $65 on funded loans 3.
FICO's 2026 menu already runs from 99 cents to $10 a pull
- Estimate
Data
| Value | |
|---|---|
| FICO 2020 (implied) (estimate) | $0.5 |
| FICO 2025 | $4.95 |
| FICO 2026, per pull | $10 |
| FICO 2026, licence | $4.95 |
| FICO Score 10T | $0.99 |
| VantageScore 4.0 | $0.99 |
The company backs competition "based on performance" and calls 10T its most predictive score 5. Holding the $10 toll cedes volume to a price fixed through 2028 6; cutting defends share, and a 58% margin is what the market reprices 7. Deutsche Bank's floor case has Rocket, 5 to 6% of originations, pulling no FICO score at all when eligible 2.
November carries the first honest number
The decider is mortgage-originations revenue inside Scores, and its next scheduled reading is FICO's November earnings call 3. How much volume moves, and whether $10 survives, no source can yet say. Until the grid gets a date, the repricing keeps running.
How this brief was made
01Gathered & sourced412 channels · 1,331 articles▾
Agents swept 412 channels and ingested 1,331 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated7 claims · 17 data feeds▾
Every one of 7 load-bearing claims was checked against primary sources, with 17 live data feeds reconciling the figures and charts.
- 1Yahoo Finance / Investing.com, 'FICO stock tumbles as US moves to break mortgage scoring monopoly', 28 September 2026
- 2MarketWatch, Steve Goldstein, 'Fair Isaac stock tumbles on FHFA director comment, Rocket Mortgage statement', 29 September 2026
- 3Forbes, Zennon Kapron, 'FICO Lost 17% In A Day Because Mortgages Finally Have A Second Credit Score', 11 September 2026
- 4Seeking Alpha via MSN, 'FICO stock slides after TransUnion extends 99-cent pricing for VantageScore 4.0', 29 September 2026
- 5Benzinga via Yahoo Finance, 'FICO Stock Falls Pre-Market After Bill Pulte Declares No More to FICO's Mortgage Scoring Monopoly (UPDATED)', 7 September 2026
- 6TransUnion press release via GlobeNewswire / Yahoo Finance, 'TransUnion Extends 99-Cent Mortgage Pricing for VantageScore 4.0 Through the End of 2028', 29 September 2026
- 7Sharadar quarterly fundamentals, from Fair Isaac (FICO)'s SEC filings, retrieved 29 September 2026
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.