Foxconn's most profitable quarter ever was paid for by its own cost cuts
AI racks passed half of Hon Hai's revenue for the first time and operating profit set an all-time quarterly record, but gross margin has fallen for three straight years and every point of the operating-margin gain came from spreading cost, not price. The 2027 ceiling is a TSMC packaging line Hon Hai does not own.
 Vincent Jiang · 3 min read
A guided beat on a record August
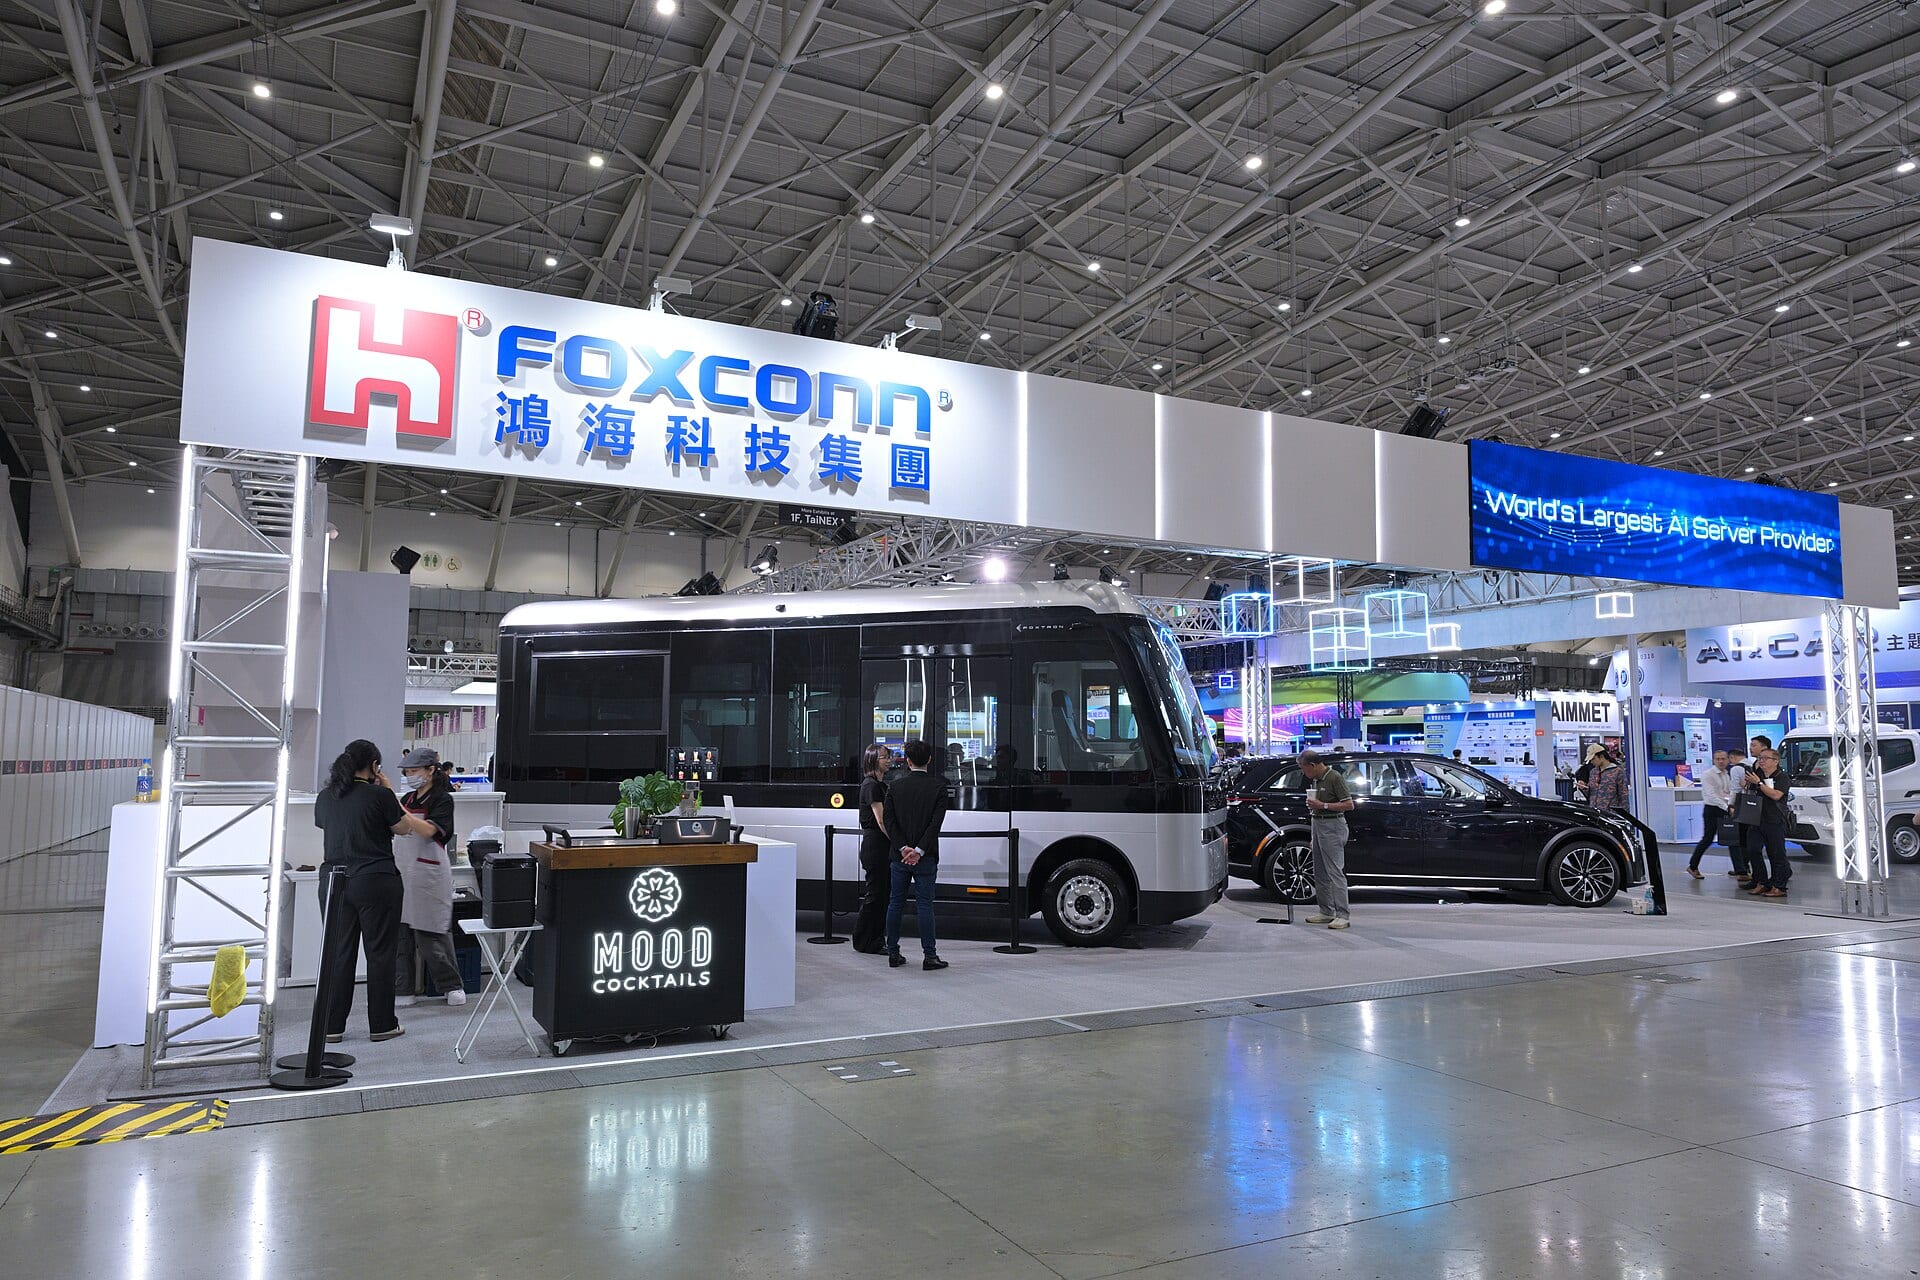
Foxconn says its third quarter will outperform market expectations 1. August revenue was NT$921.8 billion, up 52% year on year, the best August ever, after July set the all-time monthly record 12.
The June quarter underneath is the one the market calls a mix-shift win: revenue up 41% to NT$2.53 trillion, net profit up 35% to NT$59.97 billion, ahead of the NT$58.22 billion analysts expected 345. Cloud and networking, the AI rack division, passed half of revenue for the first time at 51%; the iPhone side slipped to 29% 36.
The margin that fell, the margin that rose
The cut Hon Hai keeps on what it builds keeps shrinking. Gross margin was 6.12% against 6.33% a year earlier, and the annual series has stepped down from 6.30% in 2023 to 6.25% in 2024 to 6.15% in 2025 38. Operating margin ran the other way, to 3.75%, its highest in about nine and a half years, on an all-time record NT$94.8 billion of operating profit; net margin still fell, to 2.37% 378.
Gross margin has fallen three straight years while operating margin climbed every period
- Gross margin
- Operating margin
Data
| Gross margin | Operating margin | |
|---|---|---|
| FY2023 | 6.3% | 2.7% |
| FY2024 | 6.25% | 2.92% |
| FY2025 | 6.15% | 3.2% |
| Q1 2026 | 6.18% | 3.57% |
| Q2 2026 | 6.12% | 3.75% |
The gain came off the cost line
Hon Hai does not publish its operating-expense ratio, but it is the gap between the two margins it does publish: 3.17% of revenue a year ago, 2.37% now 8. The year-on-year arithmetic closes one way: minus 0.21 points from the product, plus 0.80 points from spreading cost over more revenue, plus 0.60 points at the operating line 8.
Gross profit grew 36% while revenue grew 41% 8. Management said it first in March 2025: the chief financial officer blamed selling more servers 8. Nvidia holds about 60% of TSMC's CoWoS output, pre-committed mostly through 2027; five North American hyperscalers account for nearly 90% of 2026 AI server spend 57. The boom pays Hon Hai by the rack, and the rack's price is set elsewhere.
The operating-margin gain came entirely off the cost line
Data
| Value | |
|---|---|
| Product (gross margin) | -0.21 pts |
| Cost line (expense ratio) | 0.8 pts |
| Result (operating margin) | 0.6 pts |
The bulls have receipts
A Japanese brokerage lifted its 2026 to 2028 forecasts by 12.8%, 23.4% and 24.9% and its target from NT$352 to NT$435 8. A published bull model sees a 3.7% operating margin on NT$11 trillion of revenue this year 9. Chairman Liu Young-way promises rack capacity doubling to 2,000 a week by end-2026 8.
The upgrades grow the further out the forecast runs
- Estimate
Data
| Value | |
|---|---|
| 2026 (estimate) | 12.8% |
| 2027 (estimate) | 23.4% |
| 2028 (estimate) | 24.9% |
The ceiling Hon Hai cannot build
None of that buys CoWoS, TSMC's packaging step between a finished GPU die and a rack that can ship. Rotating chief executive Michael Chiang named chip supply, not demand, as the 2027 constraint: volumes "will depend on chip supply" 67. TSMC targets 125,000 to 130,000 wafers a month by end-2026, its chief executive calls the line sold out through 2026, and trade reporting had it still short in September 710. Morgan Stanley, an estimate, has Hon Hai's high-end rack share slipping from 51% to 39% this year as buyers add assemblers 68.
Two dates, one pair of numbers
Monthly revenue lands on 5 October 2026; the third-quarter results follow on a date still unannounced as of 25 September 8. Watch one pair: gross margin and operating margin. Gross turning up while operating keeps climbing would mean the mix shift finally charges for something. A fourth year of divergence means the model is volume, funded by a cost line shrinking toward zero.
How this brief was made
01Gathered & sourced278 channels · 1,494 articles▾
Agents swept 278 channels and ingested 1,494 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated10 claims · 28 data feeds▾
Every one of 10 load-bearing claims was checked against primary sources, with 28 live data feeds reconciling the figures and charts.
- 1Reuters via U.S. News & World Report, 'Foxconn Says Third Quarter to Outperform Market Expectations on AI Strength', 5 September 2026
- 2Crypto Briefing, 'Foxconn reports $29B revenue in August, up 52% year over year', 5 September 2026
- 3Times of Oman (ANI, citing Focus Taiwan), 'Foxconn posts record $1.86bn profit in Apr-June quarter', 13 August 2026
- 4Convergencia Latina, 'Foxconn's profit rises 35% on AI demand', September 2026
- 5TechRepublic, 'Foxconn AI Server Demand Drives 35% Profit Jump', 13 August 2026
- 6The Next Web, 'Foxconn now makes more money from AI servers than from everything else combined', 12 August 2026
- 7Tech Times via MSN, 'Foxconn CEO names CoWoS packaging as 2027 AI server ceiling after record Q2 earnings', 12 August 2026
- 8The Capital Atlas, Issue 13, 'Foxconn: the margin that fell and the margin that rose', 26 September 2026
- 9Seeking Alpha, 'Hon Hai Precision: Complex Server Manufacturing Is Becoming A Better Business', 18 September 2026
- 10DIGITIMES, 'TSMC 3nm, 2nm, and CoWoS stay tight as AWS, MediaTek, TPU shift capacity', 15 September 2026 (lede; article behind subscription)
03Reviewed & edited1 human editor▾
One editor read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.