GE Vernova Is Buying Equity In Its Own Order Book
A 1 October disclosure shows GE Vernova putting PLN 436 million into Synthos Green Energy, the developer of its own BWRX-300 reactor, three days after the first US construction permit and four weeks before a Q3 print that tests who pays for the $176 billion backlog.
 Vincent Jiang · 3 min read
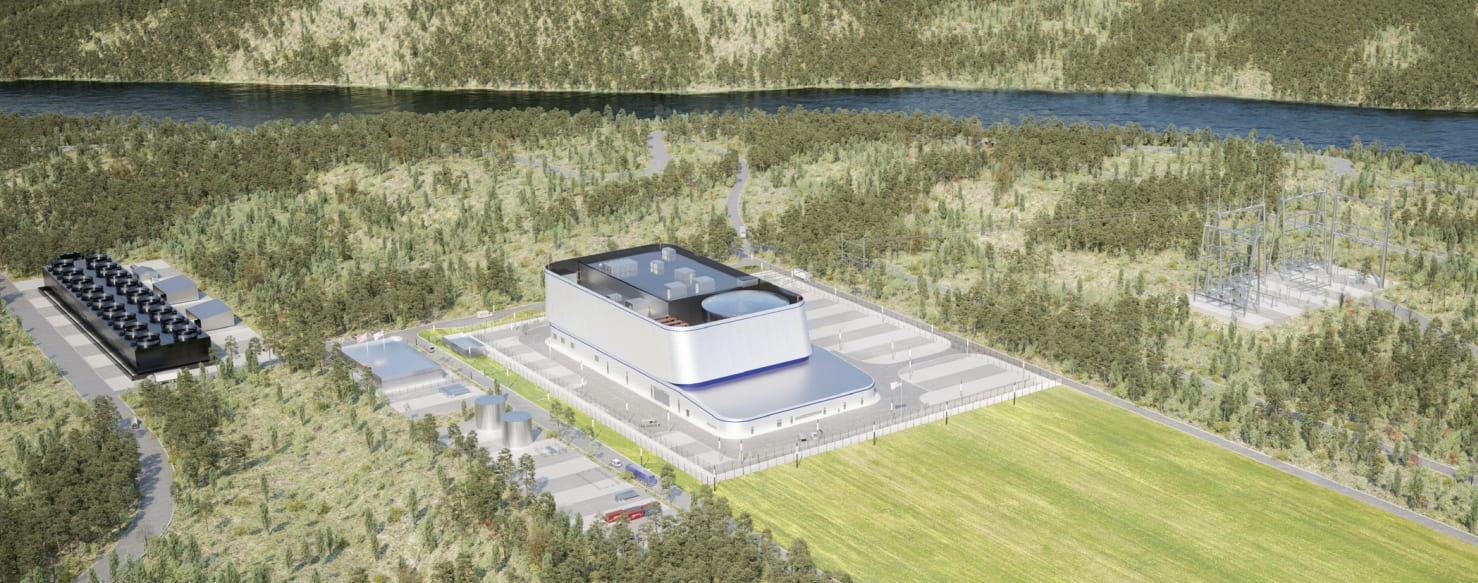
A regulatory disclosure dated 1 October 2026 carries one line nobody in the nuclear rally wrote up: Synthos Green Energy's funding round names GE Vernova Inc. as an investor of PLN 436,236,700, about €100 million, into the Warsaw developer of the same BWRX-300 reactor GE Vernova sells 1.
The equipment vendor just bought equity in its own demand.
The round is bigger than GEV's check. SGE is raising PLN 3,489,893,600, roughly €800 million, in convertible preferred shares, closing by year end 1. Ten Polish entrepreneurs, among them InPost's Rafał Brzoska and ElevenLabs' co-founders, are in for PLN 500 million, and SGE holds PLN 1.35 billion in foreign equity commitments 15. Days earlier, GE Vernova Ventures moved to upsize its fund to $250 million to back energy and data-center companies 2. Two checks, one direction: toward the buyers.
The permit earned nothing, the cap table might
On 29 September the NRC issued the first US construction permit for a BWRX-300, at TVA's Clinch River site, completing its technical evaluation four months early 47. Qualified hope, not revenue: the permit authorizes construction only, a separate operating license is required before any power flows, and no start date or project cost is disclosed 7. TVA is negotiating cost-sharing so ratepayers do not carry first-of-a-kind risk 9.
SGE, meanwhile, has a decision in principle for 26 reactors in Poland and a 14-unit, 4.2 GW UK proposal, and operates not a single power plant 5610.
That contrast is the point. GE Vernova's September 23 European MOU with Hitachi and Samsung C&T makes SGE the developer stitching together the fleet GEV wants to sell 611. With its own customers thin on the ground for capital, the vendor is now seeding them.
The receipts show whose cash fills the backlog
GEV's Q2 numbers say the order book is real but runs on other people's money 3. Orders hit $24.2 billion, up 88 percent organically, against a $176 billion backlog, and 2026 free cash flow guidance jumped to $11.5 to 12.5 billion from $6.5 to 7.5 billion explicitly because customers pay deposits to hold turbine slots, with gas backlog and slot reservations at 116 GW against a 125 GW year-end target 3.
Free cash flow jumped from under $1B a quarter to $5.1B once customers started paying deposits
Data
| GEV FCF | |
|---|---|
| Q3 '24 | 0.97B |
| Q4 '24 | 0.58B |
| Q1 '25 | 1.01B |
| Q2 '25 | 0.19B |
| Q3 '25 | 0.73B |
| Q4 '25 | 1.81B |
| Q1 '26 | 4.97B |
| Q2 '26 | 5.13B |
Q2 net income was $0.6 billion while free cash flow ran $5.1 billion, the widest gap in the company's short public life 38. The cash is a loan from the queue.
The gap between reported profit and cash collected opened wide in 2026
- Net income
- Free cash flow
Data
| Net income | Free cash flow | |
|---|---|---|
| Q3 '24 | -$0.1B | $0.97B |
| Q4 '24 | $0.48B | $0.58B |
| Q1 '25 | $0.25B | $1.01B |
| Q2 '25 | $0.51B | $0.19B |
| Q3 '25 | $0.45B | $0.73B |
| Q4 '25 | $3.66B | $1.81B |
| Q1 '26 | $4.75B | $4.97B |
| Q2 '26 | $0.67B | $5.13B |
The counterpoint: the customer is being built on purpose
The fair opposing read: deposits are paid only when customers want the turbines, and SGE's UK plan is privately financed by design, a Contract for Difference model with no state cheque, targeting fleet-mode costs of £2.2 to 2.5 billion per reactor and first power in 2034 10. SGE's founder called the entrepreneurs' PLN 500 million the strongest validation a project of this scale can get: capital committed, not support declared 5. GEV's equity de-risks the very orders its backlog depends on 11.
But the clock says otherwise. GEV trades at 65.6 times forward earnings on a $263 billion market cap 11, and its October 28 Q3 print now tests something new: not whether orders exist, but who finances them, in gas where deposits hold slots and in nuclear where they barely exist 3. Where deposits do not close the gap, GE Vernova is writing the cheque itself.
On that read, GEV holders now carry a venture-style convertible on a developer's cap table inside an industrial multiple.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.