Lumentum prepaid $87 million to lock AXT's chip capacity through 2031; insiders sold $78.8 million
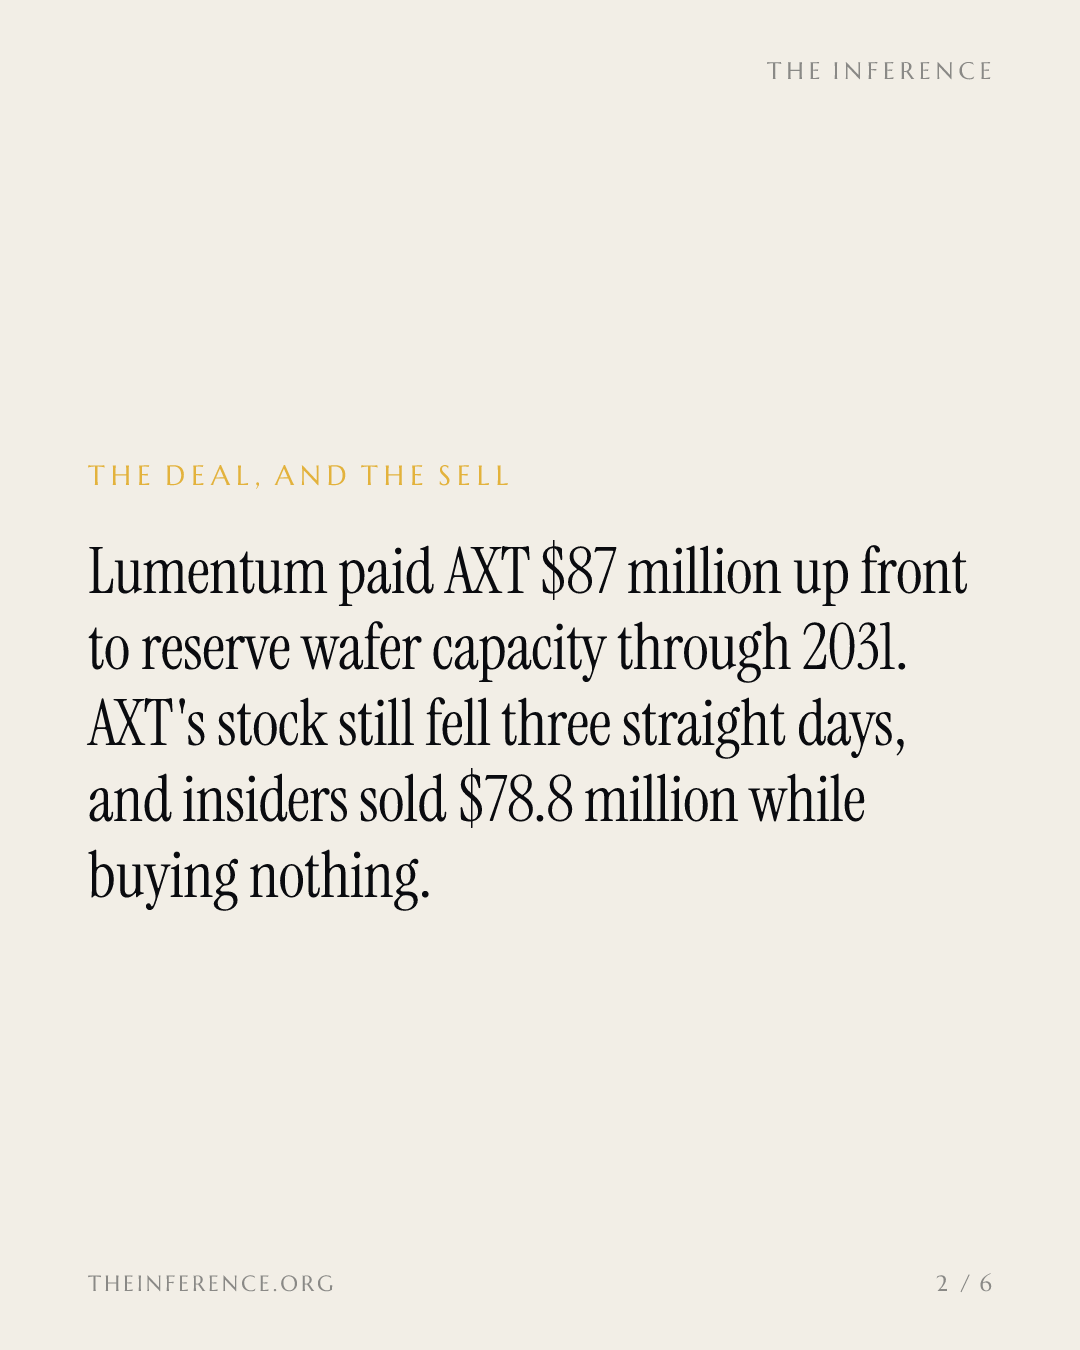
Lumentum prepaid $87 million to lock AXT's indium phosphide capacity through 2031, but the stock just fell three straight sessions while insiders sold $78.8 million and bought nothing. Wedbush's China demand thesis cuts both ways for a company whose wafers ship out of Beijing one export permit at a time.
 Vincent Jiang · 2 min read
AXT's run broke this week. The substrate maker's stock closed Thursday at $71.66, down $8.13, more than 10% on the day and lower for a third consecutive session 2. The timing matters: the slide gathered pace as Wedbush analyst Matt Bryson handed the bull case a fresh leg, arguing that China's push for optical components Western suppliers cannot fully provide could favor AXT 3.
The contract behind the run
The run rests on one signed deal. Lumentum+6.34% — Lumentum, up 6.34 percent today agreed to a binding, six-year reservation of AXT's indium phosphide wafer capacity through the end of 2031, putting down two deposits of $43.5 million each, $87 million in total, credited against future shipments 1. Because the deposits are prepaid and only clawed back as wafers ship, they point to AXT getting expansion capital in advance, and to an AI data-center customer willing to pay before the wafers exist 1.
Q2 2026 revenue doubled year over year to $47.6M as AI optics demand landed
Data
| Revenue | |
|---|---|
| Q1 '24 | $22.69M |
| Q2 '24 | $27.92M |
| Q3 '24 | $23.65M |
| Q4 '24 | $25.11M |
| Q1 '25 | $19.36M |
| Q2 '25 | $17.97M |
| Q3 '25 | $27.96M |
| Q4 '25 | $23.04M |
| Q1 '26 | $26.92M |
| Q2 '26 | $47.59M |
The buyer pays while insiders sell
The buyer pays; the people who know the company best are selling. Insiders bought nothing in the past twelve months while offloading roughly $78.8 million of stock 3. Four premium gurus still hold the shares, but three have been trimming 3.
The outside holders carry the valuation risk instead. AXT trades at 33.14 times sales against a historical median of about 2.2x, with a market value of $5.23 billion, while remaining unprofitable and cash-flow negative 3. GuruFocus scores the company 59 out of 100 overall: financial strength 8 of 10, valuation 1 of 10 3.
GuruFocus scores AXTI's valuation 1 out of 10 while insiders sold $78.8 million
Data
| Value | |
|---|---|
| Financial strength | 8/10 |
| Profitability | 5/10 |
| Growth | 5/10 |
| Momentum | 3/10 |
| Valuation | 1/10 |
Two buyers, one Beijing fab
Wedbush's China thesis cuts both ways, and nobody has connected it to the unwind. China is AXT's largest revenue source, the company operates primarily through Chinese subsidiaries, and its Asia headquarters and manufacturing sit in Beijing 3 4. On that reading, the domestic optics demand Bryson flags competes with Lumentum for the same output, and the Chinese buyer needs no export permit while Lumentum's wafers ship one approval at a time. That is the inference, not a sourced fact; the two claims have not been shown to pull on the same wafers.
The October 29 print, due after the close 4, settles which reading holds. Watch the revenue split by geography: a rising China share alongside flat Western shipments would confirm the two-buyer fight for Beijing output. Guidance that locks Lumentum's reserved capacity into 2027 shipments would hand the bull case its proof instead.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.