Microchip named no customer for its new AI power board, and the stock trades at 116 times earnings
Microchip and Navitas announced an 800V DC-to-6V rack-power reference design on October 5 and named no customer for it. The stock trades at 116.6x trailing earnings against a 27.2x five-year median; the report expected around October 29 decides whether that premium is earned.
 Vincent Jiang · 3 min read
An 800-volt board with nobody to bill
Microchip's−2.97% — Microchip, down 2.97 percent today newest AI product is a circuit board, and the announcement names nobody who will buy it.
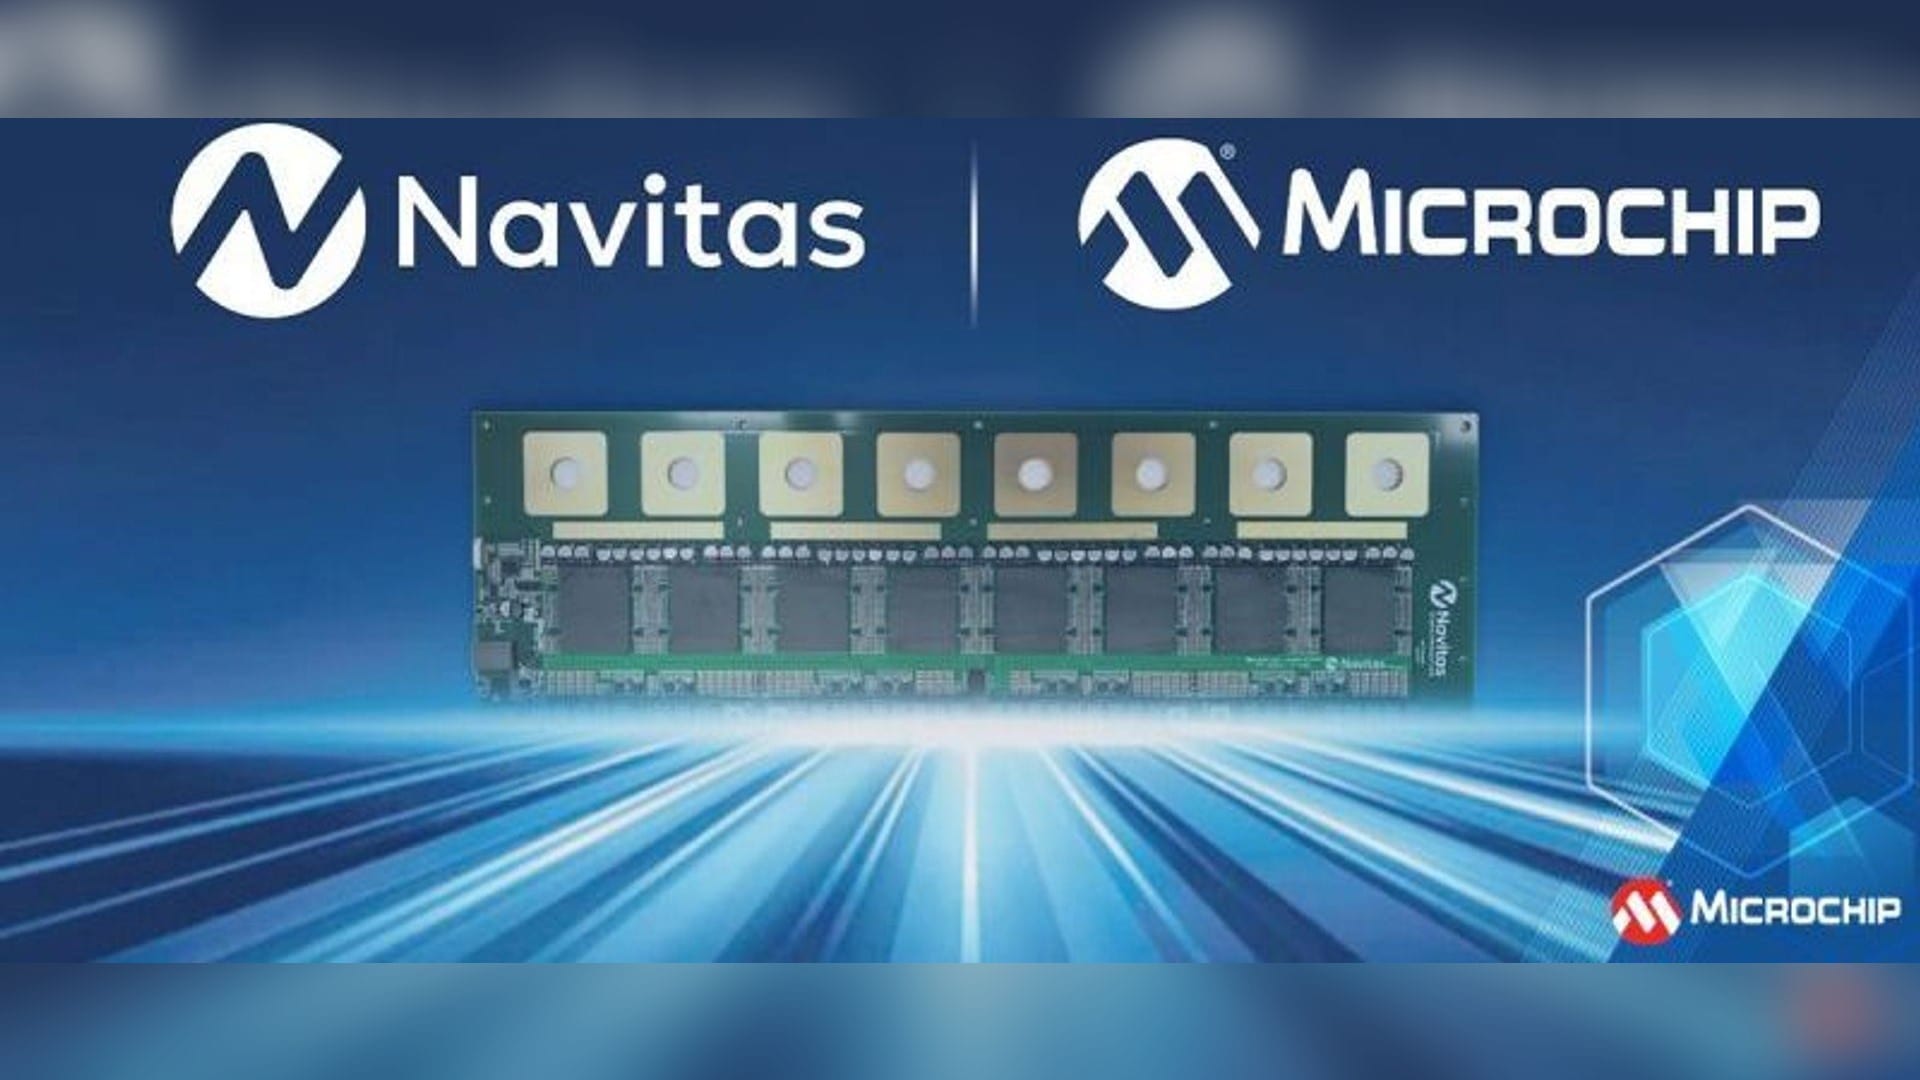
The October 5 release with Navitas−2.74% — Navitas, down 2.74 percent today describes an 800V DC-to-6V reference design for AI rack power: Microchip's dsPIC33AK digital controllers and TA100 security chip driving 16 Navitas GaN FETs, targeting up to 96% peak efficiency and 2,100 watts per cubic inch, aligned with the Open Compute Project's 800V DC standard 1.
The 20-kilowatt board reaches the OCP show floor in San Jose on October 12–15 12. What ships is a reference board, software and documentation: no customer, no socket, no revenue figure 1.
The AI line is one-sixth of the company
Data center work was 17.1% of June-quarter sales, about $1 billion annualized for 2026 on the company's own telling, inside $1.485 billion of revenue, up 38% year on year 3. CEO Steve Sanghi's clock runs later: PCIe Gen6 design wins bring "significant growth from data centers in 2027 and thereafter" 3.
The 38% is also a climb out of a hole, and revenue still sits about a third below its 2023 peak 4.
Five quarters of recovery, and revenue is still a third below its 2023 peak
Data
| Quarterly revenue | |
|---|---|
| Q3 '23 | $2.25B |
| Q4 '23 | $1.77B |
| Q1 '24 | $1.33B |
| Q2 '24 | $1.24B |
| Q3 '24 | $1.16B |
| Q4 '24 | $1.03B |
| Q1 '25 | $0.97B |
| Q2 '25 | $1.08B |
| Q3 '25 | $1.14B |
| Q4 '25 | $1.19B |
| Q1 '26 | $1.31B |
| Q2 '26 | $1.49B |
The margin guide has scaffolding in it
The September-quarter guide of 66–67% non-GAAP gross margin rests, as the bear camp quoted by Simply Wall St tells it, on a quarter of unusually strong 100%-margin licensing revenue and a one-time distributor inventory write-up, while foundry and assembly costs rise 5. The company's own disclosure covers part of that ground: June's 63.8% non-GAAP gross margin was helped by a strong licensing quarter, and CFO Eric Bjornholt called some of that help non-recurring 3.
GuruFocus counts $71.1 million of insider selling over 12 months with zero purchases, and its value line sits at $67.29 against a $78.02 price 6. Twelve-month free cash flow of about $1.07 billion anchors the Simply Wall St discounted-cash-flow model, whose value sits modestly below the $81.26 quote it used 5.
What the buyers are paying for
The recovery itself is real. Adjusted EPS nearly tripled from $0.27 a year ago to $0.76 7, and September-quarter guidance of $1.60 billion at the midpoint beat the $1.55 billion consensus 3. The forward P/E is 21.5x, not the 116.6x trailing print against a 27.2x five-year median 6.
The trailing print is more than four times the five-year median
Data
| Value | |
|---|---|
| Trailing P/E | 116.6 |
| Five-year median | 27.2 |
| Forward P/E | 21.5 |
Weiss reads the October 7 drop, 4.68% to $77.46 and roughly double the chip index's fall on a 5.35% 10-year Treasury yield, as macro risk-off rather than a Microchip event 7. Navitas is buying the whole power chain: the Claros close on October 6, a $232.8 million deal, is expected to more than double its 2030 market above $8 billion 8.
The referee works October 29
The report expected around October 29 carries consensus near $0.93 adjusted EPS on $1.61 billion of revenue, inside the $0.91–0.95 guide 7. The line to read is gross margin without the licensing quarter, with data center's share of sales as the second tell.
Until that print, whoever buys the AI premium before a data-center revenue line of scale exists is the one paying for it; holders benefit only if October 29 shows the 66–67% guide is organic. San Jose puts the board on display on October 12. The margin line speaks on October 29.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.