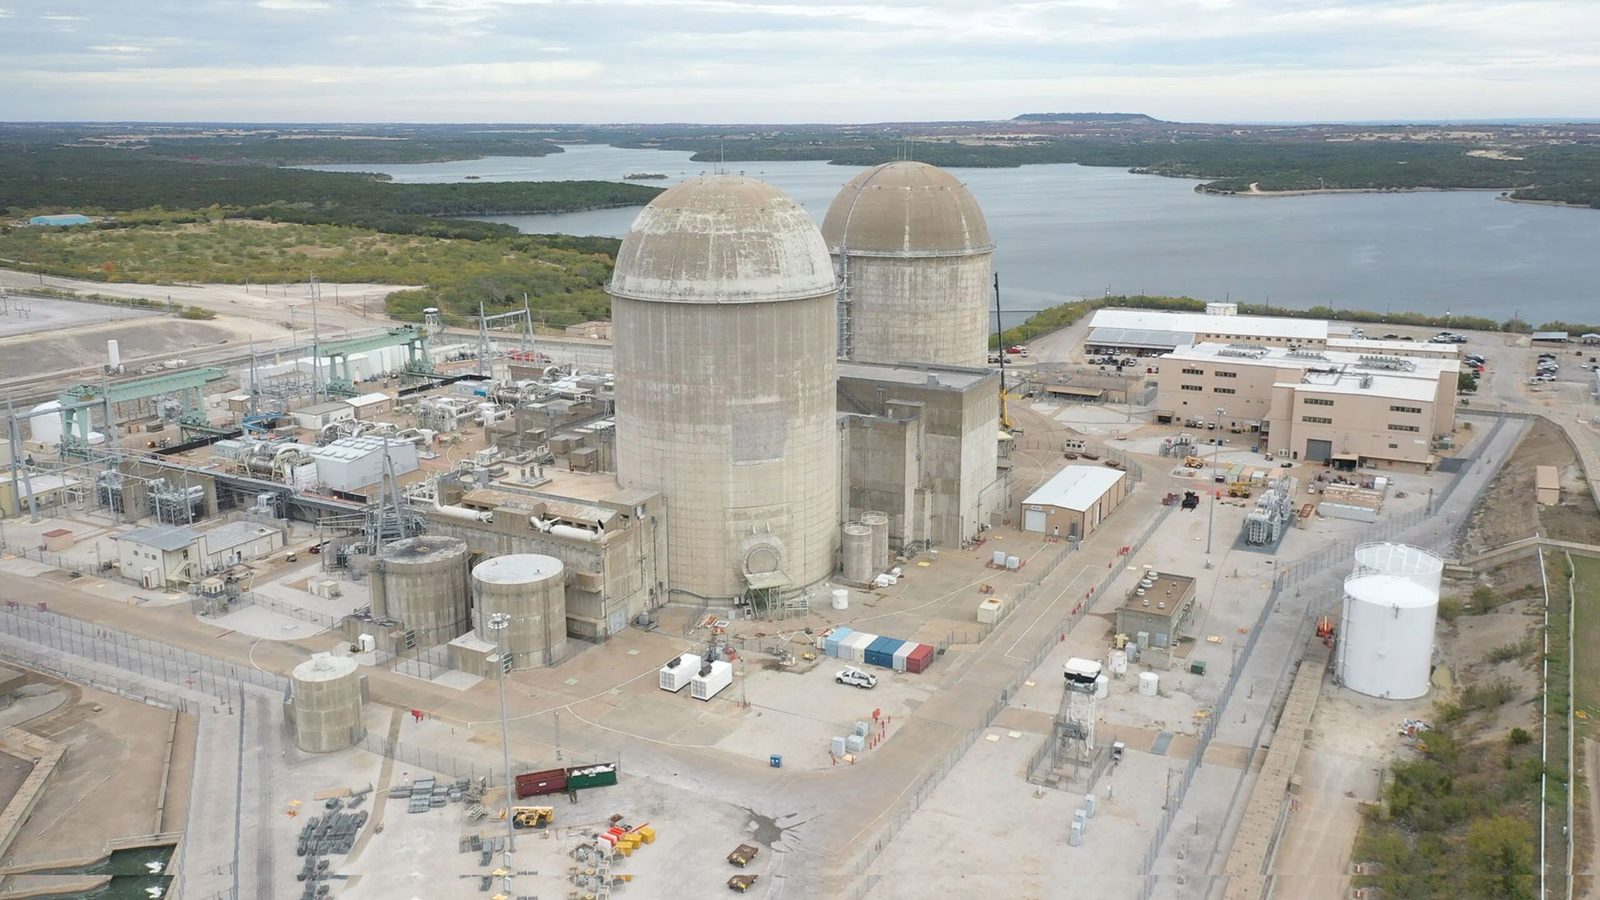
Modine Can Leave Auto Parts. It Still Has to Earn Its AI Valuation.
Data-center sales nearly doubled as MOD prepares to separate its vehicle business. Shrinking margins and customer-funded cash flow reveal what the new company must prove.
 Vincent JiangSeptember 15, 2026 · 6 min read
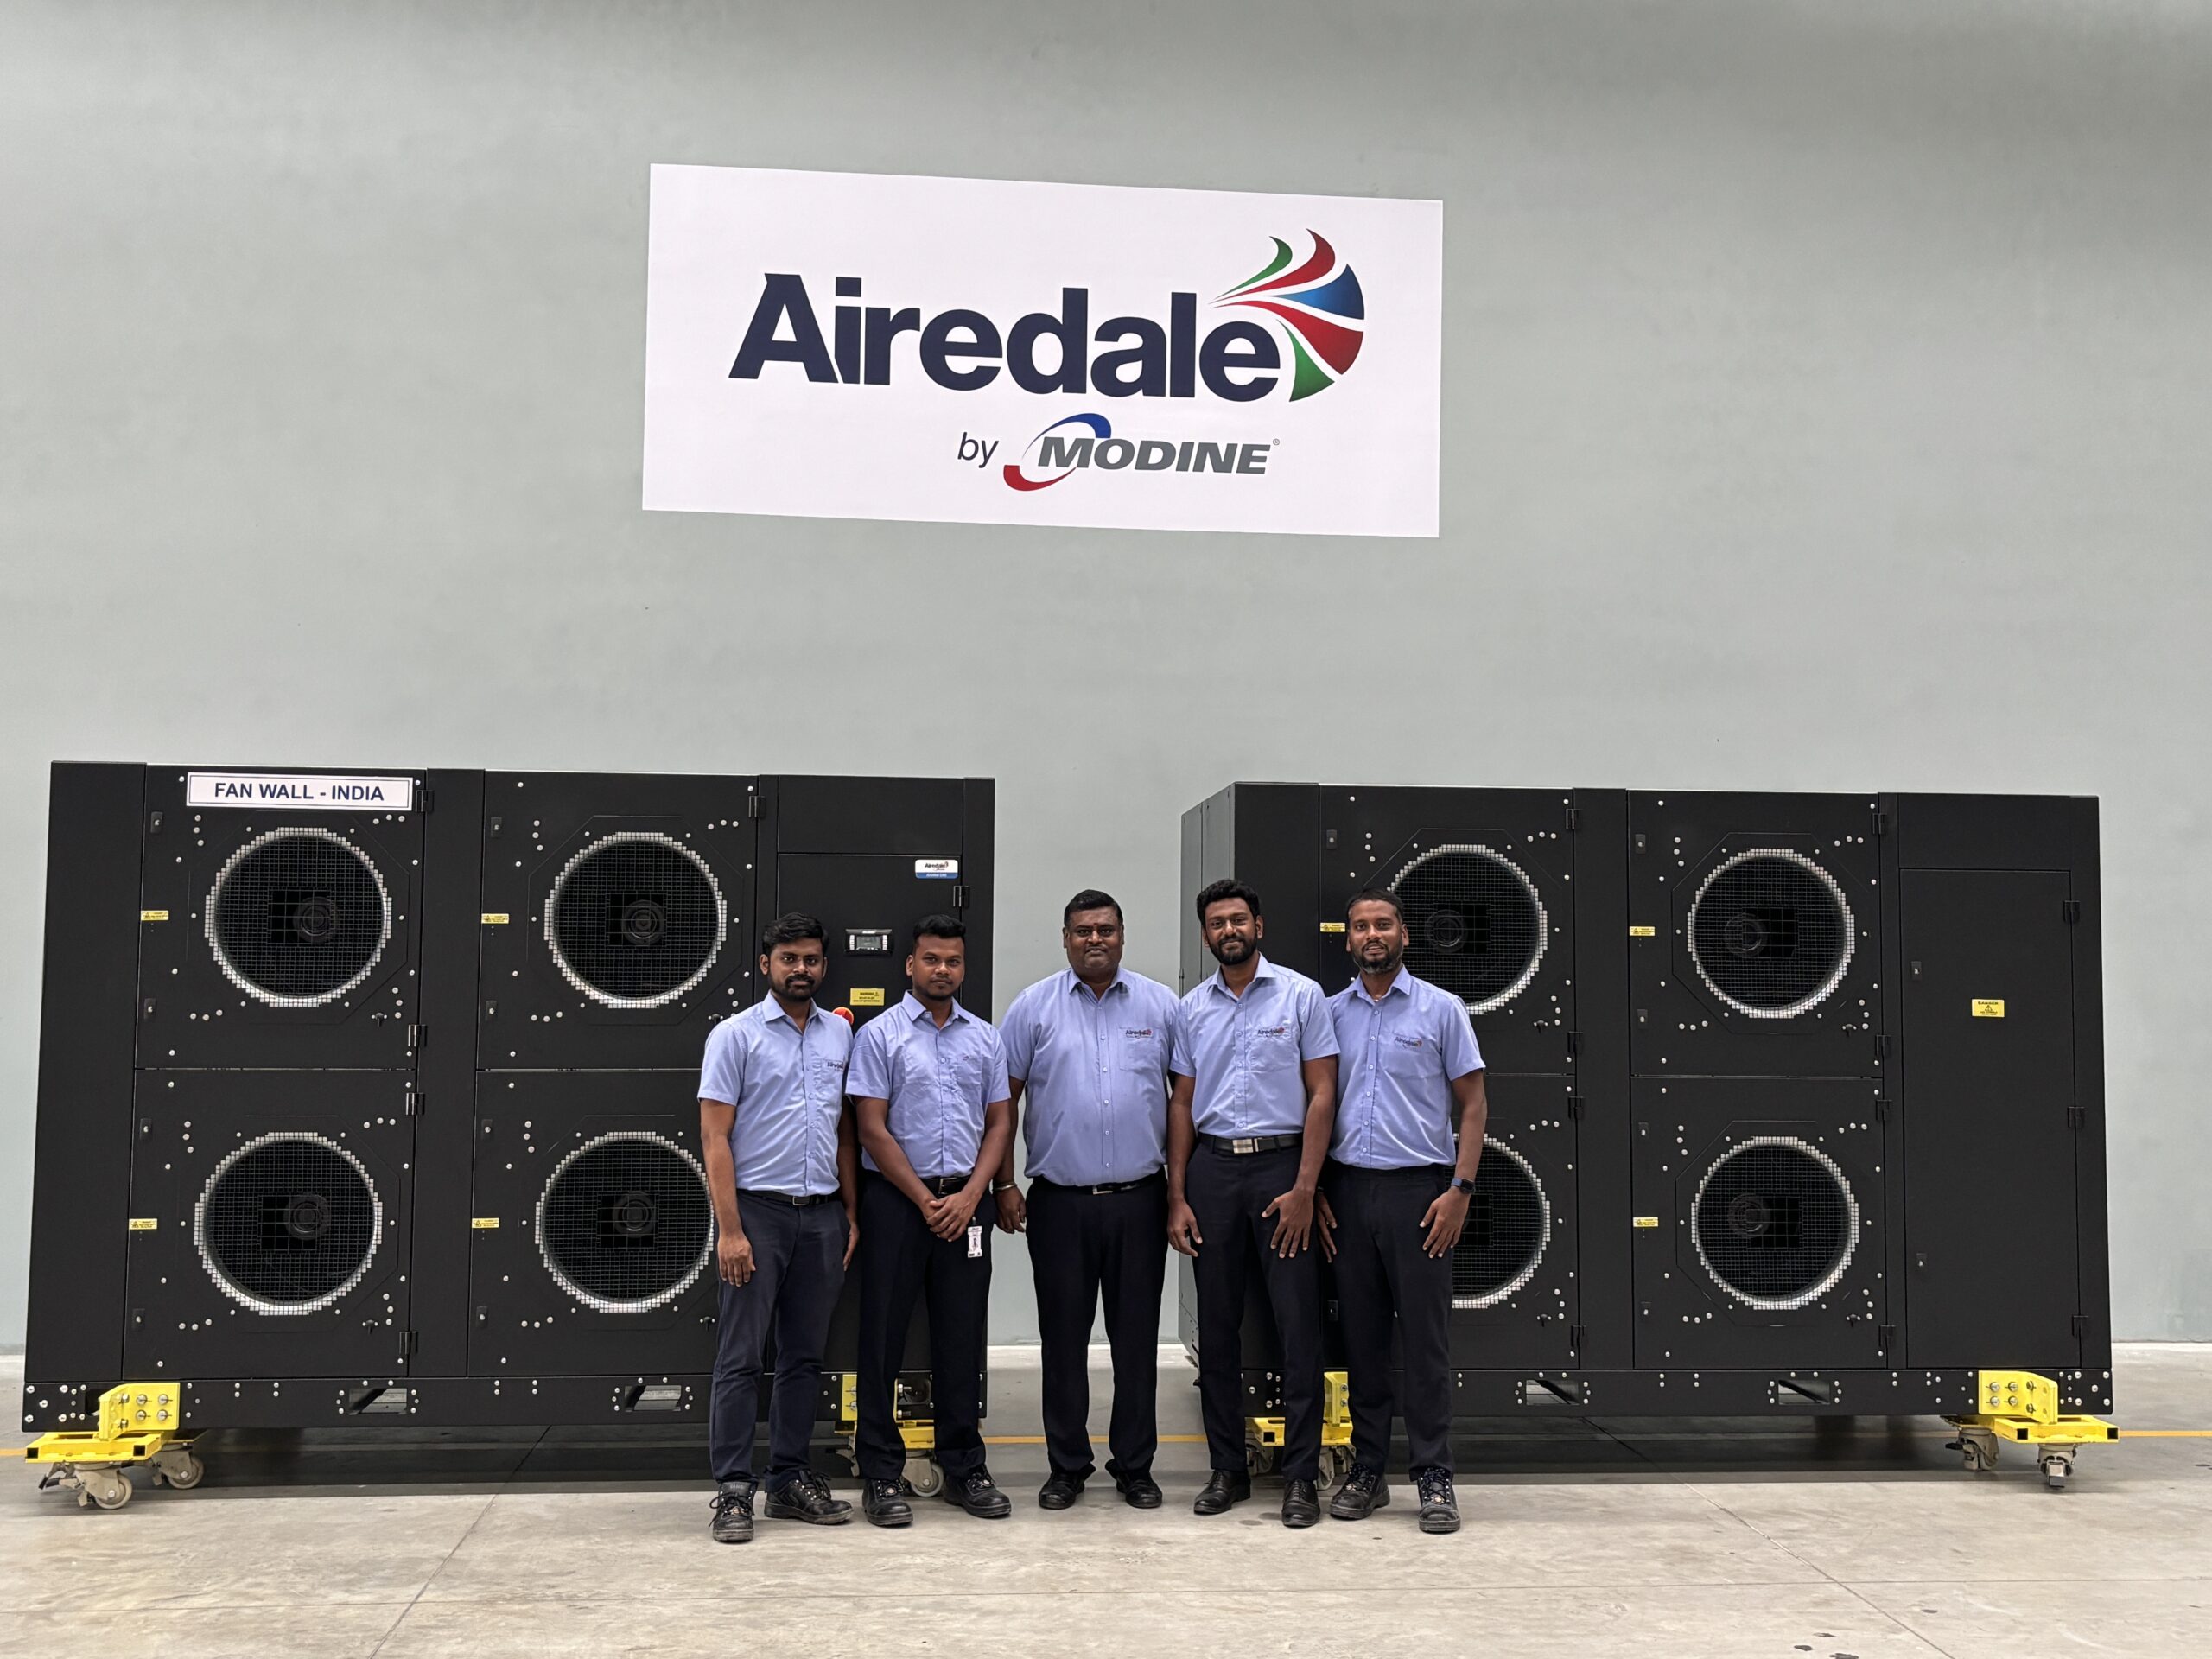
The auto-parts label is about to expire
Neil Brinker is preparing to change the name of the company he runs. On September 10, Modine announced plans to become Modexus Solutions after separating its Performance Technologies business. The proposed name requires a separate shareholder vote; the MOD ticker stays.1
The business separation is closer. Gentherm shareholders approved the combination that day, with closing now expected October 1, subject to remaining conditions.2 The company still classified as an auto-and-truck-parts supplier is moving toward data-center cooling and commercial heating, ventilation and refrigeration.
That deserves a different investment framework. It does not automatically deserve a higher valuation. Brinker has found customers who urgently need more equipment. The unresolved question is how much money Modine keeps after building and delivering it.
More heat does not guarantee more pricing power
The shift has substance. In April, Modine established a dedicated Data Centers segment, separating it from Climate Solutions.3 Investors can now examine the growth engine's performance directly instead of inferring it from a broader industrial business.
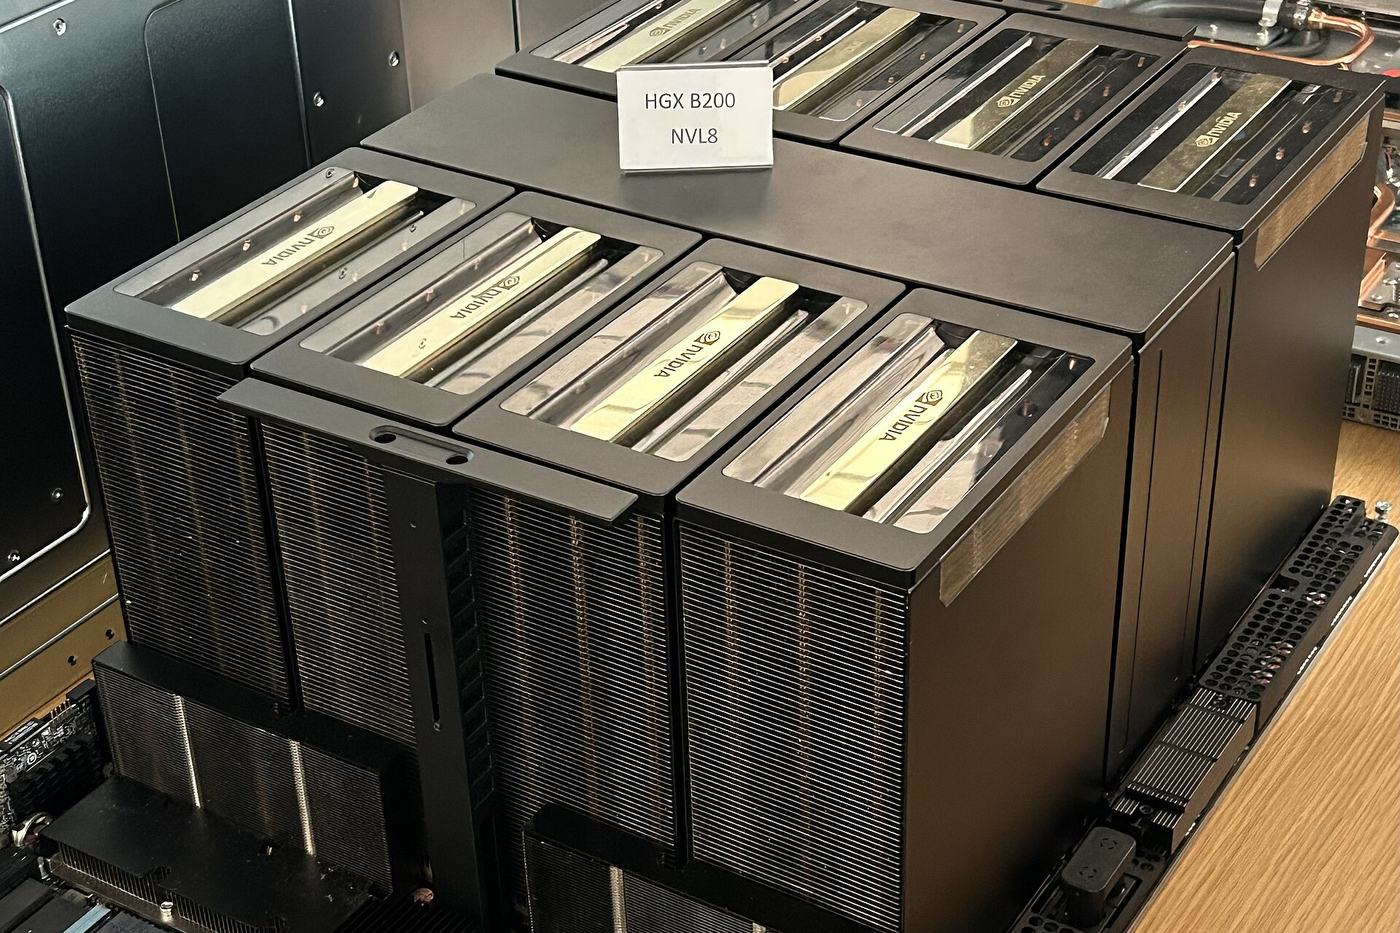
The product solves a physical problem. Computing generates heat; cooling equipment moves that heat away from chips and ultimately out of the building. Airedale, Modine's cooling brand, supplies equipment across that chain, including chillers, coolant distribution units, dry coolers and controls.4
For a customer, a delayed cooling system can delay a much larger computing investment. That makes delivery reliability valuable. It also explains why a buyer might help fund a supplier's factory before receiving the equipment.5
But the need to remove heat does not guarantee demand for every cooling product. In January, Nvidia's comments about reduced chiller requirements unsettled cooling stocks.6 Higher-temperature systems can change which equipment is needed, depending on the design and local conditions.4
Modine's range of products gives it ways to adapt. It does not establish that every dollar moving away from one product returns through another, at the same margin. The investment depends on product fit and manufacturing economics as well as total AI spending.
Sales nearly doubled. The margin went backward.
The latest quarter makes that distinction concrete. For the three months ended June 30, Modine reported $348.6 million in Data Centers sales, up from $183.7 million. Adjusted EBITDA, a profit measure before interest, tax, depreciation, amortisation and specified adjustments, increased much less.7,8
| Data Centers segment | June 2025 quarter | June 2026 quarter |
|---|---|---|
| Revenue | $183.7 million | $348.6 million |
| Adjusted EBITDA | $40.6 million | $51.7 million |
| Adjusted EBITDA margin | 22.1% | 14.8% |
Management attributes much of the pressure to expansion costs, component shortages and inefficient production. A favourable warranty settlement also made the prior-year comparison harder. It expects Data Centers adjusted EBITDA margins above 20% in the second fiscal half.9
The recovery mechanism is plausible: a staffed factory with missing components incurs costs without producing its planned output. Once supplies arrive, more shipments can spread those costs across more revenue. Strong demand can therefore coexist with temporarily weak margins.
The test is whether that improvement actually arrives. At the latest quarter's revenue, a 20% margin would produce about $69.7 million of adjusted EBITDA, roughly $18 million above the reported result. That is a sensitivity, not a forecast. It shows how much the same sales base can earn under different operating conditions.
The headline earnings growth needs similar care. Consolidated operating income slipped to $74.8 million even as adjusted earnings per share rose 44%. A favourable stock-compensation tax item helped EPS, and management expects much of that benefit to be offset later in the fiscal year.10
The customer is funding capacity, not guaranteeing profits
The strongest evidence for the bullish case is a customer's willingness to help pay for expansion. In May, Modine announced an agreement to reserve capacity for more than $4 billion of cooling products during calendar 2027 through 2029, supported by a $165 million upfront payment.5
The annual filing supplies an essential qualification: the customer may not purchase the projected amounts. Its identity remains confidential. The headline describes expected sales backed by a capacity arrangement, not $4 billion of unconditional purchase orders.11
The cash has already mattered. Modine received the advance in March and recorded a contract liability.11 Fiscal 2026 operating cash flow was $248.7 million; capital expenditure was $143.3 million, leaving $105.4 million of reported free cash flow.12
Subtract that $165 million inflow and the remainder becomes negative $59.6 million. This is an illustrative calculation, not Modine's adjusted metric. It keeps the expansion spending that the advance helped finance, so it should not be mistaken for the cash flow of a mature business.
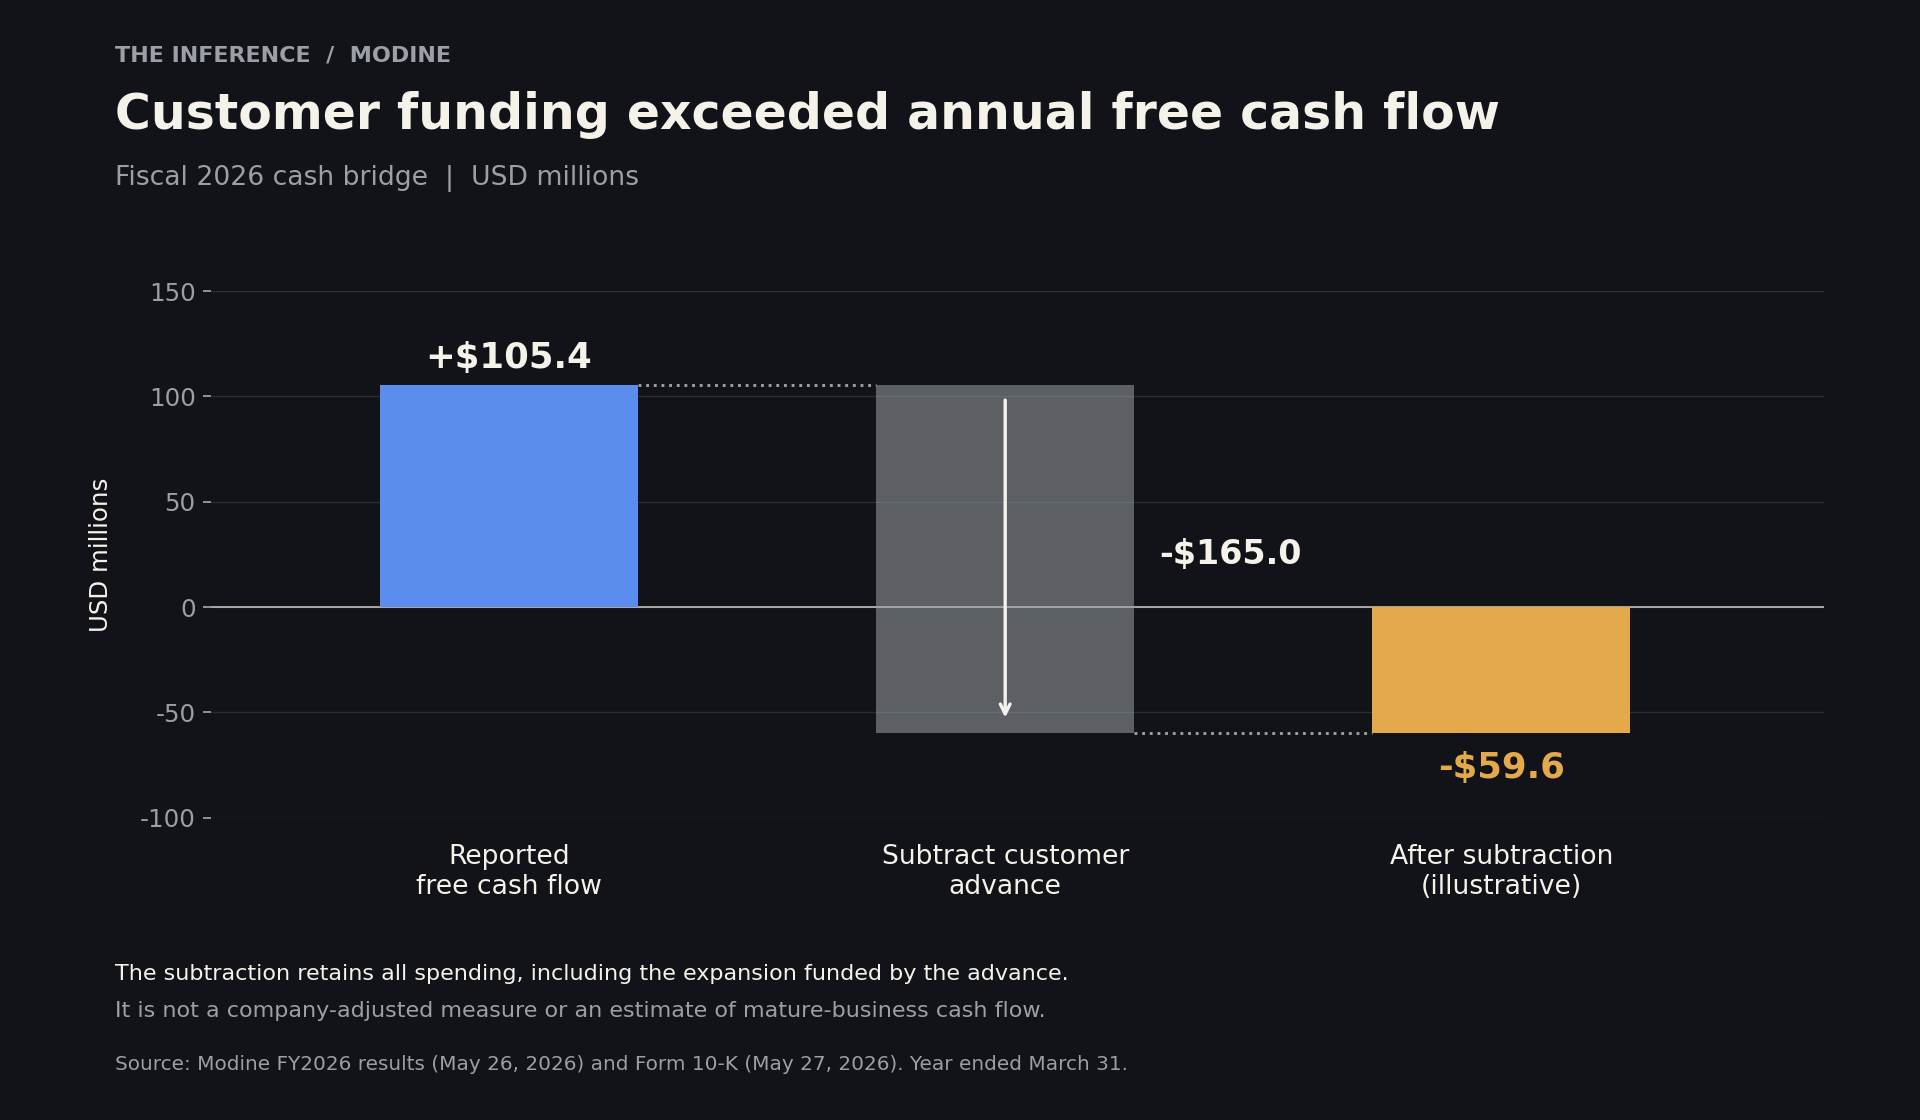
That does not make the advance bad financing. It reduces the amount Modine must fund elsewhere and demonstrates customer commitment. It does mean investors should distinguish customer-funded growth from cash generated by completed sales. June-quarter free cash flow was negative $5 million, including $14.9 million of restructuring and disposition payments.13
A customer can finance a factory before that factory proves it can earn a good return.
The valuation has to survive the separation
At the September 14 closing price of $182.18, and using July's disclosed share count, Modine's equity value was approximately $9.68 billion. Adding June net debt produces a simple enterprise-value estimate of $10.11 billion.13,14
Against the $665 million midpoint of fiscal 2027 adjusted EBITDA guidance, that is approximately 15.2 times. The same value would represent 19 times EBITDA if earnings came in 20% below that midpoint. This is sensitivity arithmetic, not an earnings prediction.10
The guidance already requires acceleration. After first-quarter adjusted EBITDA of $106.5 million, reaching the midpoint requires an average of $186.2 million across the remaining three quarters. Seasonality and the production ramp can help. The price is being compared with an earnings forecast that already assumes substantial improvement.8
The bullish argument is credible: factories already being expanded could support much higher sales, recovered margins and stronger cash generation. A multiple measured against today's investment burden may overstate the cost of tomorrow's earning capacity.
But the quoted guidance includes Performance Technologies for the entire fiscal year. It is not guidance for the remaining cooling business.10 Using it to value post-separation MOD would mix different collections of assets and earnings.
Under the announced transaction terms, Modine shareholders are expected to own approximately 40% of combined Gentherm, while Modine receives a $210 million cash distribution, both subject to adjustment.15 Shareholders retain an economic interest in the departing business through a different security.
That interest is not free upside to add to today's valuation. After closing, the analysis must allocate value between the two holdings, reflect the actual debt and cash movements, and remove departing earnings while accounting for costs left behind. The name change makes the story simpler. The transaction initially makes the accounting harder.
October 1 starts the real comparison
If the transaction closes as planned on October 1, the next useful disclosure is an outlook for the business that remains. Modine has said it will update guidance after closing.2,10 That gives investors a cleaner denominator for the price they are paying.
Then watch Data Centers margins and cash together. Improving factory efficiency should raise profit per dollar of sales. Over time, completed deliveries should support cash generation beyond additional customer advances, even as investment continues.
The case weakens if impressive sales growth keeps requiring more capital without better returns. It strengthens if Modine ships more through its expanded factories, restores margins and begins funding more growth from its own operations.
The next proof belongs in the cash-flow statement, not the new name.
How this brief was made
01Gathered & sourced363 channels · 1,049 articles▾
Agents swept 363 channels and ingested 1,049 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated15 claims · 10 data feeds▾
Every one of 15 load-bearing claims was checked against primary sources, with 10 live data feeds reconciling the figures and charts.
- 1Modine, proposed Modexus Solutions name announcement, Sep 10 2026 (primary announced intention; the name change remains subject to a separate shareholder vote, and the MOD ticker stays).
- 2Gentherm, shareholder approval of the combination with Modine's Performance Technologies business, Sep 10 2026 (primary vote result and expected Oct 1 closing, subject to remaining conditions).
- 3DatacenterDynamics, creation of Modine's dedicated Data Centers segment, Apr 16 2026 (independent reporting of a company organisational change; not a separate audit of its results).
- 4Modine, Airedale equipment for higher-temperature thermal architectures, Jan 13 2026 (primary product descriptions and manufacturer explanation; no claimed efficiency percentage used).
- 5Data Center Knowledge, cooling capacity reservation and customer funding, May 26 2026 (independent reporting and expert interpretation of company-claimed expected sales and the $165M funding; source 11 controls the purchase-guarantee qualification).
- 6Reuters, cooling-sector reaction to Nvidia's CES comments, Jan 6 2026, syndicated by Investing.com (supports market concern, not a conclusion that every data center can eliminate chillers).
- 7Zacks Investment Research, fiscal Q1 results and margin pressure, Aug 3 2026 (independent analysis of company-reported, unaudited segment results; values cross-checked against source 8, no consensus estimate used).
- 8Modine, fiscal Q1 2027 earnings presentation, Jul 30 2026, pages 7 and 10 (primary comparable segment figures, unaudited, including company-defined non-GAAP adjusted EBITDA).
- 9Modine, fiscal Q1 2027 earnings-call transcript, Jul 30 2026 (primary management explanation of production costs, the warranty comparison and forecast margin recovery; a forecast is not achieved performance).
- 10Modine, fiscal Q1 2027 results release, Jul 29 2026 (unaudited consolidated results, the stock-compensation tax explanation, and pre-separation fiscal 2027 guidance covering Performance Technologies for the full year).
- 11Modine, fiscal 2026 Form 10-K, filed May 27 2026 for the year ended Mar 31 (audited financial statements; Note 3 identifies the March customer advance and contract liability, and the risk disclosure explicitly qualifies projected customer purchases).
- 12Modine, fiscal Q4 and full-year 2026 results, May 26 2026 (cash-flow components cross-checked with the annual filing; free cash flow is a company-defined non-GAAP measure).
- 13Modine, Form 10-Q for Jun 30 2026, filed Jul 30 2026 (unaudited quarterly cash flow, June debt and cash, and 53,112,708 shares outstanding on Jul 24; share-count and balance-sheet dates differ from the valuation date).
- 14Stock Analysis / S&P Global Market Intelligence, MOD historical prices, Sep 14 2026 close of $182.18 (closing price independently matched to FinancialContent; no after-hours price used).
- 15Modine and Gentherm, joint Performance Technologies combination announcement, Jan 29 2026 (original approximately 40% ownership and $210M distribution, subject to adjustment; closing status updated by source 2).
03Reviewed & edited1 human editor▾
One editor read the draft against the evidence, tuned the framing, and signed off before it shipped.
Confidential tips
Know something about this story? We protect our sources. Reach the editor directly, or read our guide to sharing securely.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.