NextEra's $22.3 billion Texas power campus is not NextEra's to own
The campus is owned by Washington and Seoul, and Ketchum says NextEra need not put one cent in, collecting fees worth about half an owned plant's margin. The same 72 hours brought an Oklahoma price-gouging liability ruling and a Virginia merger clock running toward default approval.
 Vincent Jiang · 3 min read
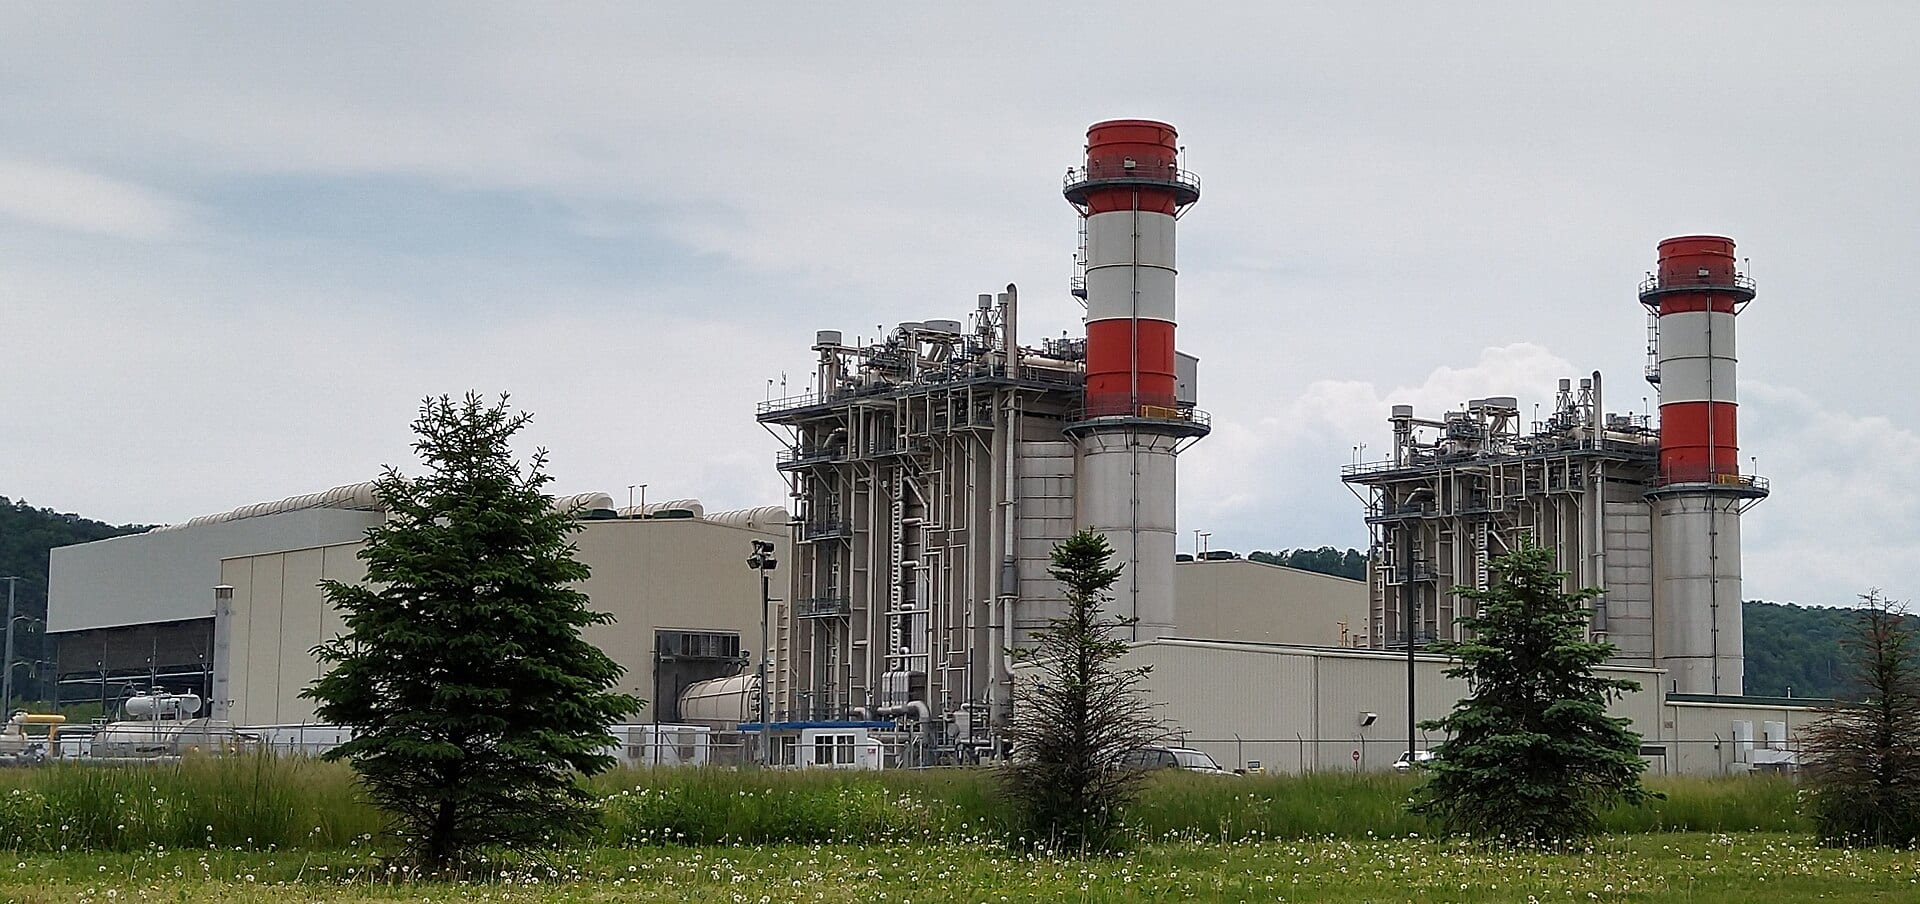
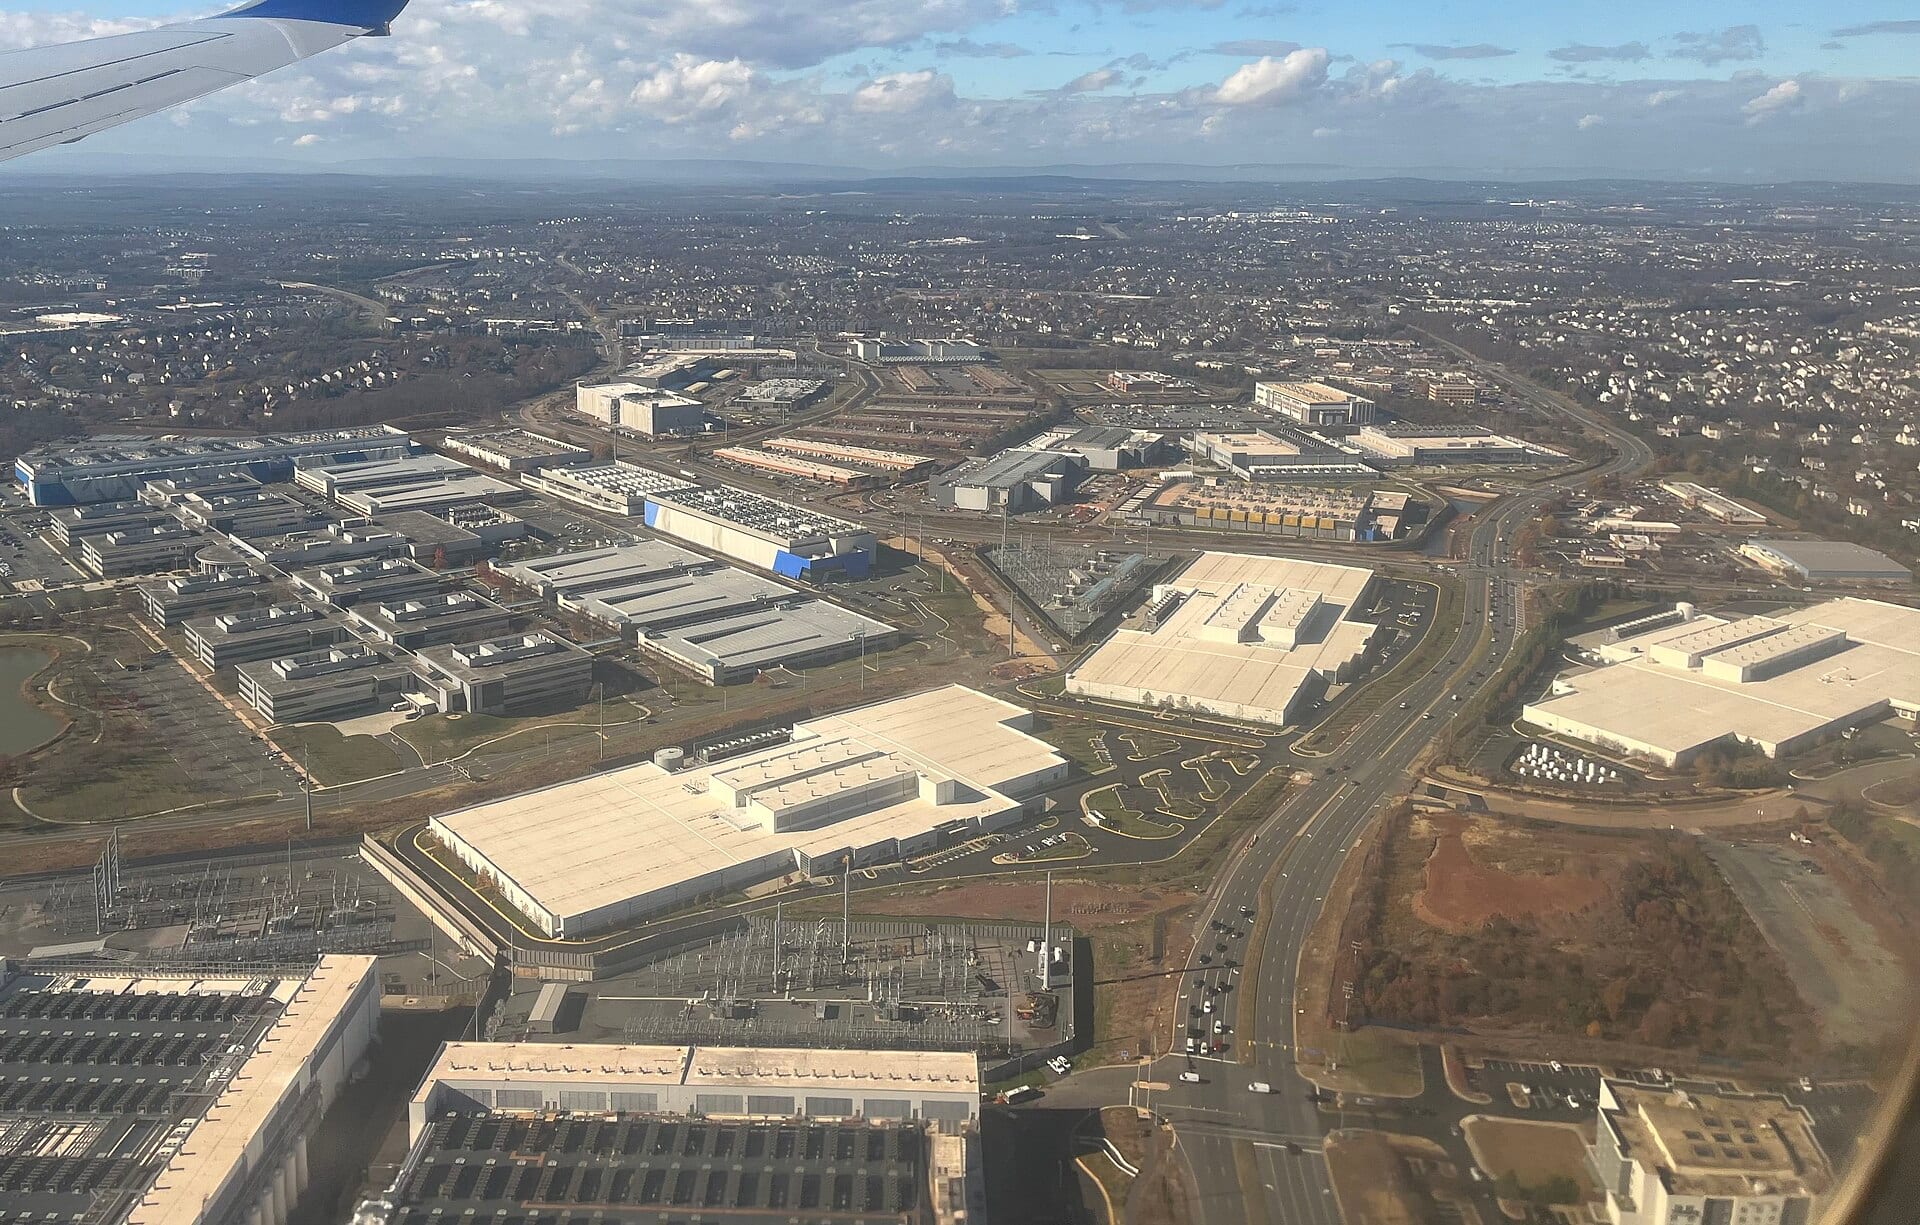
The story told on Sept 30 was that NextEra had won a $22.3 billion prize: 6.47 GW of natural gas generation in Encinal, Texas, built to feed a 5 GW data center campus that Related Digital is developing next door 1. The headline writers missed who owns the prize. Under the July 2025 US-Korea trade deal and its November investment MOU, the energy campus "will be owned jointly by the Republic of Korea and the U.S." 1. NextEra's name is on the build, not on the deed 1.
Not one cent, and not one plant
CEO John Ketchum put the business model on the record a day later at the Wolfe Research conference. $2.4 billion of government capital has already arrived for Project Star; $3.3 billion for the first 10 GW of Japanese-funded hubs 2. "We do not have to put one cent into these projects," he said. NextEra collects development, milestone and operating fees worth about 50% of the adjusted EPS it would earn by owning a comparable gas plant itself 2. That is 16 GW of federal-hub signings since the Q2 call, 18 GW of gas opportunities in all, against FPL's 24 GW gas fleet 2.
The gas build-out NextEra operates approaches the size of FPL's own 24 GW installed fleet
Data
| Value | |
|---|---|
| FPL installed gas fleet | 24 GW |
| NEE identified gas opportunities | 18 GW |
| Project Star planned generation | 6.47 GW |
The ledger, stated plainly: NextEra benefits as a fee-taker with zero capital at risk; Oklahoma ratepayers pay the securitized Uri gas debt on their monthly bills while a damages trial runs, and Virginia ratepayers are offered $185 million of credits against a $67 billion merger 235. The fee stream also depends on NextEra hitting construction and operating milestones on campuses owned by Washington, Seoul and Tokyo 2.
The ratepayer story, read in two directions
The same company selling "protect electricity customers" 1 was found liable for price gouging in Oklahoma. On Sept 28, Osage County District Judge Stuart Tate ruled NextEra Energy Marketing violated the state's Emergency Price Stabilization Act and Consumer Protection Act during Winter Storm Uri, charging Oklahoma utilities gas prices that soared from about $2.55 to $1,230.65 per unit 3. Overcharges, restitution and disgorgement are reserved for trial 37. Judge Tate wrote that ratepayers "will shoulder the securitized utility debt for years to come" 7.
Virginia is the other front. Fourteen federal legislators told FERC on Sept 30 to distrust the merger's bill credits, citing NextEra's 2014 Hawaii attempt, where regulators called its rate-credit assurances "inadequate" and killed the deal 4. Ketchum answered Oct 1 with $85 million more in residential credits, $100 million for low-income bill assistance and 1,000 Virginia jobs 2. But the state's own clock barely moved: Gov. Spanberger let the Sept 30 window to extend the State Corporation Commission's review lapse, and if the SCC misses its Jan. 11, 2027 deadline, the merger is approved by default 5.
What decides it
Two dated events. The Oklahoma damages trial, which will calculate overcharges, restitution and disgorgement, and the Virginia SCC ruling on Jan. 11 35. Management projects the combined company grows from 110 GW to about 240 GW by 2032 with adjusted EPS growth above 9%, a projection, not a result 2. The fee margin and the Jan. 11 default are the questions investors should be discounting before the docket decides for them.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.