Nvidia pays $1.5 billion toward Amkor's US packaging build; Amkor's depreciation bill starts in 2027
A 274.27 billion won construction filing on October 8 put a June 23, 2028, finish date on Amkor's Gwangju expansion. Nvidia's $1.5 billion prepayment lands around 2027 and Arizona depreciation starts in the same window, which makes the October 26 report the last clean quarter on the calendar.
 Vincent Jiang · 3 min read
A construction filing in Seoul has done what Amkor's investor decks have not: put an exact date on the AI buildout. Dongbu Construction disclosed on October 8 a 274.27 billion won contract, excluding VAT, to expand Amkor Technology Korea's−3.82% — Amkor Technology Korea, down 3.82 percent today Building D at Gwangju, running from October 8, 2026, to June 23, 2028, and worth 15.60% of the builder's 2025 revenue 1. Korea's exchange disclosure confirms the amount and the 20-month window 2. Gwangju is earmarked for data center and advanced packaging programs 3.
Nvidia pays first
The $1.5 billion agreement Nvidia announced on July 23 is, in structure, a customer financing a factory: Nvidia+0.02% — Nvidia, up 0.02 percent today pays a prepayment to expand Amkor's US packaging capacity 4512. Amkor told investors the cash arrives around 2027 and is credited back quarterly as US services deliver, over a term of five to 10 years 3. That sits beside the 10-year US packaging agreement with TSMC signed in June 35.
The second quarter showed the leverage in the existing factories: record revenue of $1.9 billion, up 26%, gross margin of 16.8% against 12.0% a year earlier, diluted EPS of $0.70 versus $0.22, and utilization up from the 50s into the 70s 3.
Gross margin has recovered almost five points from its early-2025 trough
Data
| Gross margin | |
|---|---|
| Q3 '23 | 15.5% |
| Q4 '23 | 15.9% |
| Q1 '24 | 14.8% |
| Q2 '24 | 14.5% |
| Q3 '24 | 14.6% |
| Q4 '24 | 15.1% |
| Q1 '25 | 11.9% |
| Q2 '25 | 12% |
| Q3 '25 | 14.3% |
| Q4 '25 | 16.7% |
| Q1 '26 | 14.2% |
| Q2 '26 | 16.8% |
The bill lands first too
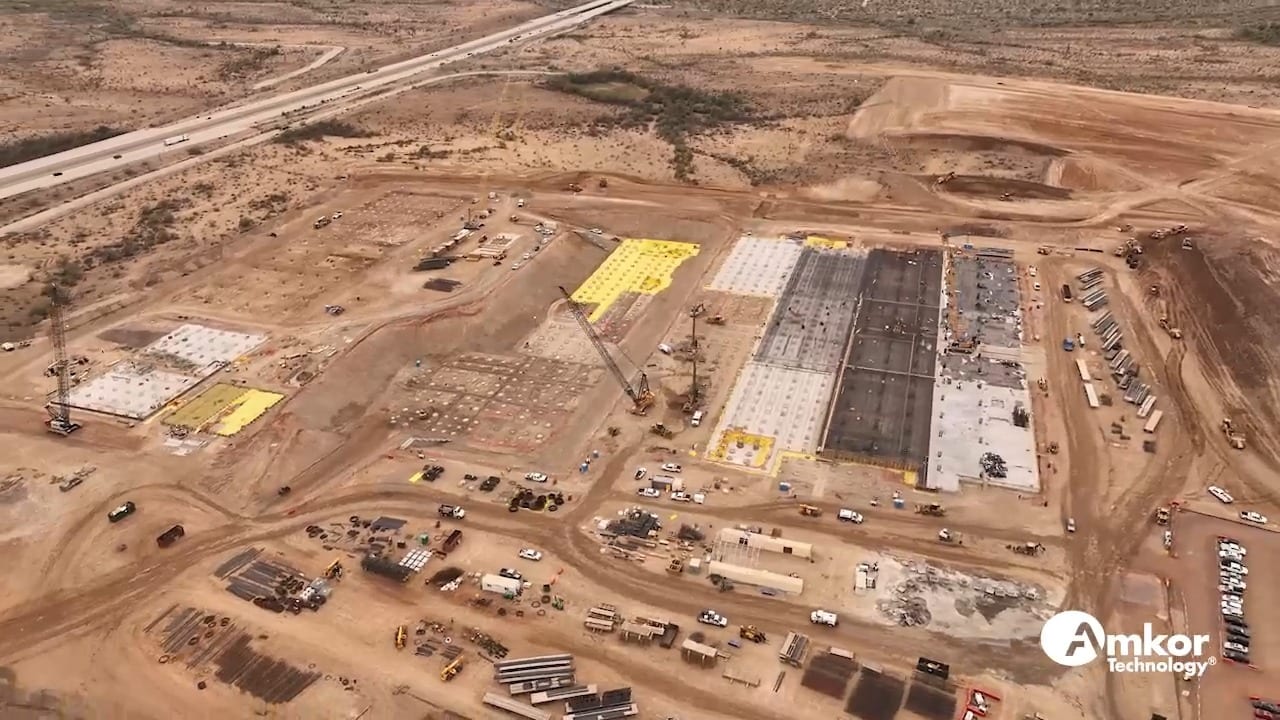
Between the prepayment and the first invoice sits the build. First-half capital spending reached $688.4 million, up from $226.1 million a year earlier, against a full-year plan of $2.5-3.0 billion 67. The Arizona campus is now a planned $12 billion project, its second phase starting construction in late 2027 and finishing by the end of 2029 8. Behind it: $2.5 billion of debt, a $1.15 billion zero-coupon convertible issued in May, and $1.47 billion of purchase obligations 36.
Management has already flagged US factory depreciation as a 2027 and 2028 margin headwind 3, a warning sell-side analysts repeat 9, and the SiP move to Vietnam idles Korean capacity into the first half of 2027 3. Nvidia's money buys the building. Amkor's margin line buys the empty months.
Quarterly capex has run near triple year-ago levels for two straight quarters
Data
| Capital spending | |
|---|---|
| Q3 '23 | $0.23B |
| Q4 '23 | $0.23B |
| Q1 '24 | $0.09B |
| Q2 '24 | $0.17B |
| Q3 '24 | $0.2B |
| Q4 '24 | $0.29B |
| Q1 '25 | $0.08B |
| Q2 '25 | $0.15B |
| Q3 '25 | $0.25B |
| Q4 '25 | $0.33B |
| Q1 '26 | $0.22B |
| Q2 '26 | $0.44B |
What October 26 decides
Third-quarter guidance is the clean quarter: revenue of $1.95-2.05 billion, gross margin of 18.5-19.5%, EPS of $0.72-0.82 3, reported after the close on October 26 10. The market has already banked the gain: shares up 84.5% over twelve months, closing at $51.00 on October 8 911, with consensus 2026 EPS of $2.60 implying 73.3% growth 6.
No filing says how much of the depreciation drag Nvidia's money offsets; the disclosures set dates, not totals. The read-through runs wide: Nvidia locks in US packaging, and the tool cycle, with Onto Innovation on the inspection critical path, follows the cranes 12. The number to listen for on October 26 is whether Q4 commentary puts a figure on the 2027 depreciation cadence. After this print, the capex, the prepayment and the depreciation all land in the same window.
More about NVIDIA
NVDA · Fiscal Q2 2027Revenue rose 106% to $96.2B, 92.5% of it from Data Center, “driven by the ramp of our Blackwell Ultra infrastructure”. Gains on equity stakes of $7.8B lifted net income to $59.7B.
Show as a table
| Line | Value |
|---|---|
| Revenue | $96.2B |
| Gross margin | 75.0% |
| Operating margin | 66.2% |
| Net income | $59.7B |
| Hyperscale | $48.7B |
| AI clouds & enterprise | $40.3B |
| Data Center | $89.0B |
| Edge Computing | $7.2B |
| Gross profit | $72.1B |
| Cost of revenue | $24.1B |
| Other income | $7.8B |
| Operating income | $63.7B |
| Operating expenses | $8.4B |
| Tax | $11.8B |
| R&D | $7.1B |
| SG&A | $1.4B |
Deepdive
AI-generated from this story and its cited sources. Not investment advice.