Nvidia prices its GPUs at ten years. Wall Street lends against three.
Lenders are rebuilding the first deals in Nvidia's $500 billion compute-financing plan around guarantees and customer contracts rather than chip collateral alone. The risk the loan market refuses to take is drifting toward the balance sheet that just committed $235 billion to buybacks.
 Vincent Jiang · 3 min read
A rack of chips became loan collateral
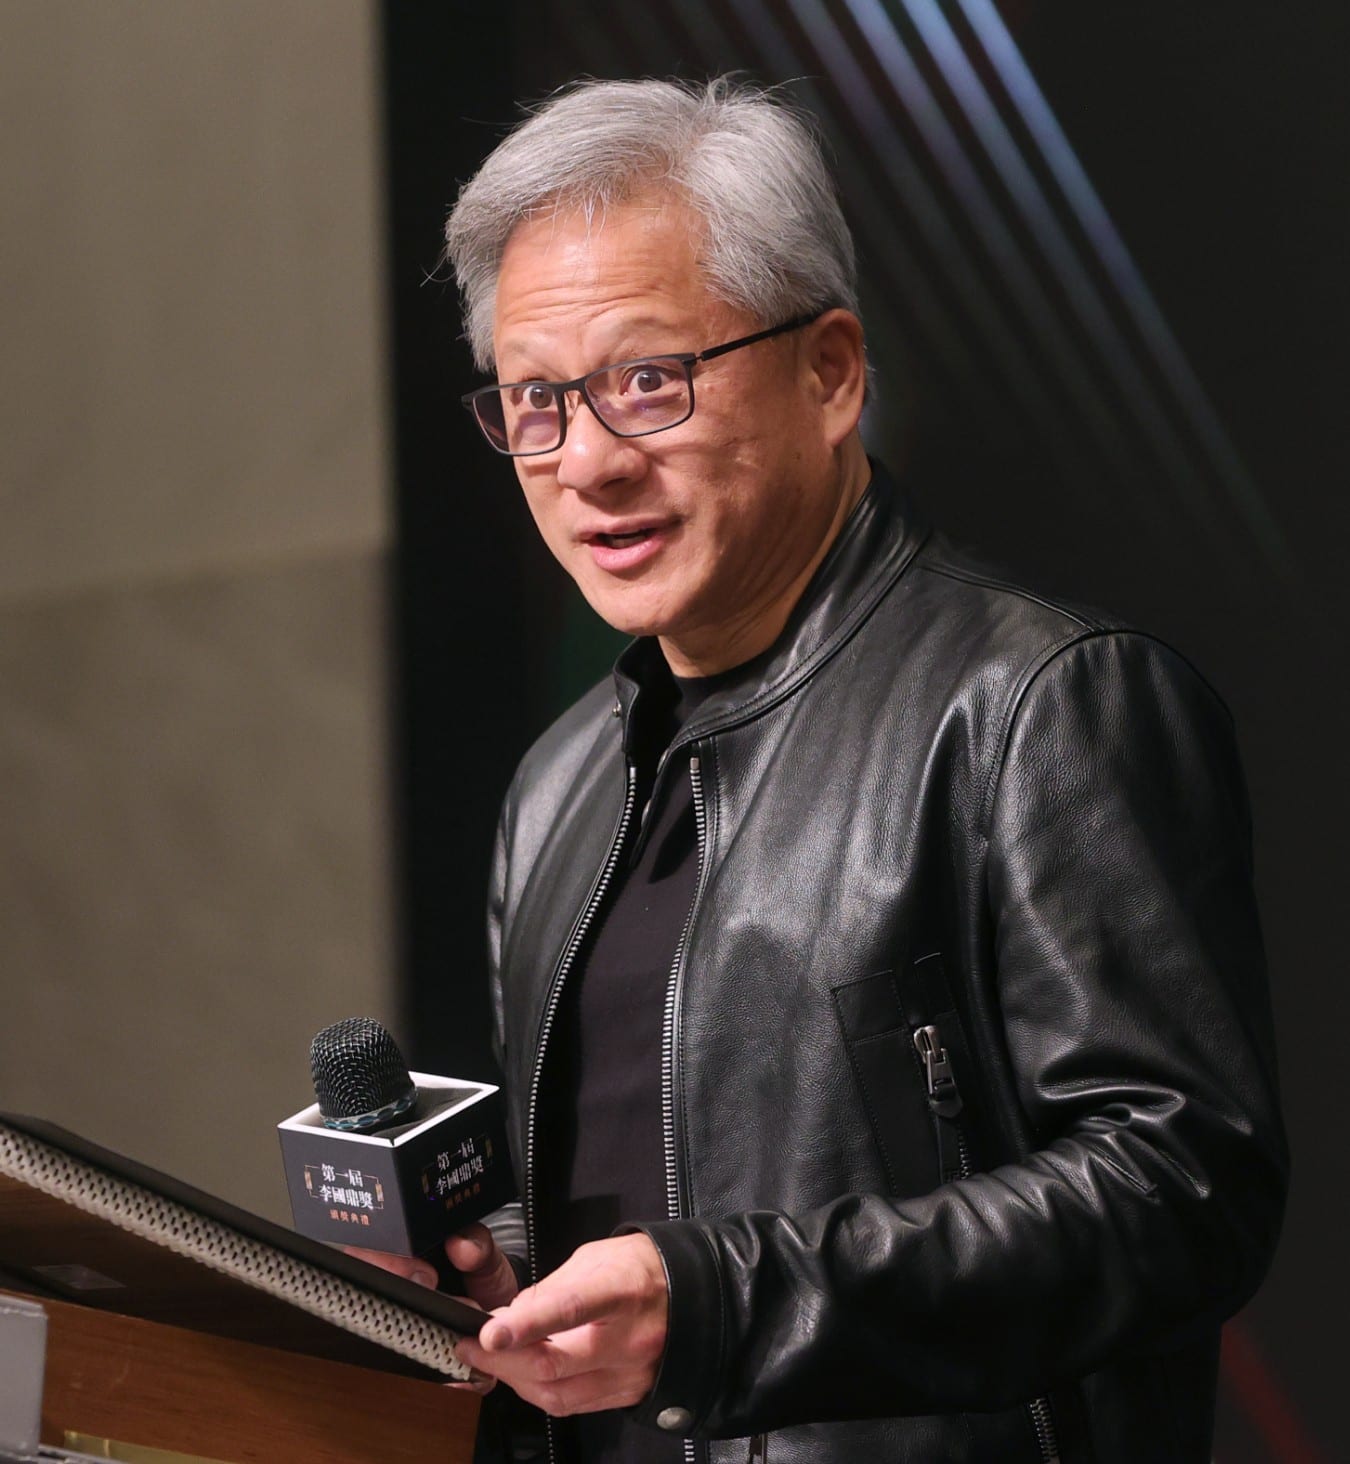
On 10 August 2026, Jensen Huang sat beside six Wall Street chiefs and declared chips an "investable asset class" for the first time; Larry Fink called it the next future of financial engineering, kin to mortgage-backed securities 2. The asset behind the claim is the GB300 NVL72, a rack Nvidia says can earn revenue for a decade 1. This week, the people who would lend against it answered.
Half a trillion dollars needs a holder of risk
The memorandums with Apollo, Blackstone, BlackRock, Brookfield, Goldman Sachs and KKR aim to mobilize more than $500 billion of third-party capital for AI buildouts 2. The money arrives in a market already full: about $236 billion of AI-linked debt sold through 31 May 2026, four times the 2025 pace, on track for roughly $570 billion this year on Morgan Stanley's numbers 4. The holders are insurers, credit funds and the bond indexes inside ordinary retirement accounts 4.
The 25% cap is already bending
The plan was sold with residual-value guarantees of no more than 25%, pitched as the answer to circular-financing fears 1. Banks did not buy it. They want guarantees on every deal, or investment-grade revenue behind the debt, and tens of billions now in the pipeline are secured by Nvidia chips, customer contracts and Nvidia's underlying guarantee 1. The collateral was supposed to be the silicon. In the pipeline, it is Nvidia.
The price list already exists
CoreWeave's $8.5 billion GPU loan carries an A3 rating only because Meta's payments sit behind it, and Broadcom backstopped more than 80% of a $35 billion structure for Anthropic 1. SharonAI just paid a fixed 9.95% for $356 million secured on GPUs and their cash flows, Goldman Sachs among the lenders 5. A $3.1 billion loan arranged with MUFG to buy Nvidia processors drew about $20 billion of demand yet priced wide because its customers were AI labs 6. Vendor financing and circular deals helped end the dot-com boom, as a Morningstar note reminds 1.
Lenders underwrite GPUs at three to four years; Nvidia argues a decade
- Estimate
Data
| Value | Range | |
|---|---|---|
| Bank underwriting of GPUs | 3.5 yrs | 3–4 yrs |
| Cloud server depreciation | 5.5 yrs | 5–6 yrs |
| Barkr on GB300 NVL72 (estimate) | 9.5 yrs | 9–10 yrs |
| Huang revenue-life claim (estimate) | 10 yrs | — |
Nvidia's own exhibits
Nvidia points to cloud operators stretching server depreciation to five or six years from three or four, and to Barkr, a valuer, putting the GB300 NVL72's useful life at 9 to 10 years 1. S&P's Andrew Chang concedes GPUs have run "well north of five years" so far, while taking "a conservative view" of their value 1. Demand for the paper remains high 1. But a depreciation schedule is an accounting choice; a guarantee is a balance-sheet event, and the deals are migrating toward exactly the protections Nvidia said it would not need.
Whose balance sheet insures the other seven years
On 28 September 2026, Nvidia's board added $150 billion to its buyback, lifting the remaining authorization to $235 billion through fiscal 2028 3. Every guarantee Nvidia writes to keep the plan moving puts the residual value of its own silicon back on that balance sheet. Wall Street will advance three years against a GB300; shareholders are insuring the other seven. The first deals to price, and the November results, will show what that insurance costs.
More about NVIDIA
NVDA · Fiscal Q2 2027Revenue rose 106% to $96.2B, 92.5% of it from Data Center, “driven by the ramp of our Blackwell Ultra infrastructure”. Gains on equity stakes of $7.8B lifted net income to $59.7B.
Show as a table
| Line | Value |
|---|---|
| Revenue | $96.2B |
| Gross margin | 75.0% |
| Operating margin | 66.2% |
| Net income | $59.7B |
| Hyperscale | $48.7B |
| AI clouds & enterprise | $40.3B |
| Data Center | $89.0B |
| Edge Computing | $7.2B |
| Gross profit | $72.1B |
| Cost of revenue | $24.1B |
| Other income | $7.8B |
| Operating income | $63.7B |
| Operating expenses | $8.4B |
| Tax | $11.8B |
| R&D | $7.1B |
| SG&A | $1.4B |
Deepdive
AI-generated from this story and its cited sources. Not investment advice.