NXPの産業・IoT部門、増収2億900万ドルで車載部門に並ぶ
ラファエル・ソトマヨール最高経営責任者(CEO)はNXPを、車載が最大市場のフィジカルAI(Physical AI)企業と位置づける。規模の小さい産業・IoT部門が直近四半期、同じ2億900万ドルの増収を達成した。
 Vincent Jiang · 2 min read
NXPセミコンダクターズのラファエル・ソトマヨール最高経営責任者(CEO)は、自社の買収を「車載への賭け」と評したアナリストの見方を訂正した。
転換を裏付ける「領収書」
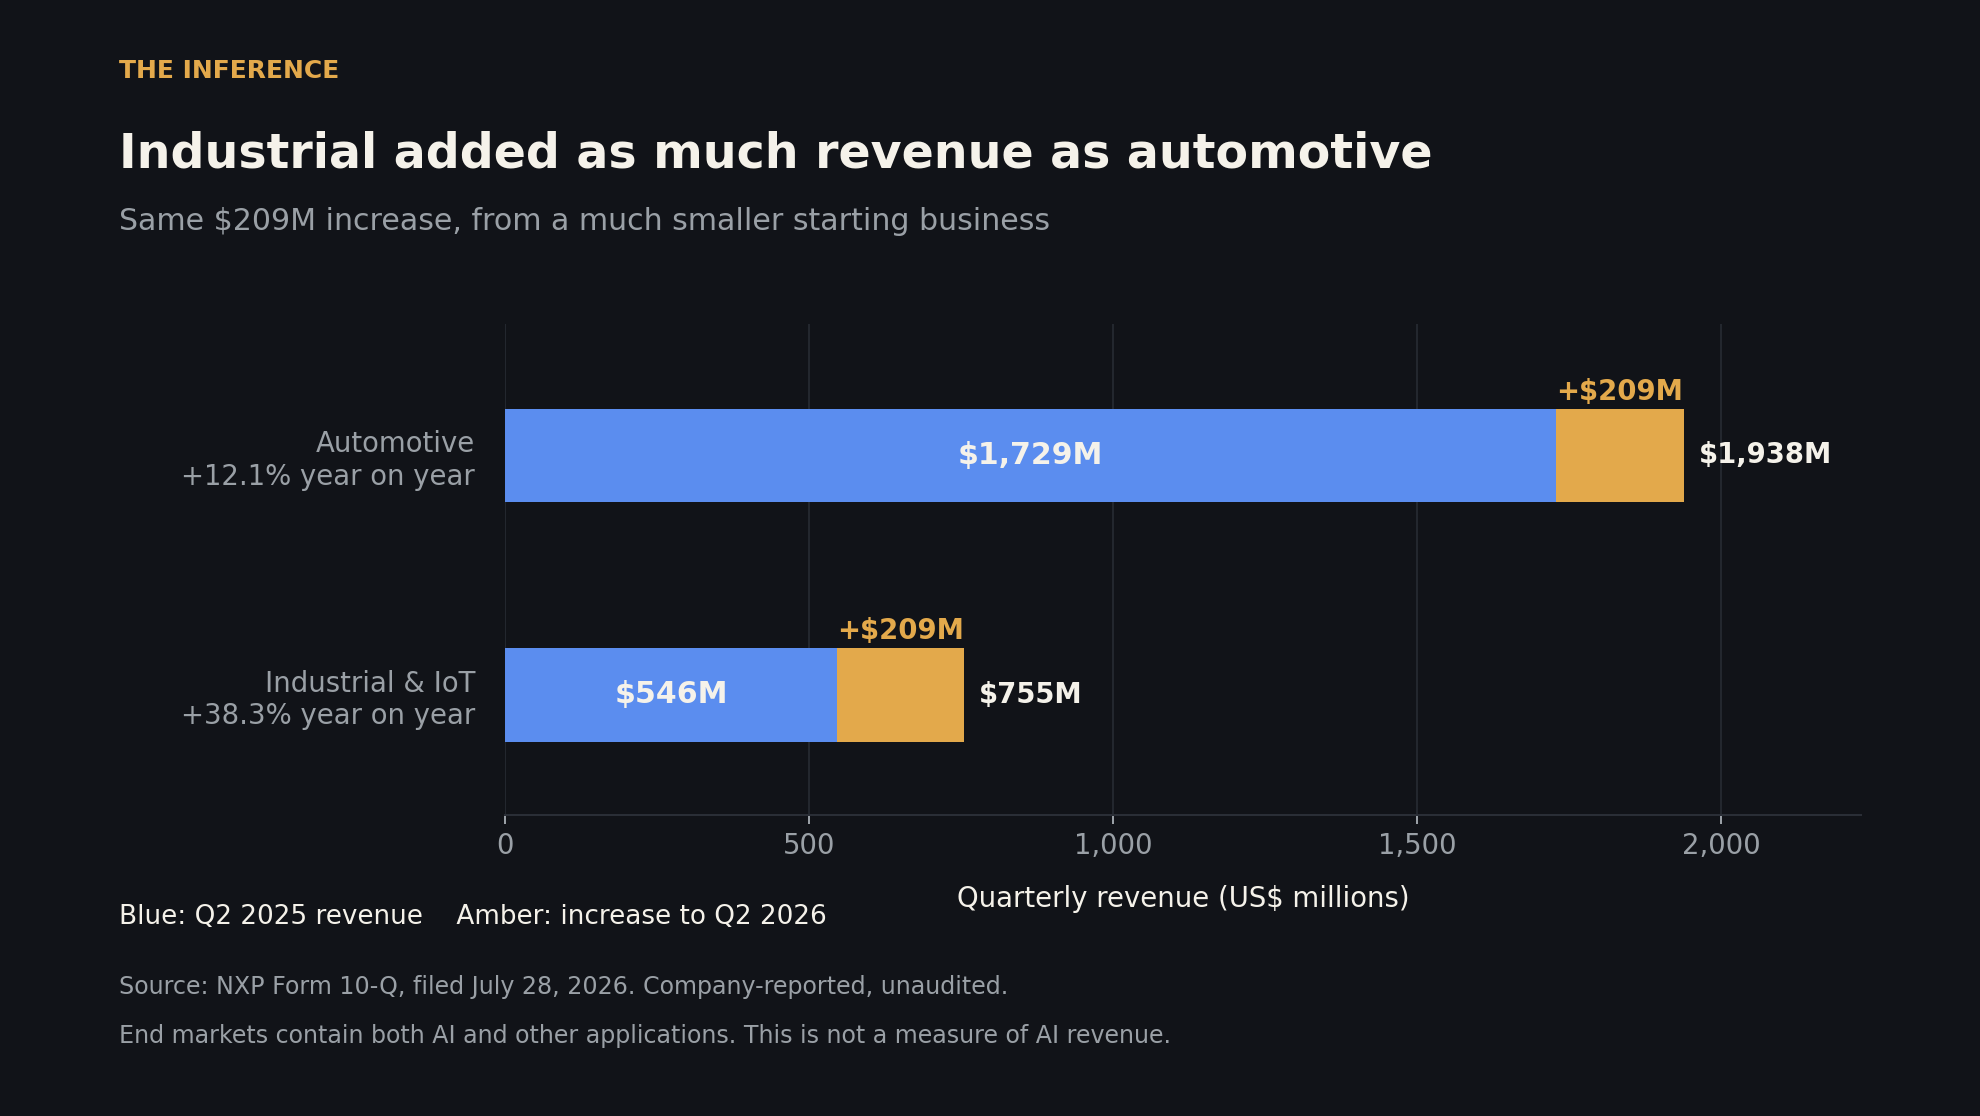
9月9日にゴールドマン・サックスが開いたカンファレンスで、ソトマヨールCEOは同社を、車載を最大市場とするフィジカルAI企業だと説明した。その主張の「領収書」を、規模の小さい産業・IoT部門が提示した。第2四半期の売上高は前年同期比で2億900万ドル増え、増加額は車載部門とちょうど同じになった。1,2
車載は今も四半期売上高の55%を生み出す。そのエンジニアリングの蓄積こそNXPの拡大の土台だ。商業上の焦点は、処理・ネットワーキング・制御のより価値の高い組み合わせを、より多様な機械に売れるかどうかにある。より広い看板は、顧客が買うものを変えて初めて意味を持つ。2
意外な出発点
意外なのは出発点だ。1年前、車載部門は産業・IoT部門の3倍を超える規模だった。ここでの計算には、6月28日締め四半期について会社が開示した監査前の数値を使った。比較には買収と事業売却が含まれ、有機的な成長やAI収益だけを切り出したものではない。2
フィジカルAIが金を生むのは、機械が仕事をやり遂げたときだ。
戦略のみせどころ
ソトマヨール氏の戦略が商業的に面白くなるのは、ここからだ。ロボットメーカーは知覚・動作・安全を協調させて動かさなければならない。3月16日に発表されたNXPとエヌビディア(NVIDIA)の協業は、この課題を軸にビジョン処理、モーター制御、ネットワーキングを束ねる。ここから推論できるのは、顧客側の統合作業を減らすことが、機械1台の設計の複数の部分をまとめて獲得する助けになる可能性がある、ということだ。発表自体には収益面の証拠はない。4
このニーズは、NXPのプレゼンテーションの外にも実在する。ベックホフ(Beckhoff)が4月16日に紹介したDexterityのロボット「Mech」についての記述は、AIの意思決定システムを補完する独立したモーション制御と安全制御の姿を描いている。エンジニアリング上の要求を裏付けると同時に、顧客には他の供給業者もあることを示すものだ。5
より近い試金石はデータセンター
より近い商業上の試験は、すでにデータセンターで始まっている。経営陣は4月、当該用途の2025年の売上高を約2億ドルと述べ、2026年は5億ドル超と予想した。同社のチップは冷却、基板、インフラの管理を支える。これらの売上は既に産業・IoTと通信インフラの中に含まれており、改めて加算すれば機会を二重に数えることになる。あくまで会社側の予想である。3
懐疑的な読み
最も有力な懐疑論は、これがAIのラベルを付けた産業市況の回復にすぎない、というものだ。工場稼働率の改善がNXPの利益率向上に寄与しており、会社も報告した成長のうちAIの貢献を切り分けていない。このためバリュエーションを根拠とする議論には限界が生じるが、1台の機械に搭載する部品を増やして売る機会が消えるわけではない。2
ソトマヨール氏は9月のカンファレンスで、人型ロボットの商機を2032年ごろと位置づけた。投資家にはもっと近い期限がある。通期決算だ。データセンター向けの売上が経営陣の見通しをクリアするか、産業向けの急成長が全社のキャッシュフロー増強と歩調を合わせるかを注視したい。1
次の決算が示すべきは、顧客が実際に何を買ったかである。
How this brief was made
01Gathered & sourced333 channels · 1,059 articles▾
Agents swept 333 channels and ingested 1,059 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated5 claims · 23 data feeds▾
Every one of 5 load-bearing claims was checked against primary sources, with 23 live data feeds reconciling the figures and charts.
- 1NXP at the Goldman Sachs Communacopia conference, Sep 9 2026 (participant transcript hosted by StockAnalysis: Sotomayor's physical-AI framing, the systems strategy and the roughly 2032 humanoid timeframe. Company-claimed strategy and forecast, not independent confirmation; numerical transcription errors elsewhere in the transcript were excluded).
- 2NXP SEC Form 10-Q for the quarter ended Jun 28 2026, filed Jul 28 (primary and unaudited: the end-market table behind the $209 million comparison, the 55% automotive share and factory utilization. Reported growth includes portfolio changes and is not organic growth or AI revenue).
- 3NXP Q1 2026 earnings-call transcript, Apr 28 2026 (company-claimed: about $200 million of 2025 data-center revenue and a forecast above $500 million for 2026. An actual figure and an expectation are not alike, and both sit inside end markets already reported).
- 4NXP's collaboration announcement with Nvidia, Mar 16 2026 (company-claimed product integration across vision, motor control and networking; no revenue is disclosed, and the integration advantage drawn from it is our inference).
- 5Beckhoff's case study on Dexterity's Mech, Apr 16 2026 (single-source participant account; it supports the architectural argument that motion and safety control sit beside an AI decision system, and does not establish NXP content in that machine).
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.