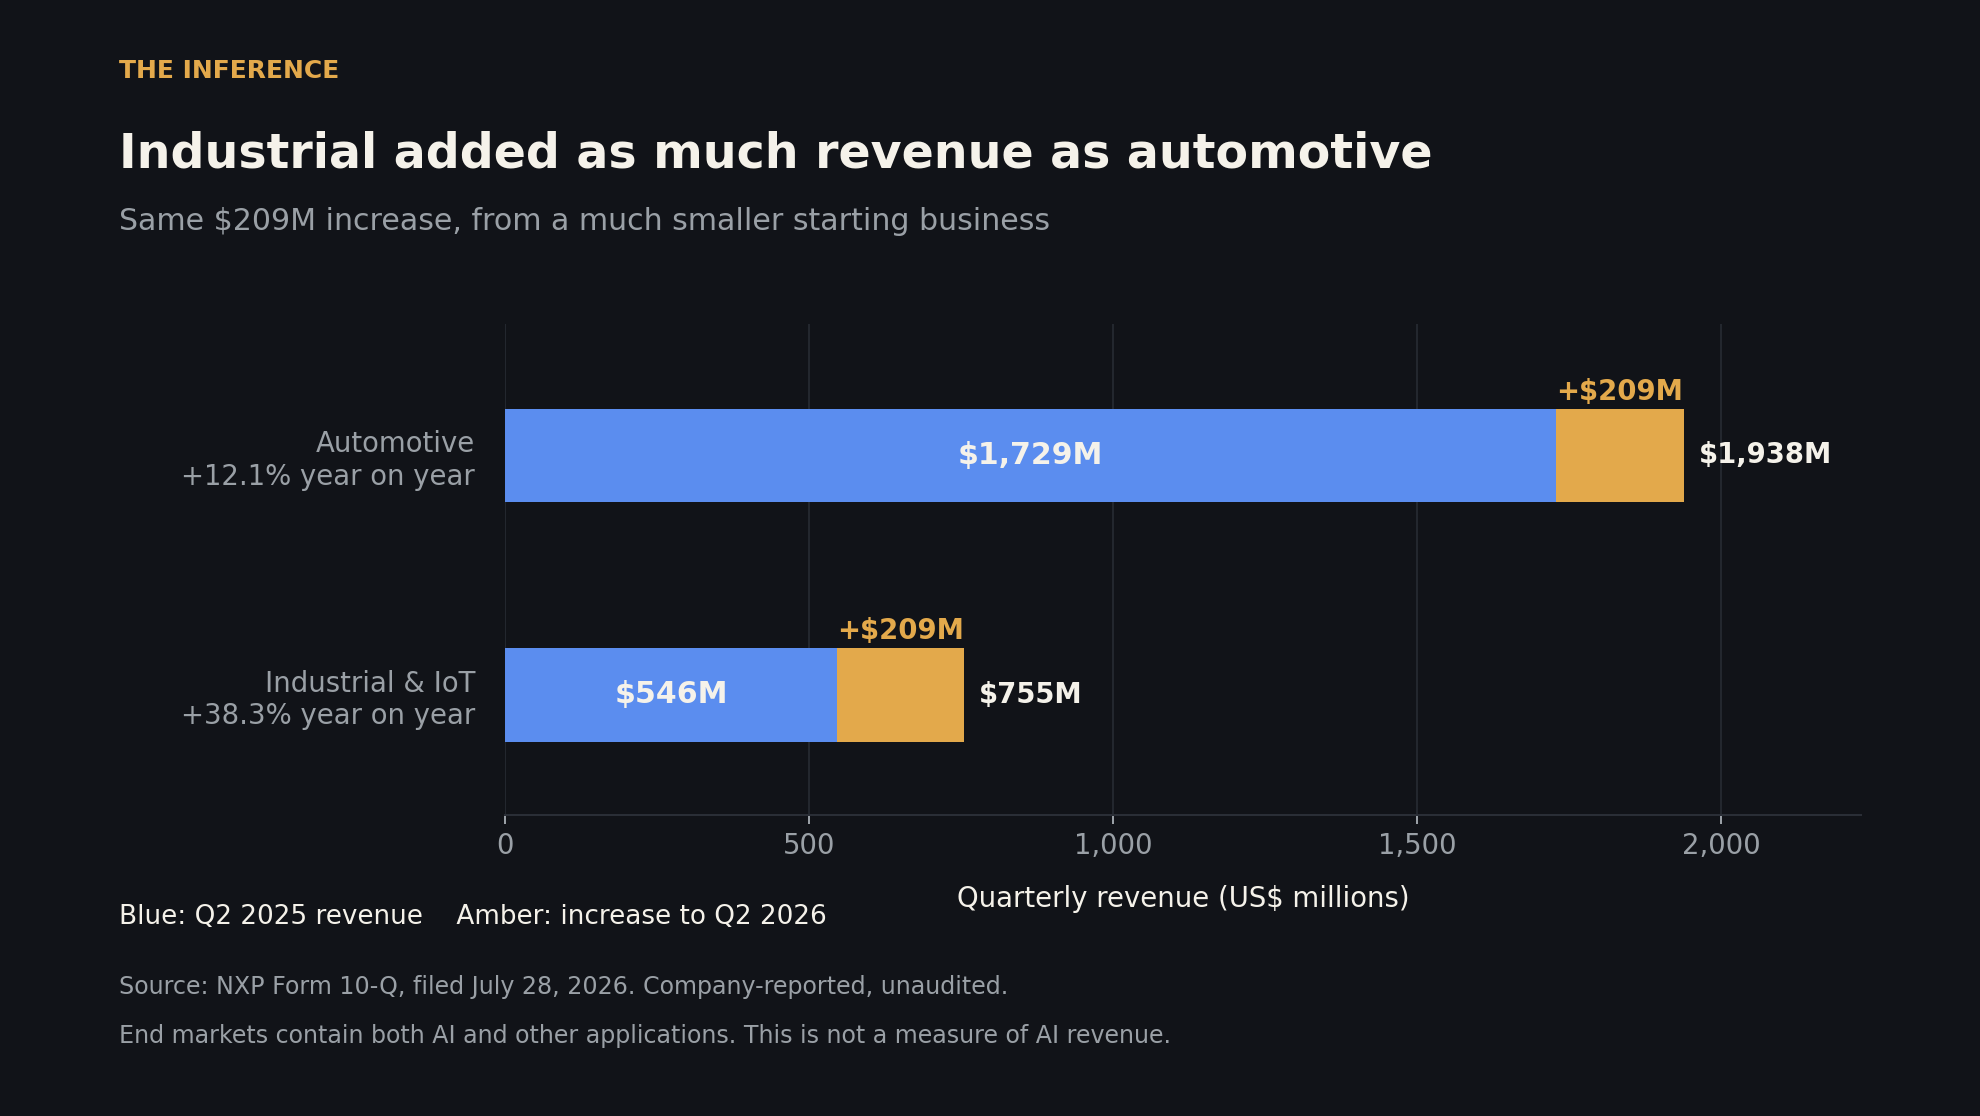
恩智浦工业业务单季增长额追平汽车业务的2.09亿美元
首席执行官拉斐尔·索托马约尔将恩智浦定位为一家物理AI公司,汽车是其最大市场。规模更小的工业业务单季度增长额恰好追平了2.09亿美元。
 Vincent Jiang · 2 min read
拉斐尔·索托马约尔纠正了分析师将其收购行为描述为“押注汽车”的说法。
战略转向的凭证
在高盛9月9日的会议上,恩智浦首席执行官将公司描述为一家物理AI公司,汽车是其最大市场。其规模较小的工业业务为此提供了凭证:第二季度营收同比增加2.09亿美元,与汽车业务的增量完全一致。1,2
汽车业务仍贡献了季度销售额的55%。其工程专业能力是恩智浦扩张的基石。商业层面的问题在于,公司能否向更多种类的机器销售更具价值的处理、网络与控制组合方案。一个更宏大的标签,唯有在它能改变客户采购行为时才具有意义。2
令人意外的起点
意外之处在于起点:一年前,汽车业务的规模是工业与物联网业务的三倍以上。上述计算基于公司报告的、截至6月28日季度的未审计数据。该对比包含了并购与剥离因素,并未剥离有机增长或AI收入。2
物理AI的商业回报,体现在机器完成任务之时。
战略的商业价值显现之处
这正是索托马约尔战略展现出商业吸引力的地方。机器人制造商必须让感知、运动与安全系统协同工作。恩智浦3月16日与英伟达的合作,正是围绕这一问题,整合了视觉处理、电机控制与网络连接。其推论是:减少客户的集成工作,可能有助于恩智浦赢得一台机器设计中的多个部件。但该公告未提供营收证据。4
需求并非只存在于恩智浦的演示文稿中。贝克霍夫4月16日对Dexterity公司Mech机器人的描述表明,独立的运动与安全控制器正与其AI决策系统协同工作。这证明了工程需求的存在,同时也显示客户拥有其他供应商选择。5
更近的考验:数据中心
更近的商业考验已在数据中心领域展开。4月,管理层预计2025年来自这些应用的营收约为2亿美元,并预测2026年将超过5亿美元。其芯片用于管理散热、电路板及基础设施。这些销售已计入工业与物联网以及通信基础设施终端市场;若重复计算则会夸大机会。这仍是公司自身的预测。3
质疑的视角
最强的质疑视角是:这不过是一场工业复苏,却被贴上了AI的标签。工厂产能利用率提升贡献了恩智浦利润率的改善,而公司尚未分离出AI对报告增长的具体贡献。这限制了估值论证,但并未消除向每台机器销售更多内容的机会。2
索托马约尔在9月的会议上将人形机器人机会的时间点设定在2032年左右。投资者面对的时间线更近:全年业绩。需观察数据中心销售额能否达到管理层预测,以及更快的工业增长是否伴随着更强劲的公司现金流。1
下一期财报需要证明客户实际购买了什么。
How this brief was made
01Gathered & sourced333 channels · 1,059 articles▾
Agents swept 333 channels and ingested 1,059 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated5 claims · 23 data feeds▾
Every one of 5 load-bearing claims was checked against primary sources, with 23 live data feeds reconciling the figures and charts.
- 1NXP at the Goldman Sachs Communacopia conference, Sep 9 2026 (participant transcript hosted by StockAnalysis: Sotomayor's physical-AI framing, the systems strategy and the roughly 2032 humanoid timeframe. Company-claimed strategy and forecast, not independent confirmation; numerical transcription errors elsewhere in the transcript were excluded).
- 2NXP SEC Form 10-Q for the quarter ended Jun 28 2026, filed Jul 28 (primary and unaudited: the end-market table behind the $209 million comparison, the 55% automotive share and factory utilization. Reported growth includes portfolio changes and is not organic growth or AI revenue).
- 3NXP Q1 2026 earnings-call transcript, Apr 28 2026 (company-claimed: about $200 million of 2025 data-center revenue and a forecast above $500 million for 2026. An actual figure and an expectation are not alike, and both sit inside end markets already reported).
- 4NXP's collaboration announcement with Nvidia, Mar 16 2026 (company-claimed product integration across vision, motor control and networking; no revenue is disclosed, and the integration advantage drawn from it is our inference).
- 5Beckhoff's case study on Dexterity's Mech, Apr 16 2026 (single-source participant account; it supports the architectural argument that motion and safety control sit beside an AI decision system, and does not establish NXP content in that machine).
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.