オラクル、売上高急成長 リストラ予算も拡大
インフラ売上高が倍増を超えるも、オラクルは再編計画を拡大。大部分は退職金に充当
 Vincent Jiang · 2 min read
販売提案の後の署名
9月10日、ヒラリー・マクソンはコスト効率化がオラクルの利益率を守ったと指摘した。1
翌日、財務責任者は約7億ドルの再編計画拡大を示す書類に署名した。2
退職予算の拡大
予想コストは約28億ドルに上り、大半は退職金だ。追加分は更なる計画行動を示すが、オラクルは新たなリストラ人数を公表していない。2,3
5月末時点で、オラクルの従業員数は前年同期比で約2万1千人減少していた。これは過去最大の純減であり、今回のリストラ対象数ではない。3
成功が労働者を追い詰めることも
販売は好調だ。8月31日終了四半期のインフラ収入は121%増の74億ドル、総収入は30%増の193億ドルとなった。4,8
だが、インフラはビジネスモデルを変える。調整後粗利益率は前年比68.7%から61%へ低下した。マクソン氏は、運営コストの低減がこの圧力を緩和したと説明した。1
注目点は、堅調な需要と人員削減圧力が同時に存在し得ることだ。成長が資本を消費する限り、売上増だけでは従業員は守られない。業績説明会での説明とは関係なく。
資金不足は解消されず
7月9日、S&Pグローバル・レーティングは、事業リスクの高まりと資金フローの悪化を理由に、オラクルの格付けをBBB-に引き下げた。5
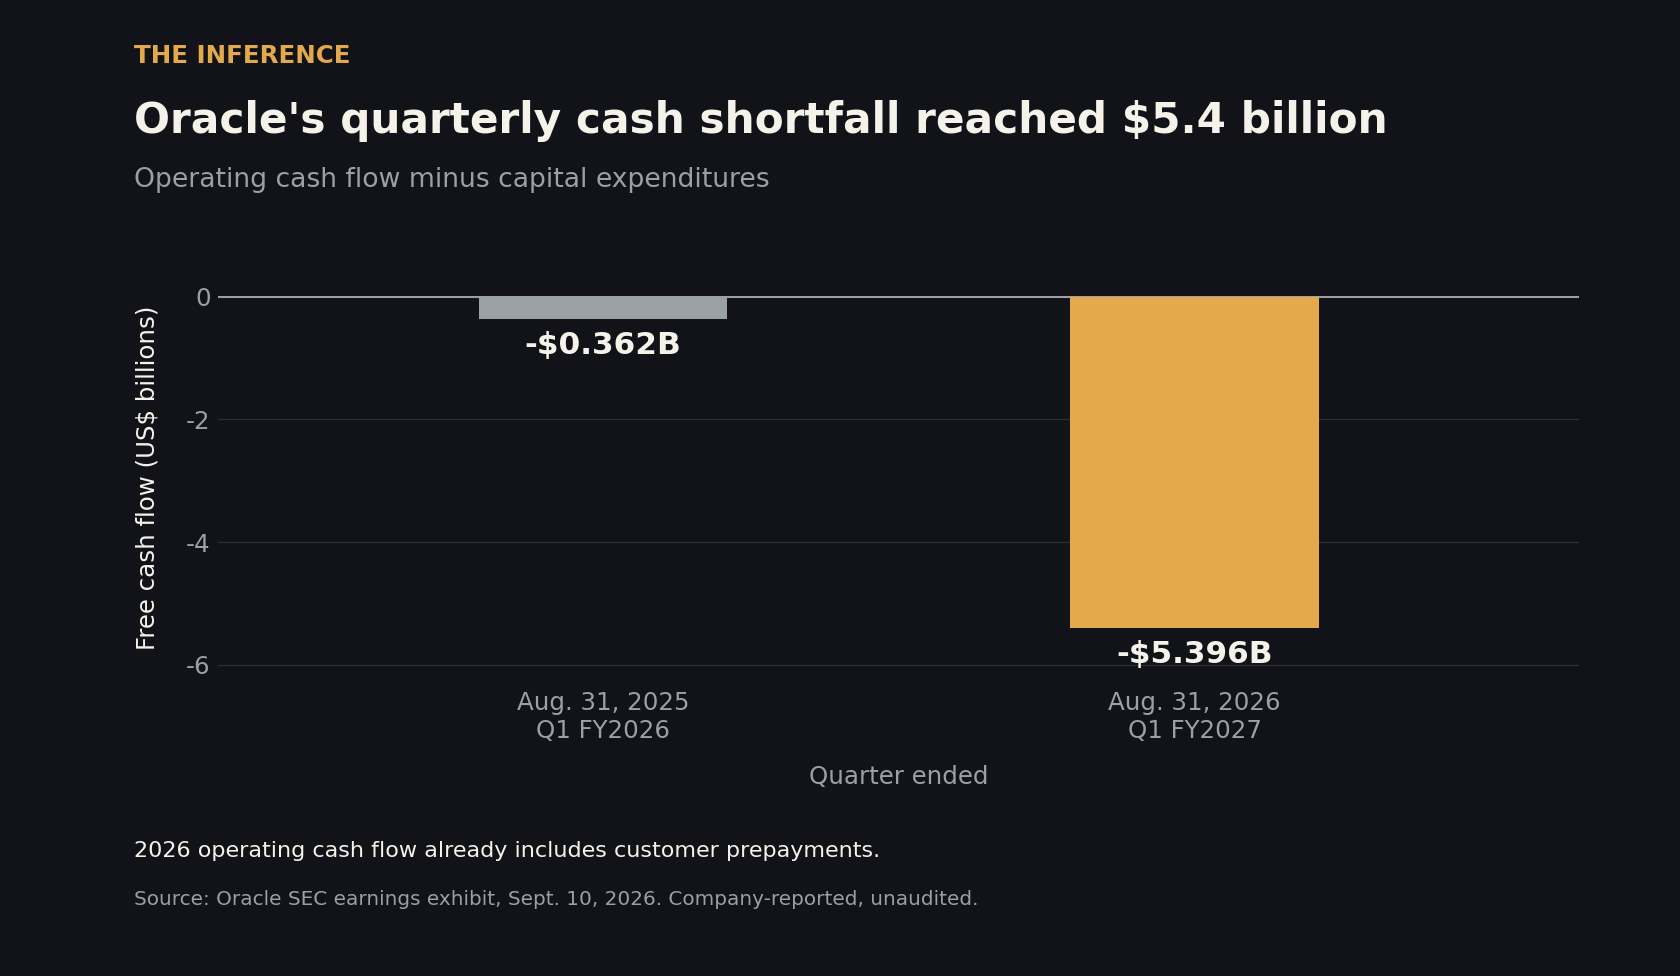
直近四半期の営業キャッシュフローは231億300万ドル、設備投資は284億9900万ドル。差引くと、フリーキャッシュフローはマイナス53億9600万ドルとなった。6
顧客前払いが資金調達を支援
四半期中の顧客前払い金は113億6000万ドル。この前払い金は営業キャッシュフローに計上済みだ。6,8
オラクルはGPU利用率97.9%も報告した。アナリストのレベッカ・ウェッテマン氏は、利用率の高さが契約ベースの売上認識への移行を示すと指摘。資金不足額は予想を下回り、会計上は黒字を確保した。4,8,9,10
ただ、これらの数字は、拡大された再編計画が最終なのかどうかを従業員に示していない。
次の予測に注目
10月28日の投資家会合では、フリーキャッシュフローのプラス転換と再編コストの残存に注目だ。11 これは資金調達型の拡大が最終的に直面する問いである。
従業員を抱えることが高コストでなくなる時、好況は労働者にも届く。
How this brief was made
01Gathered & sourced312 channels · 1,536 articles▾
Agents swept 312 channels and ingested 1,536 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated11 claims · 20 data feeds▾
Every one of 11 load-bearing claims was checked against primary sources, with 20 live data feeds reconciling the figures and charts.
- 1MT Newswires on margin pressure and Maxson's explanation, Sep 11 2026 (single-source relay of a Morgan Stanley note; 61% vs 68.7% is an adjusted, not GAAP, gross margin).
- 2SEC Form 10-Q for the quarter ended Aug 31 2026, filed Sep 11 (primary record: roughly $700M added after Aug 31 to a plan previously estimated at up to $2.1B; projected costs remain management estimates).
- 3Bloomberg on the expanded restructuring plan, Sep 11 2026 (company-reported: ~$2.8B expected cost, mainly severance; 49,000 U.S. and 92,000 international staff at May-end, down 21,000 year over year; no new layoff count given).
- 4CNBC on first-quarter earnings, Sep 10 2026 (company-claimed and unaudited; the category is infrastructure revenue, not a separately disclosed AI line).
- 5S&P Global Ratings downgrade to BBB-, Jul 9 2026 (primary rating action with a stable outlook; a rating is not an assertion of insolvency).
- 6SEC earnings exhibit 99.1, furnished Sep 10 2026 (company-claimed, unaudited: operating cash flow $23,103M, capex $28,499M, FCF -$5,396M; prior-year $8,140M, $8,502M, -$362M. Operating cash already includes customer prepayments).
- 7Axios on the cash-flow comparison, Sep 11 2026 (independent corroboration of the prior-year $362M deficit; its own chart is not reproduced).
- 8Reuters on results and customer prepayments, Sep 10 2026 (company-claimed: $11.36B prepaid, $19.3B revenue up 30%; includes a finance-chief briefing and analyst reaction).
- 9Zacks Equity Research on capacity and utilization, Sep 11 2026 (97.9% GPU utilization is management's metric from earnings-call coverage, not an independent inspection).
- 10SiliconANGLE on cloud growth, Sep 10 2026 (single-source interpretation: Rebecca Wettemann on backlog conversion, from an original interview).
- 11The Next Web on financing and the October investor meeting, Sep 11 2026 (single-source scheduling detail: the October 28 date is reported by one outlet and worth reconfirming).
03Reviewed & edited1 human editor▾
One editor read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.