CoreWeave Mortgages the Future. Its Founders Take Cash.
A $104 billion backlog proves customers want the compute. Interest already equals a quarter of sales, and CoreWeave's newest loan runs about two years past the average contract behind it.
 Vincent Jiang · 4 min read
Michael Intrator sold approximately $25.1 million of CoreWeave−9.27% — CoreWeave, down 9.27 percent today shares on September 1 through personal and LLC holdings. The sales followed a November 2025 trading plan; he still holds substantial stock.1 His liquidity is real. So is his remaining exposure.
For public shareholders, the excitement is a September 9 forecast: CoreWeave's backlog could exceed $150 billion before 2028.2 That forecast could come true while the stock disappoints. A customer ordering more compute has not promised you a good return.
The backlog and the bill
CoreWeave rents the computing infrastructure AI companies need. Its June backlog was $104.2 billion, according to its August earnings presentation.3 Earning that revenue requires delivering the capacity and meeting service requirements. The equipment, power and financing have to be paid for along the way.
This is where backlog worship gets expensive.
In Q2, CoreWeave reported $2.575 billion of revenue and $640 million of net interest expense. Interest alone equaled about 25% of sales. The company finished the quarter with a $626 million net loss.5 These are unaudited results; the percentage is calculated.
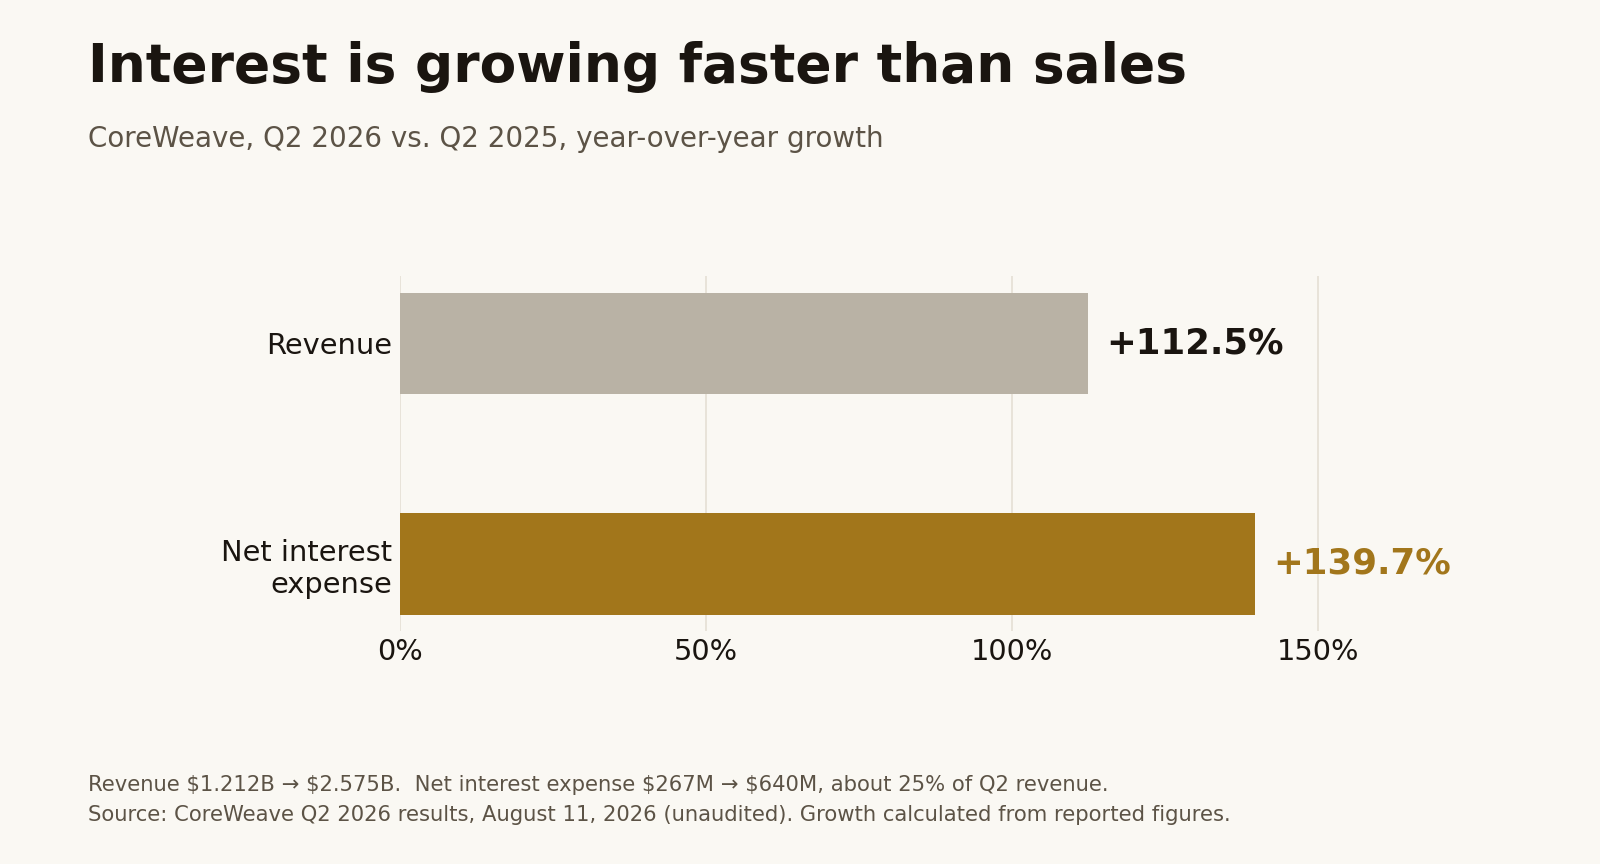
CoreWeave's customers can get their GPUs, its lenders can collect interest, and its shareholders can still lose money.
A loan that outlasts its contracts
The more revealing announcement came August 10. CoreWeave closed a $2.6 billion loan facility with an approximately five-year maturity. Its underlying customer contracts average three years.6 Earlier facilities had customer contracts extending through debt maturity. This one stretches beyond the average initial customer commitment.
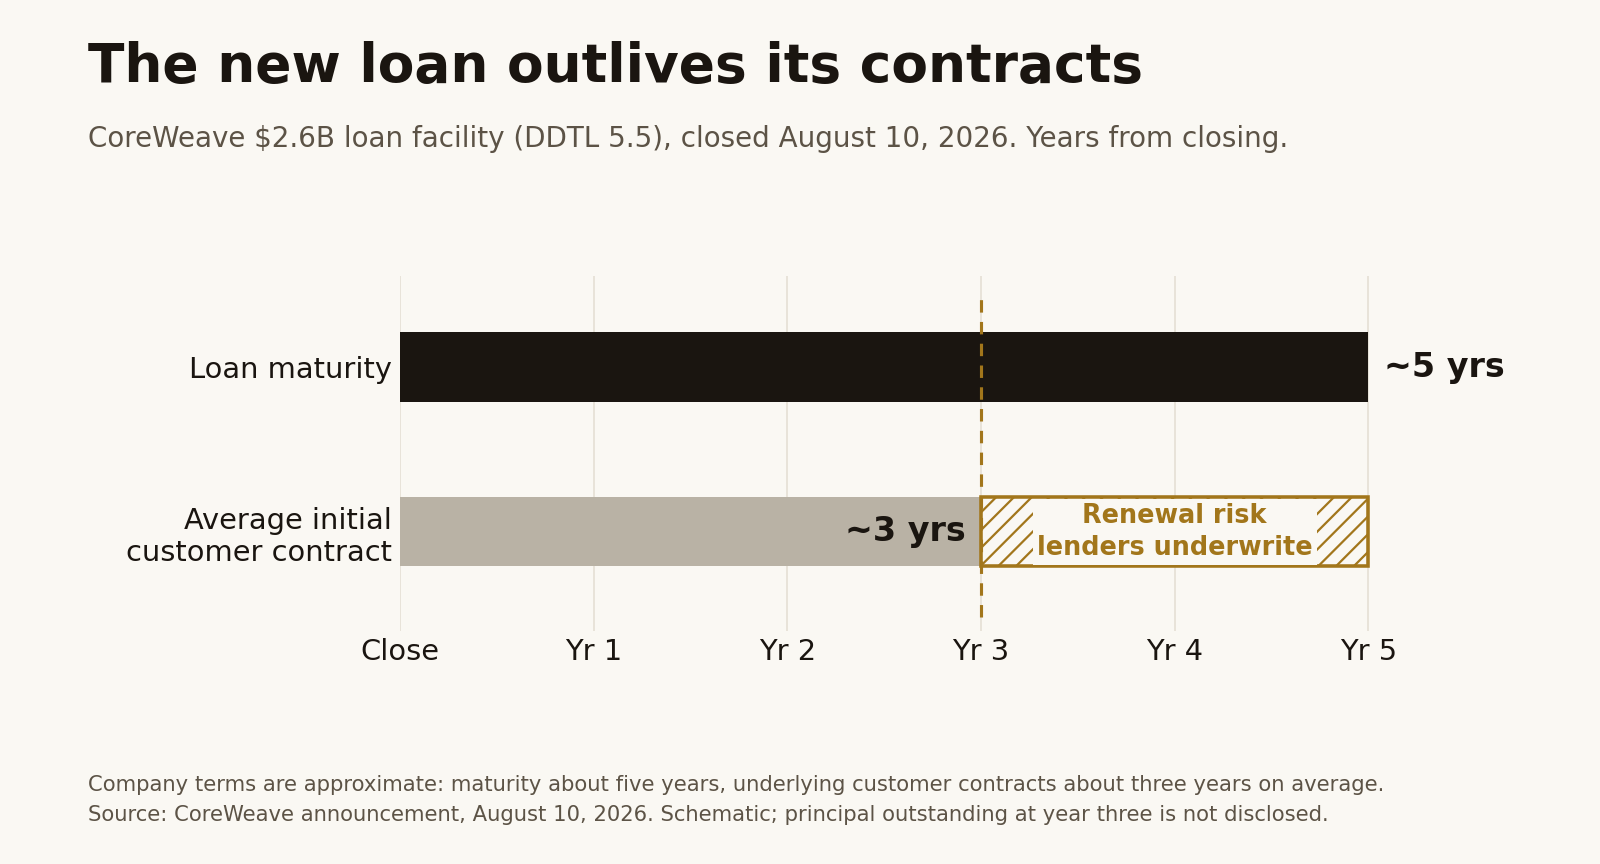
Co-founder Brannin McBee called the financing a “major unlock.” The company explicitly says lenders are willing to underwrite renewal risk.6 Shorter contracts can command higher prices and attract more customers. That flexibility has value. It also makes the economics after the first contract expires part of the underwriting.
How much principal will remain at that point? The announcement does not establish it. That is the number investors need before declaring the structure safe or doomed.
The parent is still on the hook
Subsidiaries do not automatically insulate the parent, either. Before this new facility, approximately 90% of June's reported debt carrying value was classified as recourse: direct parent obligations or obligations unconditionally guaranteed by the parent.4
Data
| Value | |
|---|---|
| Recourse | $31.4B |
| Non-recourse | $3.7B |
The bull case, and what it leaves out
The strongest bull argument is that the machines earn enough to justify the borrowing. CFO Nitin Agrawal says a typical five-year contract delivers attractive returns while fully repaying the asset-level debt used to fund it. He also reported an A100 contract extending into 2029.11 Older chips can keep working after newer chips arrive.
There is physical evidence behind the growth: Core Scientific−8.50% — Core Scientific, down 8.50 percent today reported approximately 395 MW of CoreWeave-related capacity had begun billing by June 30.12 CoreWeave also generated positive operating cash flow in the first half while investing heavily.4 Expansion can consume cash before it produces returns.
But a profitable original contract and an attractive public stock remain separate achievements. Shareholder returns depend on the cash remaining after debt service and necessary reinvestment.
What to ask at the next earnings call
At the next earnings call, Intrator should show what mature deployments have earned after financing, how much of their debt they have repaid, and what remains at renewal. Another giant booking would demonstrate demand again.
Ask him about the contracts already delivered.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.