甲骨文营收大涨,裁员预算同步加码
基础设施收入增长超过一倍,甲骨文却仍在扩大重组计划,而这项计划的支出大部分是遣散费。
 Vincent Jiang · 2 min read
业绩说辞话音刚落,签字随之而来
9月10日,甲骨文首席财务官希拉里·马克森(Hilary Maxson)表示,降本增效保住了公司的利润率。1
一天后,这位首席财务官便签署文件,披露公司重组计划将新增约7亿美元支出。2
遣散预算再加码
至此,重组计划的预计成本升至约28亿美元,其中大部分为遣散费。新增金额对应更多已列入计划的举措;甲骨文未披露新的裁员人数。2,3
截至5月31日,甲骨文员工总数已比一年前减少约2.1万人。这是历史累计的净减员,并非周五那轮裁员的人数。3
业绩向好,员工照样承压
销售引擎运转良好。截至8月31日的季度,基础设施收入同比增长121%,达到74亿美元;总营收增长30%,至193亿美元。4,8
但基础设施业务改变了盈利逻辑。调整后毛利率从一年前的68.7%降至61%。马克森表示,运营成本下降有助于抵消这一压力。1
本文的推断是:旺盛的需求与压缩人力成本的压力可以并存。当扩张中的业务消耗更多资本时,单靠营收增长给不了员工多少保护——无论业绩电话会就这轮裁员讲出怎样的故事。
现金依然入不敷出
7月9日,标普全球评级将甲骨文评级下调至BBB-,理由是业务风险加大、现金流走弱。5
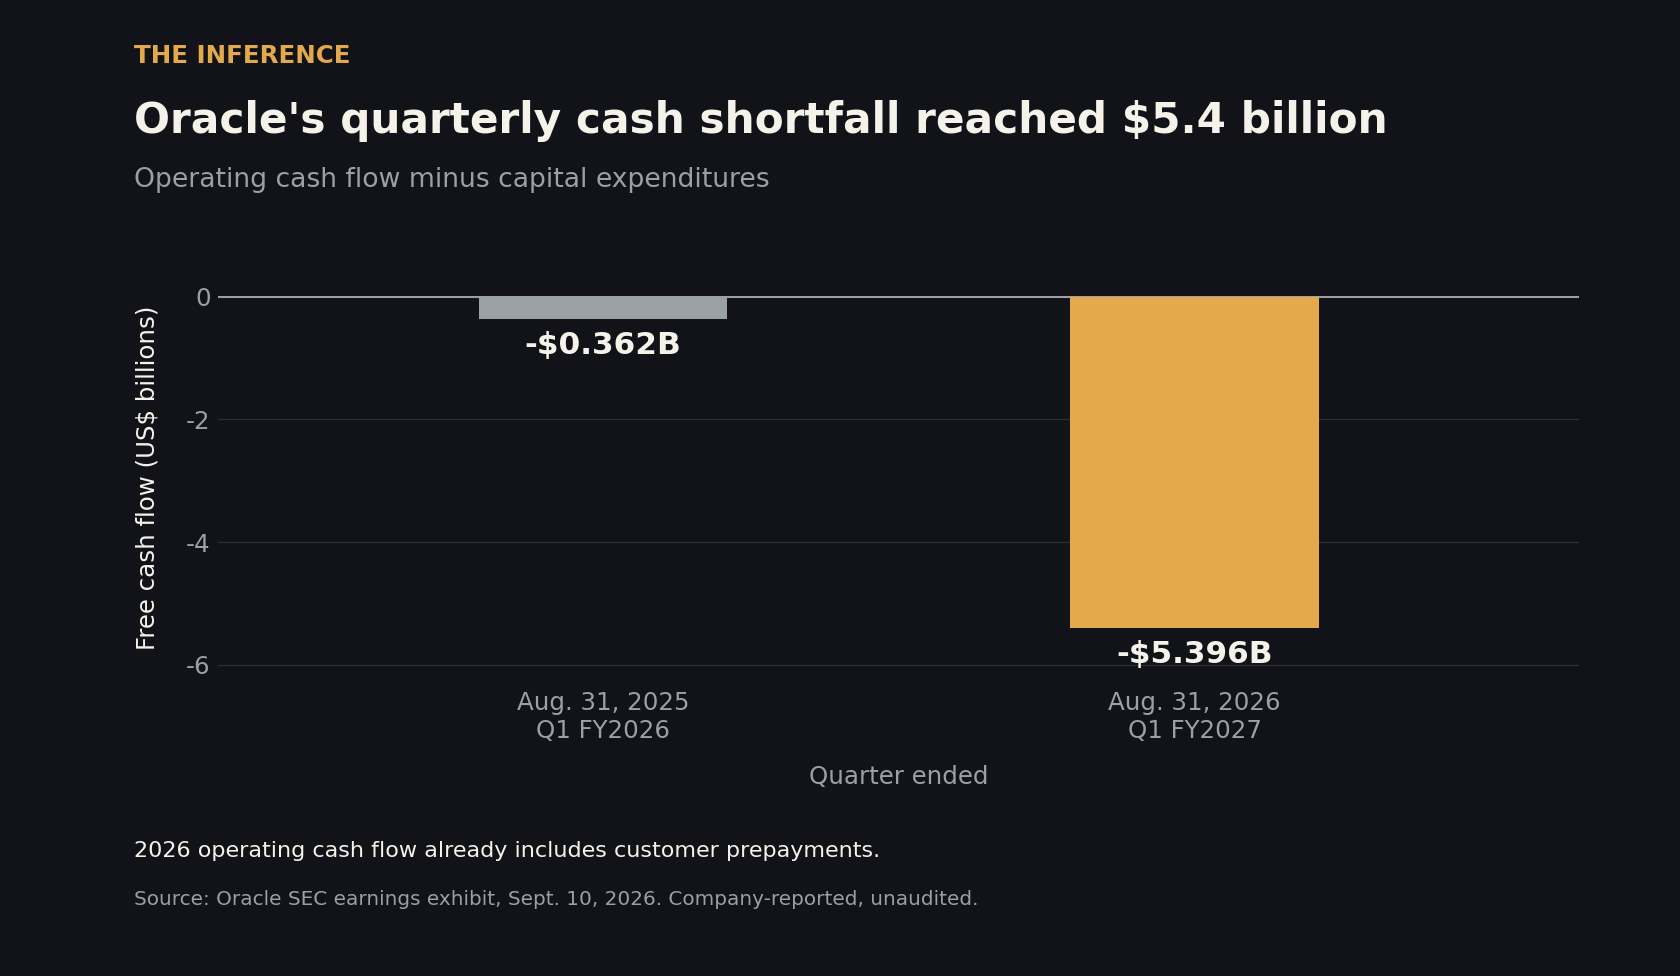
最新季度,经营活动产生现金231.03亿美元,资本支出消耗284.99亿美元。两者相减:自由现金流为负53.96亿美元。6
客户也在出资
本季度,客户预付了113.6亿美元;这些预付款已计入经营现金流。6,8
甲骨文还披露GPU利用率达到97.9%。分析师丽贝卡·韦特曼(Rebecca Wettemann)表示,这一利用率说明已签约业务正在转化为确认收入。现金缺口小于分析师预期,甲骨文按会计口径也仍然盈利。4,8,9,10
尽管如此,这些数字仍无法告诉员工,扩大后的重组计划会不会是最后一轮。
让下一次预测真正算数
在10月28日的投资者会议上,值得重点关注的是:通往正自由现金流的更清晰路径,以及剩余的重组成本还有多少。11 这是每一个靠融资推进的扩建项目最终都要回答的问题。
只有当留住员工不再显得是更贵的选项时,繁荣才会真正惠及员工。
How this brief was made
01Gathered & sourced312 channels · 1,536 articles▾
Agents swept 312 channels and ingested 1,536 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated11 claims · 20 data feeds▾
Every one of 11 load-bearing claims was checked against primary sources, with 20 live data feeds reconciling the figures and charts.
- 1MT Newswires on margin pressure and Maxson's explanation, Sep 11 2026 (single-source relay of a Morgan Stanley note; 61% vs 68.7% is an adjusted, not GAAP, gross margin).
- 2SEC Form 10-Q for the quarter ended Aug 31 2026, filed Sep 11 (primary record: roughly $700M added after Aug 31 to a plan previously estimated at up to $2.1B; projected costs remain management estimates).
- 3Bloomberg on the expanded restructuring plan, Sep 11 2026 (company-reported: ~$2.8B expected cost, mainly severance; 49,000 U.S. and 92,000 international staff at May-end, down 21,000 year over year; no new layoff count given).
- 4CNBC on first-quarter earnings, Sep 10 2026 (company-claimed and unaudited; the category is infrastructure revenue, not a separately disclosed AI line).
- 5S&P Global Ratings downgrade to BBB-, Jul 9 2026 (primary rating action with a stable outlook; a rating is not an assertion of insolvency).
- 6SEC earnings exhibit 99.1, furnished Sep 10 2026 (company-claimed, unaudited: operating cash flow $23,103M, capex $28,499M, FCF -$5,396M; prior-year $8,140M, $8,502M, -$362M. Operating cash already includes customer prepayments).
- 7Axios on the cash-flow comparison, Sep 11 2026 (independent corroboration of the prior-year $362M deficit; its own chart is not reproduced).
- 8Reuters on results and customer prepayments, Sep 10 2026 (company-claimed: $11.36B prepaid, $19.3B revenue up 30%; includes a finance-chief briefing and analyst reaction).
- 9Zacks Equity Research on capacity and utilization, Sep 11 2026 (97.9% GPU utilization is management's metric from earnings-call coverage, not an independent inspection).
- 10SiliconANGLE on cloud growth, Sep 10 2026 (single-source interpretation: Rebecca Wettemann on backlog conversion, from an original interview).
- 11The Next Web on financing and the October investor meeting, Sep 11 2026 (single-source scheduling detail: the October 28 date is reported by one outlet and worth reconfirming).
03Reviewed & edited1 human editor▾
One editor read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.