Regal Rexnord is 37% off its high as record credit spreads on Oracle and CoreWeave test its Nov. 3 orders
Regal Rexnord closed October 14 at $157.06, 37% below its 52-week high, as record default-insurance costs on Oracle and CoreWeave raised the question of whether AI data-center building keeps getting funded. The same analysts cutting targets still say buy, and the November 3 order book votes first.
 Vincent Jiang · 2 min read
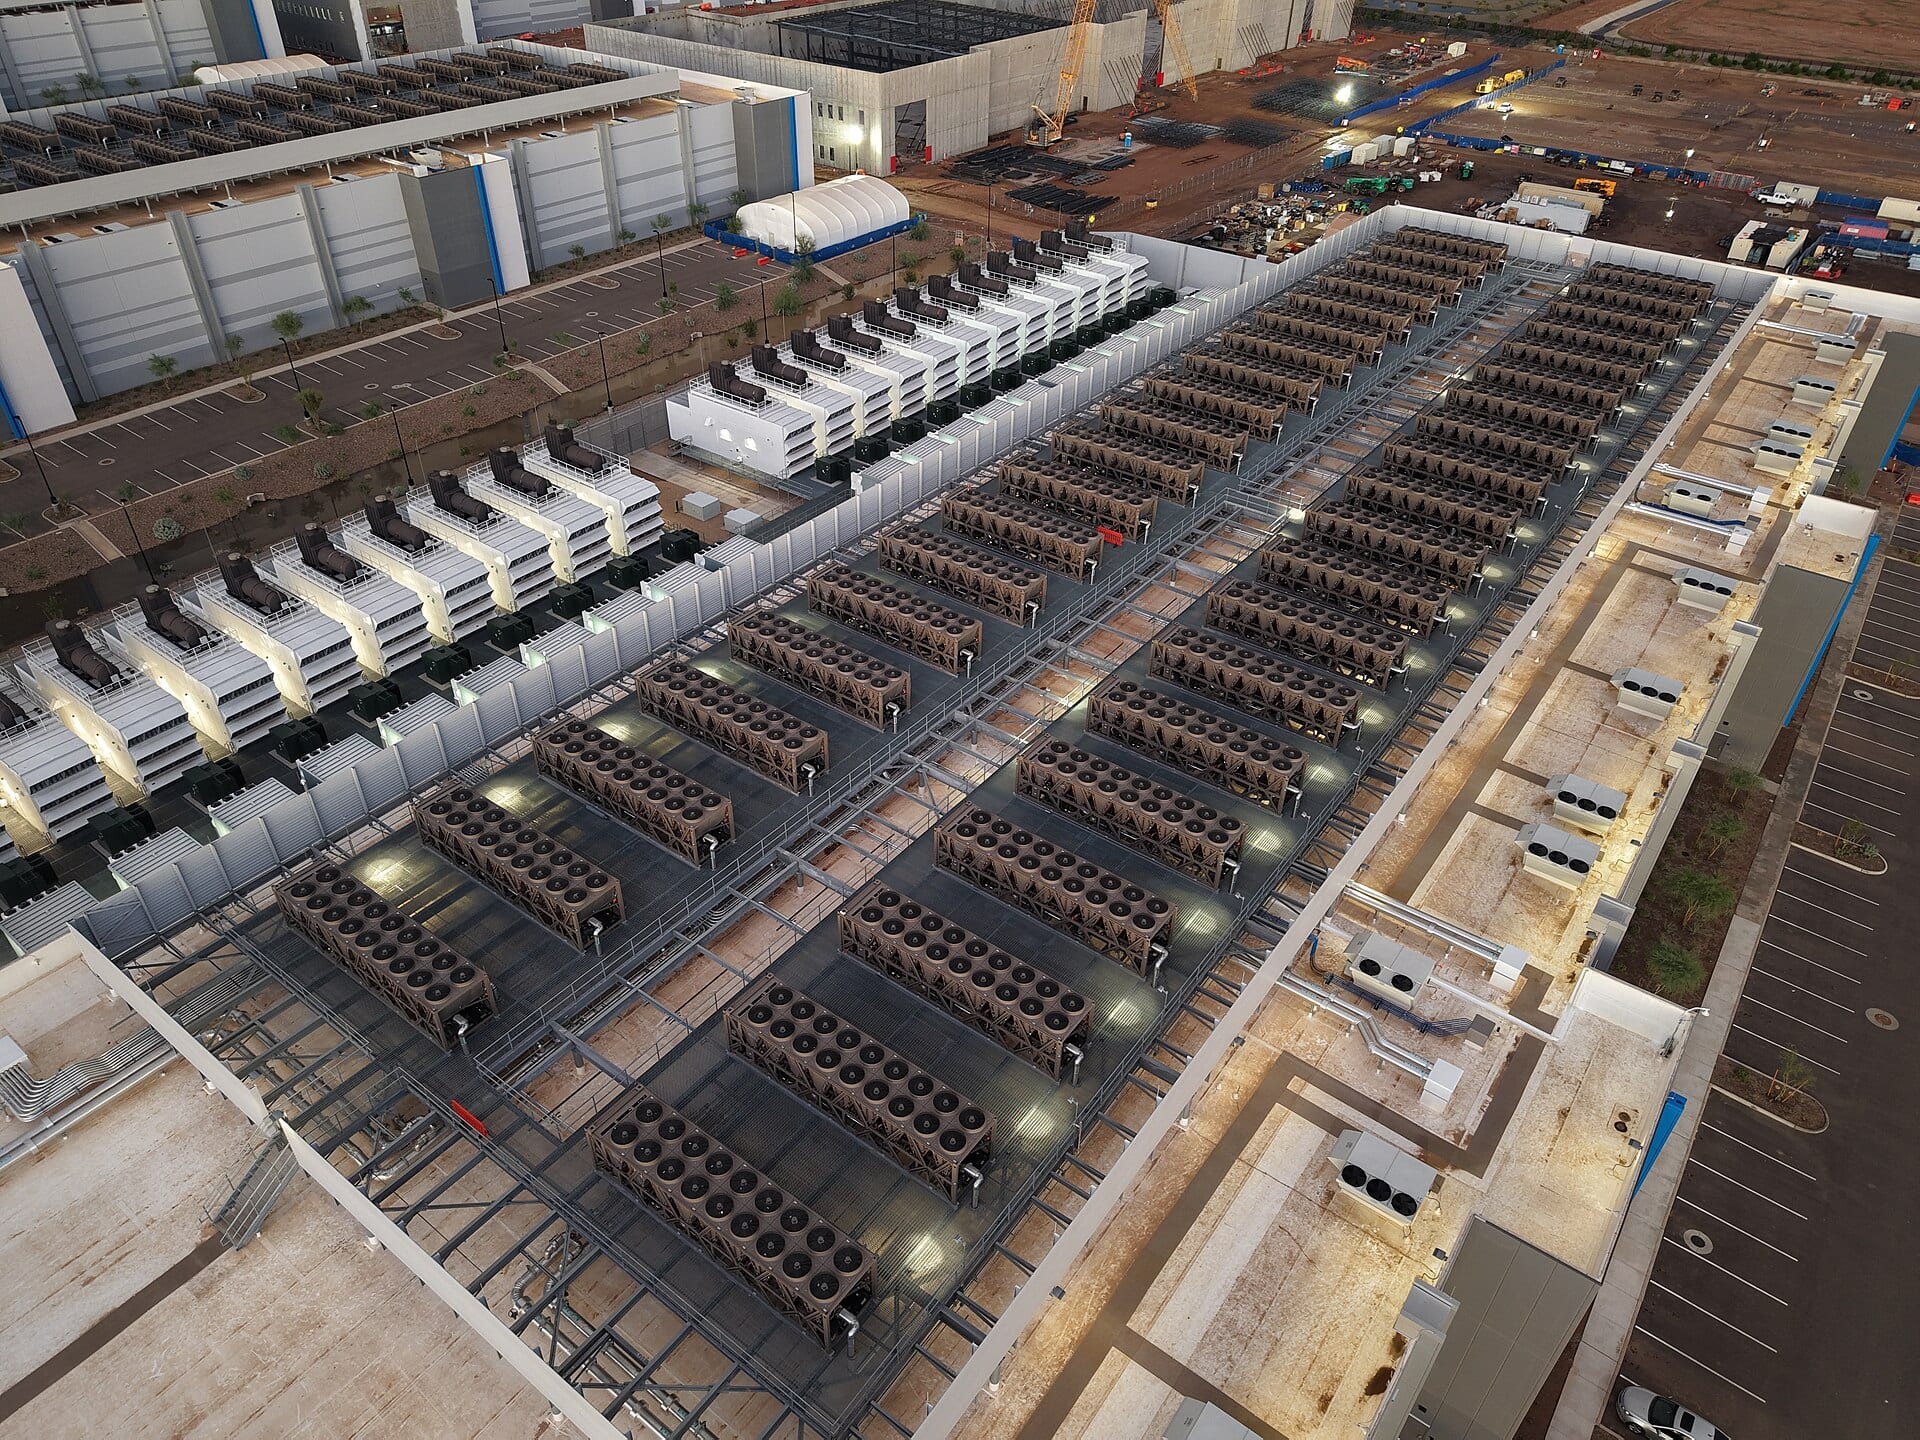
Credit markets put a price on doubt this week. Reuters reported on October 15 that five-year default insurance on Oracle+2.08% — Oracle, up 2.08 percent today widened overnight to a record 288 basis points, SoftBank moved to 424, and data center operator CoreWeave+3.04% — CoreWeave, up 3.04 percent today blew out past 1,000 bps, its 2032 bonds changing hands at 77 cents on the dollar against nearly $50 billion owed 1. That is the bond market asking how the AI building boom gets funded. Regal Rexnord−0.59% — Regal Rexnord, down 0.59 percent today, the Milwaukee maker of the motors, fans and precision motion parts inside those data centers, is paid only if it does.
Default insurance on CoreWeave blew past 1,000 bps as Oracle hit a record 288
Data
| Value | |
|---|---|
| CoreWeave | 1,000 bps |
| SoftBank | 424 bps |
| Oracle | 288 bps |
The cuts took targets down, not the buy ratings
RRX closed October 14 at $157.06, down 3.8% and roughly 37% below its 52-week high of $247.80 2. Two cuts landed in two days: Oppenheimer moved its target from $245 to $200 on October 8 while keeping Outperform 3, and JPMorgan moved from $240 to $196 on October 9 while keeping Overweight 4. Neither cut carried the rating to sell. The one rating change in that stretch went away from buy instead: Wall Street Zen downgraded its call on RRX to Hold on October 3 4.
Twelve of thirteen analysts still say buy
FactSet+4.17% — FactSet, up 4.17 percent today counts 13 covering analysts at 12 Buys and one Hold, average target $231.10, about 40% above the October 9 close 5. MarketBeat's tracker shows eight Buys and three Holds at a $235.50 average, so the counts differ by tracker 4. Their case is the quarter: Q2 revenue of $1.56 billion, up 4.2% year over year, adjusted EPS of $2.99 against $2.58 expected, and orders lifted by data center, commercial HVAC and discrete automation demand 46. After four quarters of shrinking sales, growth turned positive in late 2025 and has held since 8.
Revenue growth turned positive in late 2025 and has held since
Data
| Revenue growth, year over year | |
|---|---|
| Q3 '24 | -10.4% |
| Q4 '24 | -9.1% |
| Q1 '25 | -8.4% |
| Q2 '25 | -3.3% |
| Q3 '25 | 1.3% |
| Q4 '25 | 4.3% |
| Q1 '26 | 4.3% |
| Q2 '26 | 4.2% |
Guidance of $10.35 to $10.85 in adjusted EPS holds the line 4, but it leans on tariff refunds to protect margins 6, and insiders have sold $27.7 million of stock in the past year with no buying 2.
The order book settles it
Credit markets question whether the money arrives; equity analysts have bet that it already has. RRX's order book sits between them. Q3 results land before the market opens on November 3, the first reported orders since the credit scare began 7. Two numbers decide which camp wins the next round: whether reported orders hold the data-center-driven growth of Q2, and whether margins hold without leaning harder on tariff refunds.
Every target cut left buy ratings well above the broken stock
Data
| Value | |
|---|---|
| JPMorgan (Oct 9) | $196 |
| Oppenheimer (Oct 8) | $200 |
| FactSet consensus | $231.1 |
Deepdive
AI-generated from this story and its cited sources. Not investment advice.