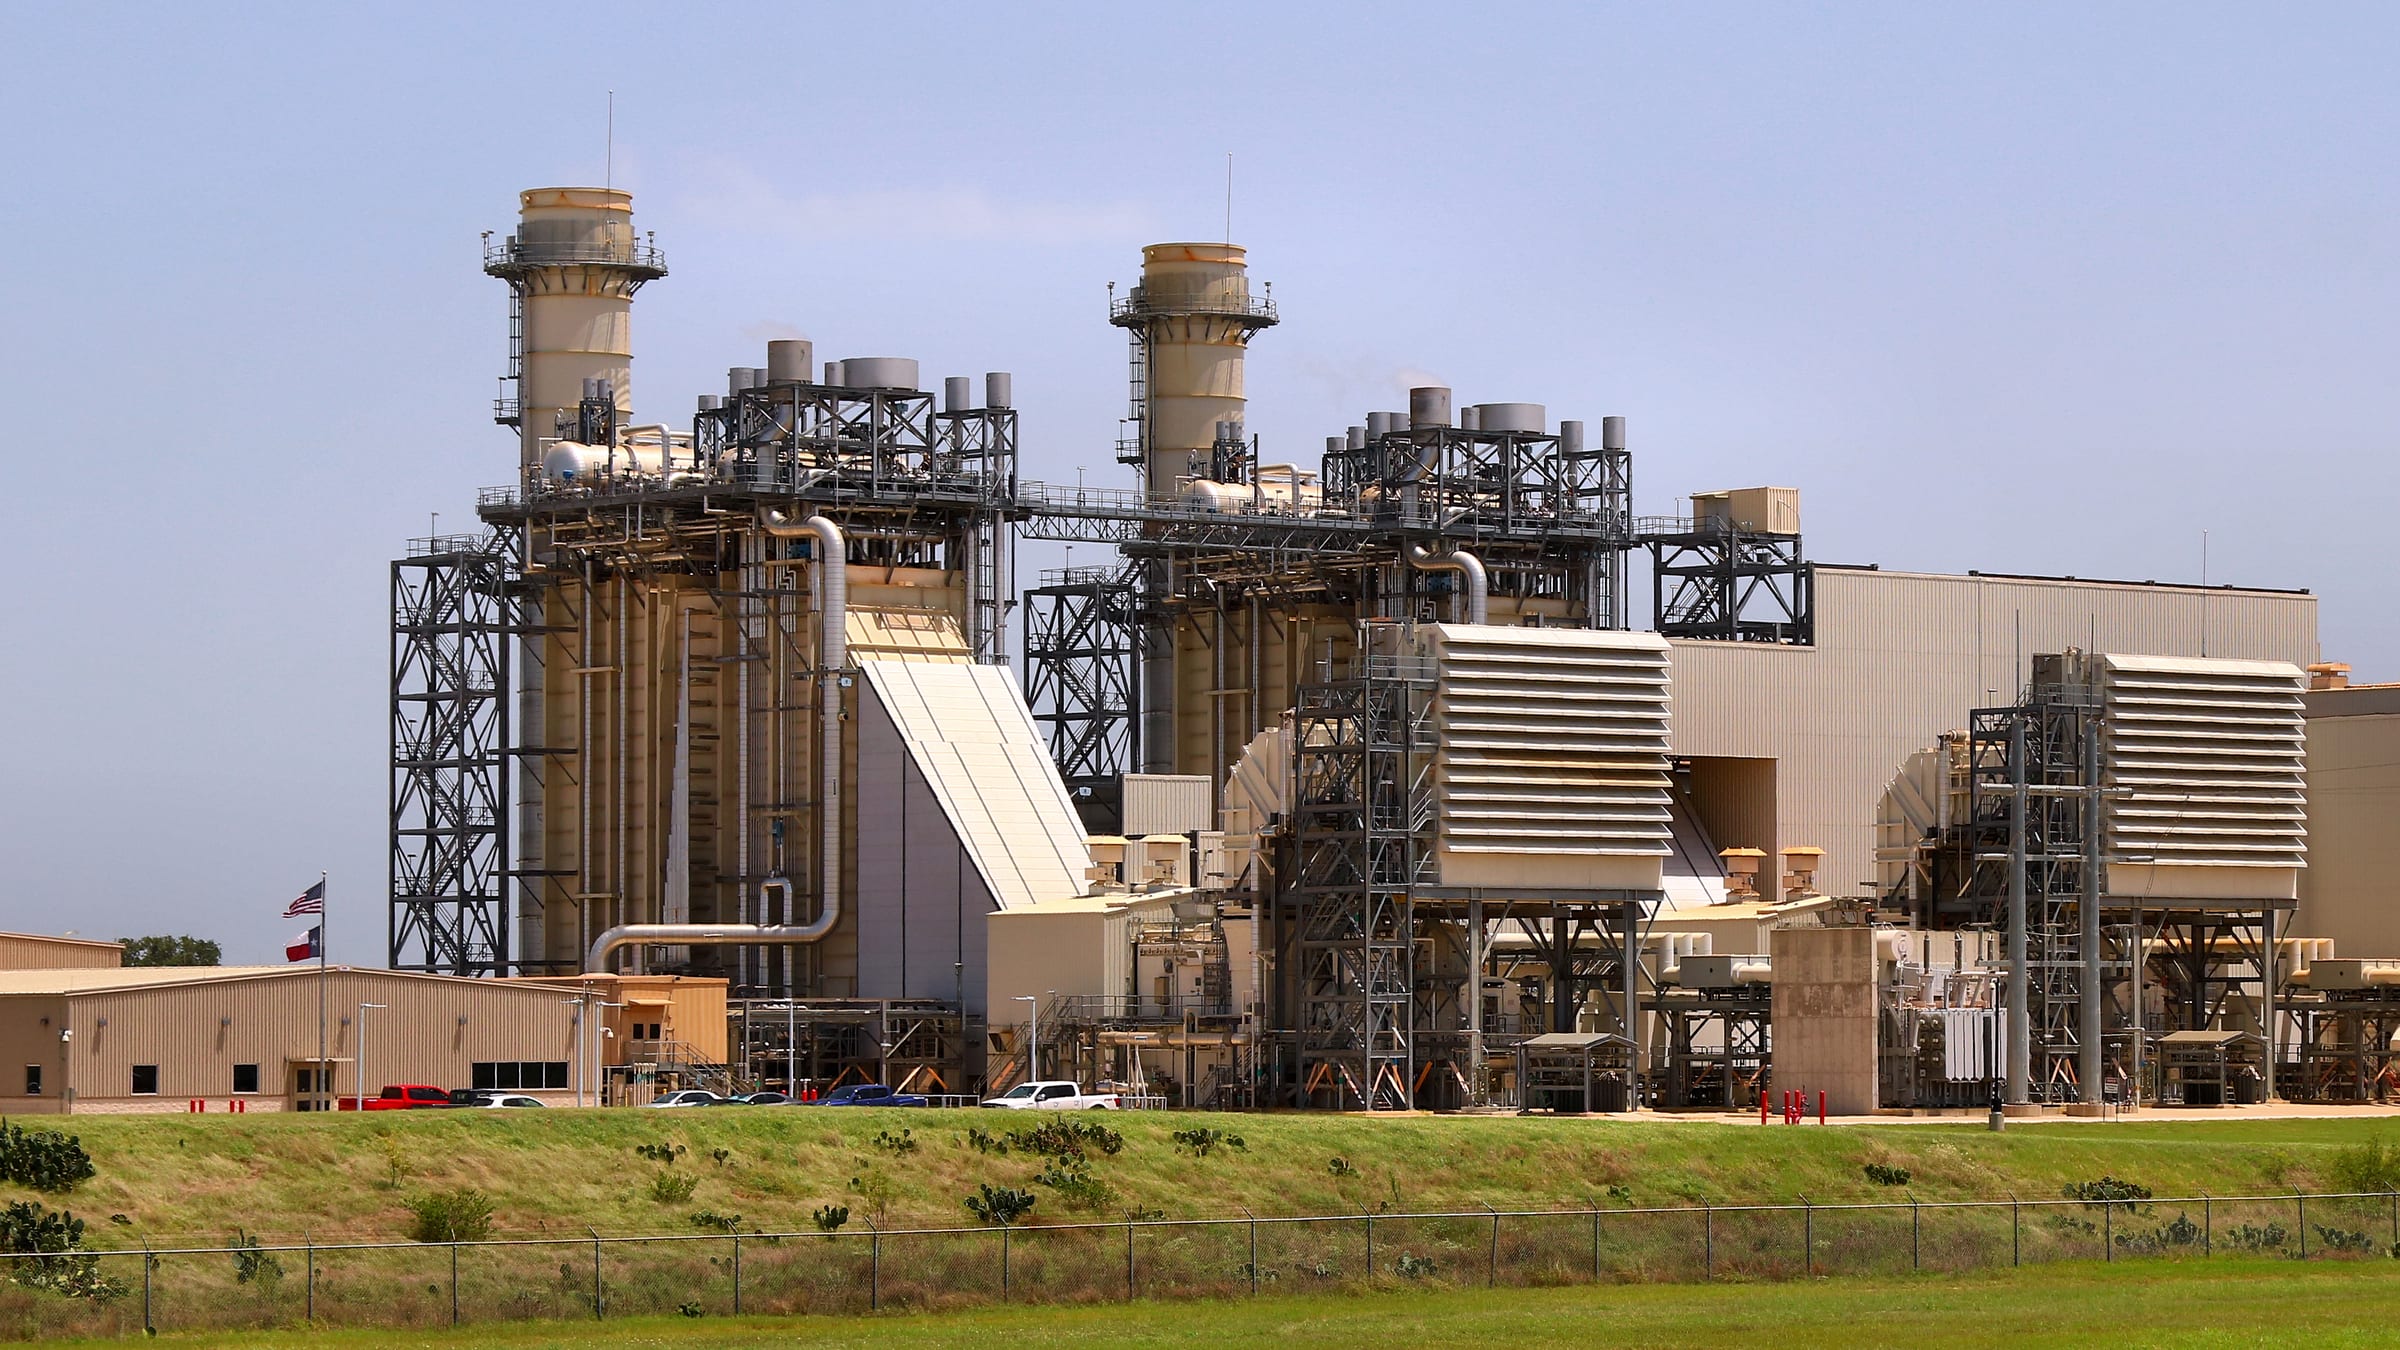
SemiAnalysis calls IREN's old sites the industry's worst; the Street's median target is $80
SemiAnalysis's ClusterMAX 3.0 keeps IREN "not recommended" and names one site the worst in the industry by user report. Nine analysts carry an $80 median target, and $25 billion to $30 billion of FY27 capex rides on the new Texas builds outgrowing the old fleet.
 Vincent Jiang · 3 min read
Two verdicts landed on one Wednesday
On 23 September the industry's technical referee and a research bank published opposite verdicts on IREN. SemiAnalysis released ClusterMAX 3.0, its GPU-cloud rankings, built on in-depth testing of 77 of 323 tracked providers and more than 200 end-user interviews 1. Rothschild Redburn started the stock at Neutral the same day, with a $40 target, 17.6% below the prior close of $48.55 23.
IREN fell 3.6% the next day and another 4% to $44.09 on 25 September, while the Nasdaq-tracking QQQ rose 43. Northland's $99 Outperform initiation had landed five days before the rankings, on 18 September 5.
The referee's complaint is specific, and it is not Texas
ClusterMAX 3.0 keeps IREN in its bottom tier, "not recommended" 67. The record behind it is the old fleet: multi-day power outages, network upgrades, storage failures and link flaps at Prince George and Mackenzie in British Columbia, where B200 and B300 capacity sells at rock-bottom prices 8. One of those locations is "the number one worst site in the industry according to users" 8.
The advice is blunt: stop marketing managed clusters and inference endpoints and sell bare metal 8. The same report says the new Sweetwater builds in Texas "look much better" and expects Nvidia's $2.1 billion investment to buy fewer cut corners 8. Firmus, SemiAnalysis's favorite in Asia-Pacific, holds its third-best silver rating 6.
The bulls priced the signatures first
Northland opened at Outperform on 18 September with a $99 target, 128% above the prior close 5. B. Riley, at $96, counts three-year contract pricing up about 125% in recent months 5.
IREN claims $4 billion of contracted run-rate revenue tied to capacity due online by year-end, 85% of it signed when announced, though only about $1 billion was operating on 26 August 52. The median target across the nine analysts Quiver tracks is $80 4.
Nine targets from $40 to $99 while IREN trades at $44
Data
| Value | |
|---|---|
| Northland, 18 Sep | $99 |
| Cantor, 28 May | $99 |
| B. Riley, 4 Jun | $96 |
| Macquarie, 4 Jun | $90 |
| Jefferies, 18 Jun | $79 |
| Canaccord, 3 Jun | $79 |
| Freedom, 6 Jul | $58 |
| JPMorgan, 11 May | $46 |
| Redburn, 23 Sep | $40 |
A $25 billion to $30 billion bill against $14 billion in hand
The build needs $25 billion to $30 billion of FY27 capital expenditure against roughly $14 billion in hand across cash, prepayments and committed GPU financing 5. Management is seeking another $8 billion in GPU loans and prepayments, with data-center financing, operating cash flow, corporate debt or equity expected to provide the balance 5.
Sweetwater's 2GW hub won conditional ERCOT base-load inclusion on 8 September, grid capacity the chief executive calls the industry's scarcest input 10. The pivot still bleeds: FY26 closed with a $702.6 million net loss 5, and the June quarter spent $1.37 billion of capex against $95 million of revenue 9.
Quarterly capex now runs 14 times revenue
- Capex
- Revenue
Data
| Capex | Revenue | |
|---|---|---|
| Q1 '24 | $0.07B | $0.04B |
| Q2 '24 | $0.2B | $0.04B |
| Q3 '24 | $0.27B | $0.04B |
| Q4 '24 | $0.11B | $0.07B |
| Q1 '25 | $0.28B | $0.09B |
| Q2 '25 | $0.24B | $0.12B |
| Q3 '25 | $0.19B | $0.16B |
| Q4 '25 | $0.49B | $0.12B |
| Q1 '26 | $0.92B | $0.1B |
| Q2 '26 | $1.37B | $0.1B |
The cheapest neocloud per GW, and still a Neutral
Redburn scored IREN the most efficient operator in its coverage and valued it at $3.8 billion per GW, 60 to 70% below peers, and still declined the stock: its downside list runs tenant demand, financing costs and construction disruption 2.
If the referee is right, the prepay customers contracted onto the graded-worst legacy fleet and the lenders pricing the $8 billion raise sit closest to the loss. The bulls priced the signatures; the referee graded the clusters. What settles it is the dullest machinery in the plan: commissioning, testing and customer acceptance across 480 MW this year and 1.2 GW in 2027 25.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.