Snowflake's CFO calls forecasting CoCo 'somewhat reckless'; investors just paid 7.42% more anyway
Wall Street raised revenue estimates on Snowflake's AI agent while CFO Brian Robins says forecasting CoCo into guidance would be "somewhat reckless." Someone is wrong, and the December quarter will say who.
 Vincent Jiang · 2 min read
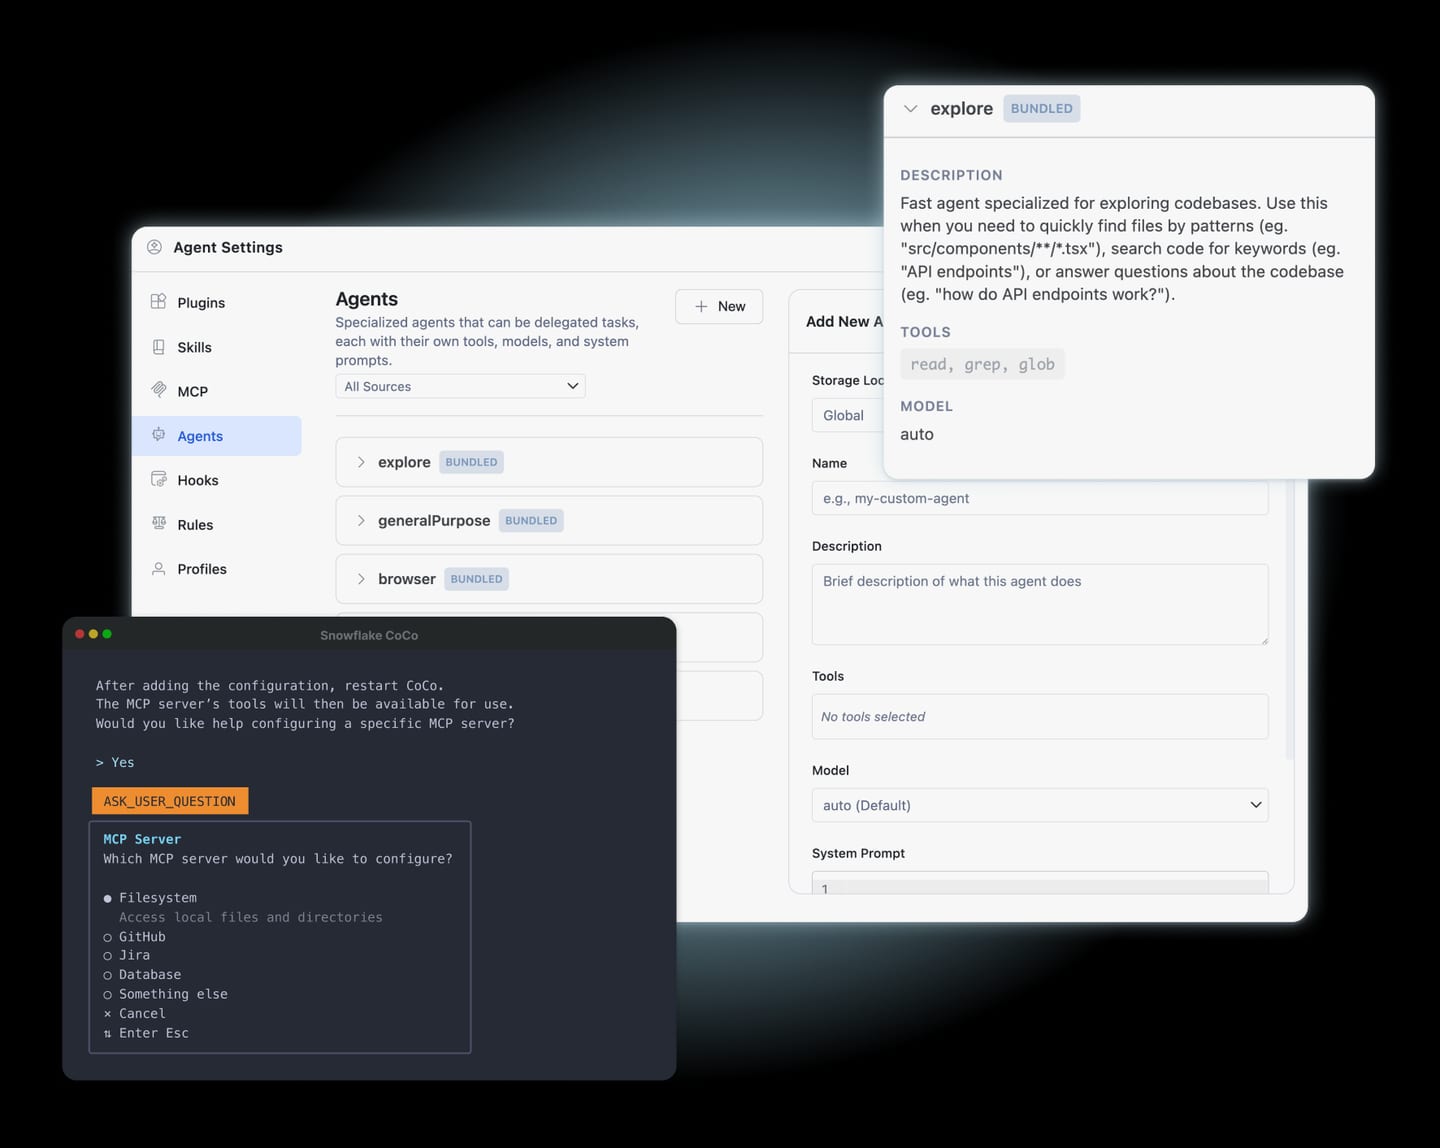
Snowflake+7.51% — Snowflake, up 7.51 percent today investors paid up 7.42% on October 9 for a product its own finance chief will not put in a forecast. The stock closed at $368.89 after the company released Agentic Marketplace Discovery in public preview, a tool that lets customers query Snowflake's AI agent CoCo to find and compare Marketplace listings 13. CoCo sits at the center of the bull case. It carries about 9,100 accounts as of the July quarter, up more than 2,000 in the quarter 1.
The bulls raised estimates. The CFO raised a red flag
Analysts have lifted revenue estimates after each of the last two reports: fiscal 2027 consensus is up about 7% since March 31, fiscal 2028 up about 10% 1. Robins wants no part of that compounding in guidance. At the Piper Sandler Growth Frontiers Conference on September 15 he called extracting the CoCo forecast into guidance "somewhat... reckless," saying Snowflake applies a haircut because "we have 2 quarters' worth of data. So we're getting closer to what that number is" 1. Snowflake's top 10 CoCo skills even include a cost optimizer that shrinks customer bills 1.
What actually lands in the bank
July-quarter free cash flow of $83.80 million missed the $107.27 million estimate by 21.87%, the third miss in five quarters, on a GAAP loss of $0.55 per share 1. SEC filings show revenue accelerating to 35.1% growth in the July quarter while free cash flow ran $84 million against $1.55 billion of revenue 4. That gap is what 146x NTM normalized P/E and 18x EV/NTM revenue must eventually cover 1. September's $3.75 billion of 0% convertible notes adds dilution risk 1.
Revenue compounds every quarter, free cash flow stays thin
- Revenue
- Free cash flow
Data
| Revenue | Free cash flow | |
|---|---|---|
| Q3'24 | 0.94 | 0.08 |
| Q4'24 | 0.99 | 0.42 |
| Q1'25 | 1.04 | 0.18 |
| Q2'25 | 1.15 | 0.06 |
| Q3'25 | 1.21 | 0.11 |
| Q4'25 | 1.28 | 0.77 |
| Q1'26 | 1.39 | 0.23 |
| Q2'26 | 1.55 | 0.08 |
Migrations took 10 or 11 months. With CoCo, about 6
The core is real: migrations that took 10 or 11 months now take about 6 with CoCo agents, and Snowflake has canceled its own BI and analytics contracts in favor of CoCo dashboards 1. Analysts rate it 36 Buy, 9 Outperform, 5 Hold, 1 Underperform, 1 Sell 1. The bears' strongest argument is behavioral: the CFO knows more about the bookings than the buyers, and he is the one discounting.
45 of 52 analysts rate Snowflake Buy or better
- Buy3669.3%
- Outperform917.3%
- Hold59.6%
- Underperform11.9%
- Sell11.9%
Data
| Slice | Value | Share |
|---|---|---|
| Buy | 36 | 69.3% |
| Outperform | 9 | 17.3% |
| Hold | 5 | 9.6% |
| Underperform | 1 | 1.9% |
| Sell | 1 | 1.9% |
December 2 will say who was wrong
October-quarter results are expected around December 2, with analysts modeling about 36% revenue growth 1. If CoCo adds another 2,000-plus accounts and growth beats that line, the haircut was too deep. A smaller gain means management was right and 146x has nowhere to hide. Count the accounts, not the preview.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.