Two downgrades in two days: Nova's record AI ramp beats on revenue, loses on cash
Nova guided to another record quarter after beating on revenue, but first-half free cash flow fell 27% and GAAP EPS rose 1.7%. Zacks and Citigroup cut the stock this week; the AI thesis now gets decided by collections, not bookings.
 Vincent Jiang · 2 min read
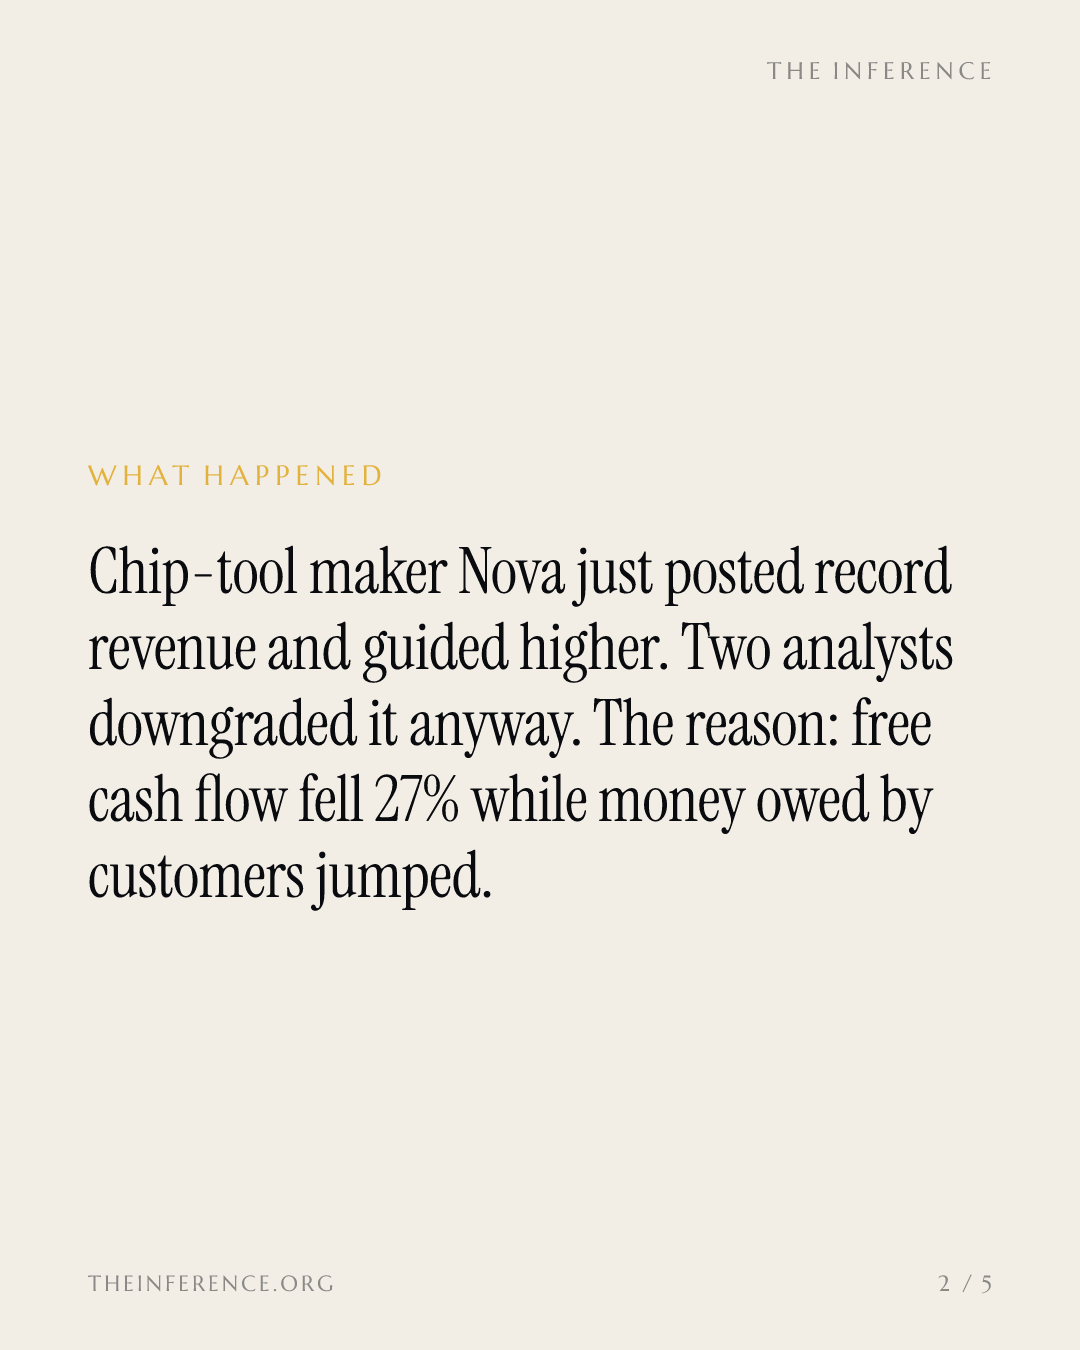
Zacks cut Nova from strong buy to hold in a report published Monday, October 5 1; the stock closed down 4.2% at $377.77 on the 7th 2. Citigroup followed on the 8th, to neutral with a $415 target, and the shares finished at $354.59, down 6.1% 3. Both cuts landed after a record quarter: revenue of $254.96 million, up 15.9%, beat the $250.33 million consensus, and third-quarter guidance of $277–287 million implies about 25.6% growth at the midpoint 14.
The ramp is real, the cash is late
First-half revenue rose 13.1% and operating profit 14.1%, but diluted GAAP EPS rose 1.7% and free cash flow fell 27.4% to $74.5 million 5. Receivables ended June at $210.3 million, up 38.4% from December, after absorbing $59.4 million of cash while deferred revenue fell from $67.2 million to $45.9 million 5. Deposits fell and invoices stretched: in effect, Nova is financing its customers' AI buildout from its own balance sheet 5. At a September conference, management said deposit arrangements and payment terms are unchanged, and that 2026 spending sits in existing logic nodes, DRAM capacity and NAND upgrades, mix that buys less metrology than new architectures 5. The chief executive made the same point in August: NAND growth this year is upgrades, not capacity 4.
Revenue sets records while free cash flow runs a third below its Q1 2025 peak
- Revenue
- Free cash flow
Data
| Revenue | Free cash flow | |
|---|---|---|
| Q3 '23 | $128.81M | $43.13M |
| Q4 '23 | $134.22M | $22M |
| Q1 '24 | $141.8M | $56.67M |
| Q2 '24 | $156.86M | $57.92M |
| Q3 '24 | $178.97M | $43.06M |
| Q4 '24 | $194.77M | $60.4M |
| Q1 '25 | $213.36M | $59.69M |
| Q2 '25 | $219.99M | $42.92M |
| Q3 '25 | $224.61M | $66.94M |
| Q4 '25 | $222.62M | $48.36M |
| Q1 '26 | $235.31M | $36.03M |
| Q2 '26 | $254.96M | $38.42M |
The other side is still buying
Consensus holds a moderate buy with an average target of $514.44, about 36% above the October 7 close 13. Phoenix Financial bought 2,129,282 shares at $372.10 on September 7, roughly $792 million, lifting its holding to 2,746,913 shares 6. The board authorized a $200 million buyback on September 2, up to 1.9% of shares 71, for a stock that closed October 7 39% below its June 15 intraday high of $615.99 2. Against that, insiders sold $6.7 million of stock over twelve months with no purchases, all under trading plans 2, and the chief executive's 2026 bonus pays 40% on revenue and 30% on M&A strategy 5. The shares carry a 1.5% trailing free-cash-flow yield at 12.4 times trailing revenue 5.
The test is collections, not revenue
The next report tests delivery against the $277–287 million guide 4, and the deciding line is whether $210.3 million of receivables turns into cash 5. Management presents its next strategic model at an investor day early in 2027 4. So far the AI boom has paid Nova in booked revenue; the next print shows whether it pays in collected cash.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.