Wolfspeed now sells premium wafers to its competitors, and guides to lose money doing it
Wolfspeed made its premium 200 mm silicon carbide substrate orderable this week and reports on October 28 with the September quarter guided to $140–160 million of revenue and a negative gross margin. The tape, up 33% in a week on retail buying, sits more than $8 above the average analyst target.
 Vincent Jiang · 3 min read
The Roaring Kitty remix
Wolfspeed's retail crowd spent the week quoting Roaring Kitty. A thread on r/wolfspeed put "Mr. Market says Wolfspeed is a $31.17 stock" over a chart, and a Stocktwits post counted the shares up 33% in a week 12. The move was real: WOLF closed at $35.28 on October 2 after a 13.19% jump 4, then slid 4.90% to $33.55 on October 5 7. This is a company that canceled its old shares in bankruptcy court 13 months ago; the replacement shares surged more than 1,000% on day one 8.
The wafer it sells to its rivals
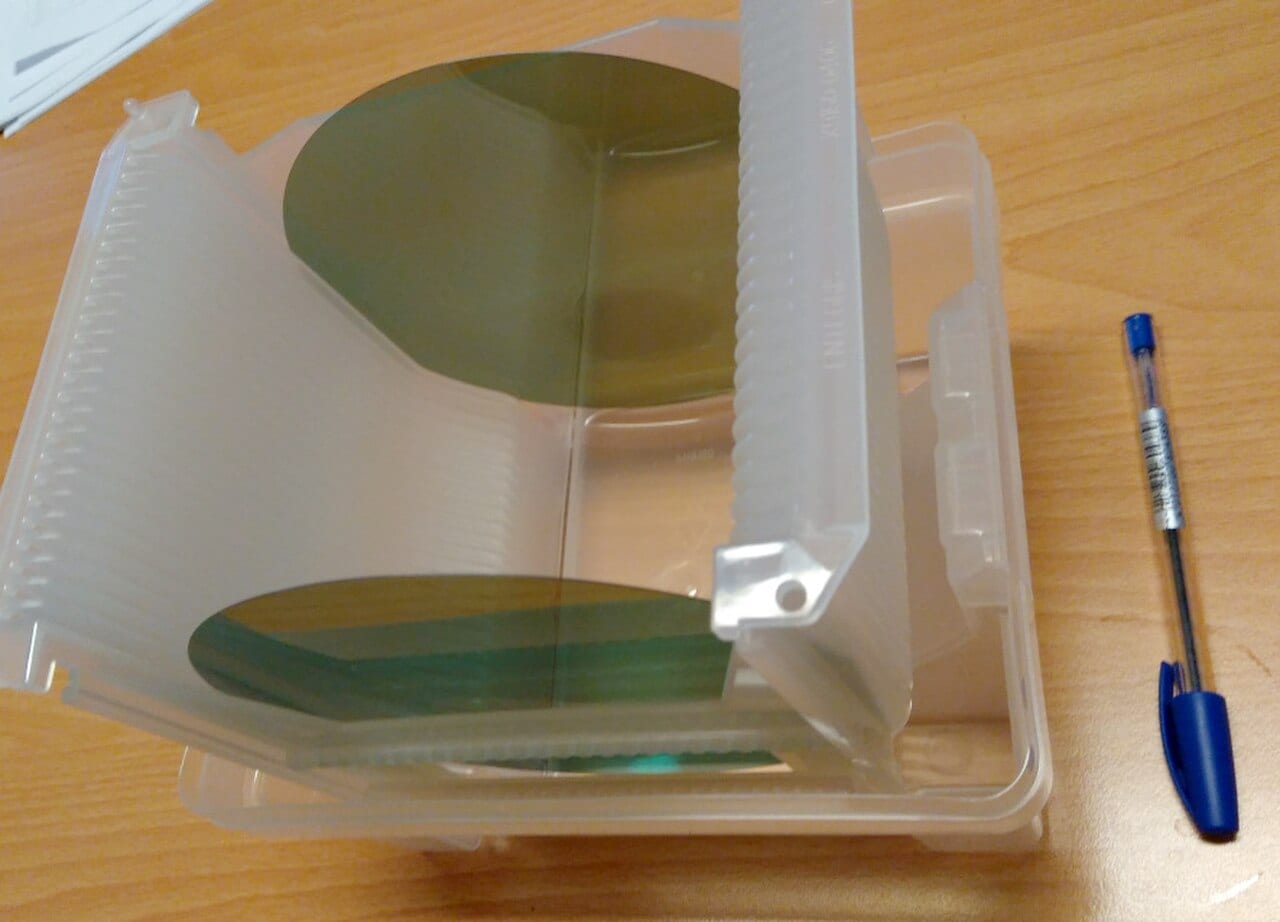
On September 27, Wolfspeed made its Premium 200 mm n-type silicon carbide substrate orderable: fewer than 0.01 micropipes per square centimeter, fewer than three per wafer, with dedicated capacity and room to ramp inside its existing fab 3. A micropipe is a hollow defect that kills whatever device is built on top of it 11. The customers Wolfspeed names are "silicon carbide device manufacturers" 3, and Wolfspeed builds those devices itself 6. The pivot sells the starting material to everyone, competitors included.
A guide to lose money by
The launch lands on numbers pointing the other way. Fiscal 2026 revenue fell to $665.1 million from $757.6 million 4. The June quarter dropped 24.1% to $149.6 million 6. GAAP gross margin has been negative in all four quarters since the Chapter 11 exit 5, and the September quarter is guided to $140–160 million with a negative non-GAAP gross margin 4.
Gross margin has been negative every quarter since the Chapter 11 exit, narrowing for two straight quarters
Data
| GAAP gross margin | |
|---|---|
| Sep '25 | -39.2% |
| Dec '25 | -46.5% |
| Mar '26 | -26.6% |
| Jun '26 | -24.5% |
Four quarters down, no floor in the guide
Revenue has fallen every quarter since the bankruptcy exit, and the guide holds it flat
- Revenue
- Estimate
Data
| Revenue | |
|---|---|
| Sep '25 | $196.8M |
| Dec '25 | $168.5M |
| Mar '26 | $150.2M |
| Jun '26 | $149.6M |
| Sep '26 guide (estimate) | $150M ($140–160M) |
The guide's midpoint matches the June quarter, so the slide stops only if Wolfspeed beats it 4. Five analysts, one Buy, three Holds and one Sell, average a $25.00 target, $10.28 below the October 2 close 64. The 52-week range of $13.48 to $80.82 is what a positioning-driven tape looks like 4. On its own guidance, more than a dollar of cost goes into every dollar of September-quarter sales, and the market paid $35.28 a share for the privilege.
The AI counterargument
The bull case is hyperscale power. Wolfspeed qualified its silicon carbide MOSFETs for LITEON's 800 VDC platforms aimed at AI data centers 9, and in July it sued Navitas to defend the patents behind that hardware 10. Materials chief Cengiz Balkas calls the substrate "a stronger foundation" for demanding devices 3. None of it is revenue this quarter, and the guide carrying those wins still says negative gross margin 4.
October 28 decides
Earnings land on October 28, the first print where substrate orders must answer the device decline, with the annual meeting the day before 4. No source discloses order volume for the new wafer, so the squeeze and the story part ways there. The tell is one line: if the December-quarter margin guide is still negative, the wafer business is not yet carrying the factory.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.