YTL Power's 72.7% rally prices a data centre listing the company has not announced
Fourteen of fifteen research houses rate YTL Power positively, none at sell, on a data centre segment they value anywhere from RM1.40 to RM5.13 a share. The quarter behind the rally was half billing catch-up, and the Yeoh family has just seated the heirs who would inherit the listing decision.
 Vincent Jiang · 3 min read
*Fourteen of fifteen research houses rate YTL Power positively, none at sell, on a data centre segment they value anywhere from RM1.40 to RM5.13 a share. The quarter behind the rally was half billing catch-up, and the Yeoh family has just seated the heirs who would inherit the listing decision.*
The heir and the unit that carries the stock
On 24 September, Bursa filings seated 12 grandchildren of the late founder Yeoh Tiong Lay across the boards of YTL Corp, YTL Power and Malayan Cement, aged 25 to 41 1. All seven branches of the founder's second generation were represented in the exercise 1.
The one that matters is Yeoh Keong Hann, 40, son of YTL Power managing director Yeoh Seok Hong, elevated that day to a full executive director seat at YTL Power and an alternate seat at YTL Corp 134. He spearheaded YTL Data Center Holdings 2, runs the group's investments, digital and infrastructure portfolio behind the Nvidia partnership 3, and sits on the PowerSeraya and Wessex Water boards 2.
What the 72.7% is made of
YTL Power closed at RM5.66 on 17 September, up 72.7% for the year; the 52-week range runs RM2.51 to RM6.02 56. On 24 September, the day the grandchildren filed in, the stock settled 1.86% lower at RM5.80, valuing it at RM50.7 billion; YTL Corp holds 52.46% 1. Fourteen of 15 research houses rate it positively, none at sell, on an average target of RM6.52 5.
The quarter was half a billing catch-up
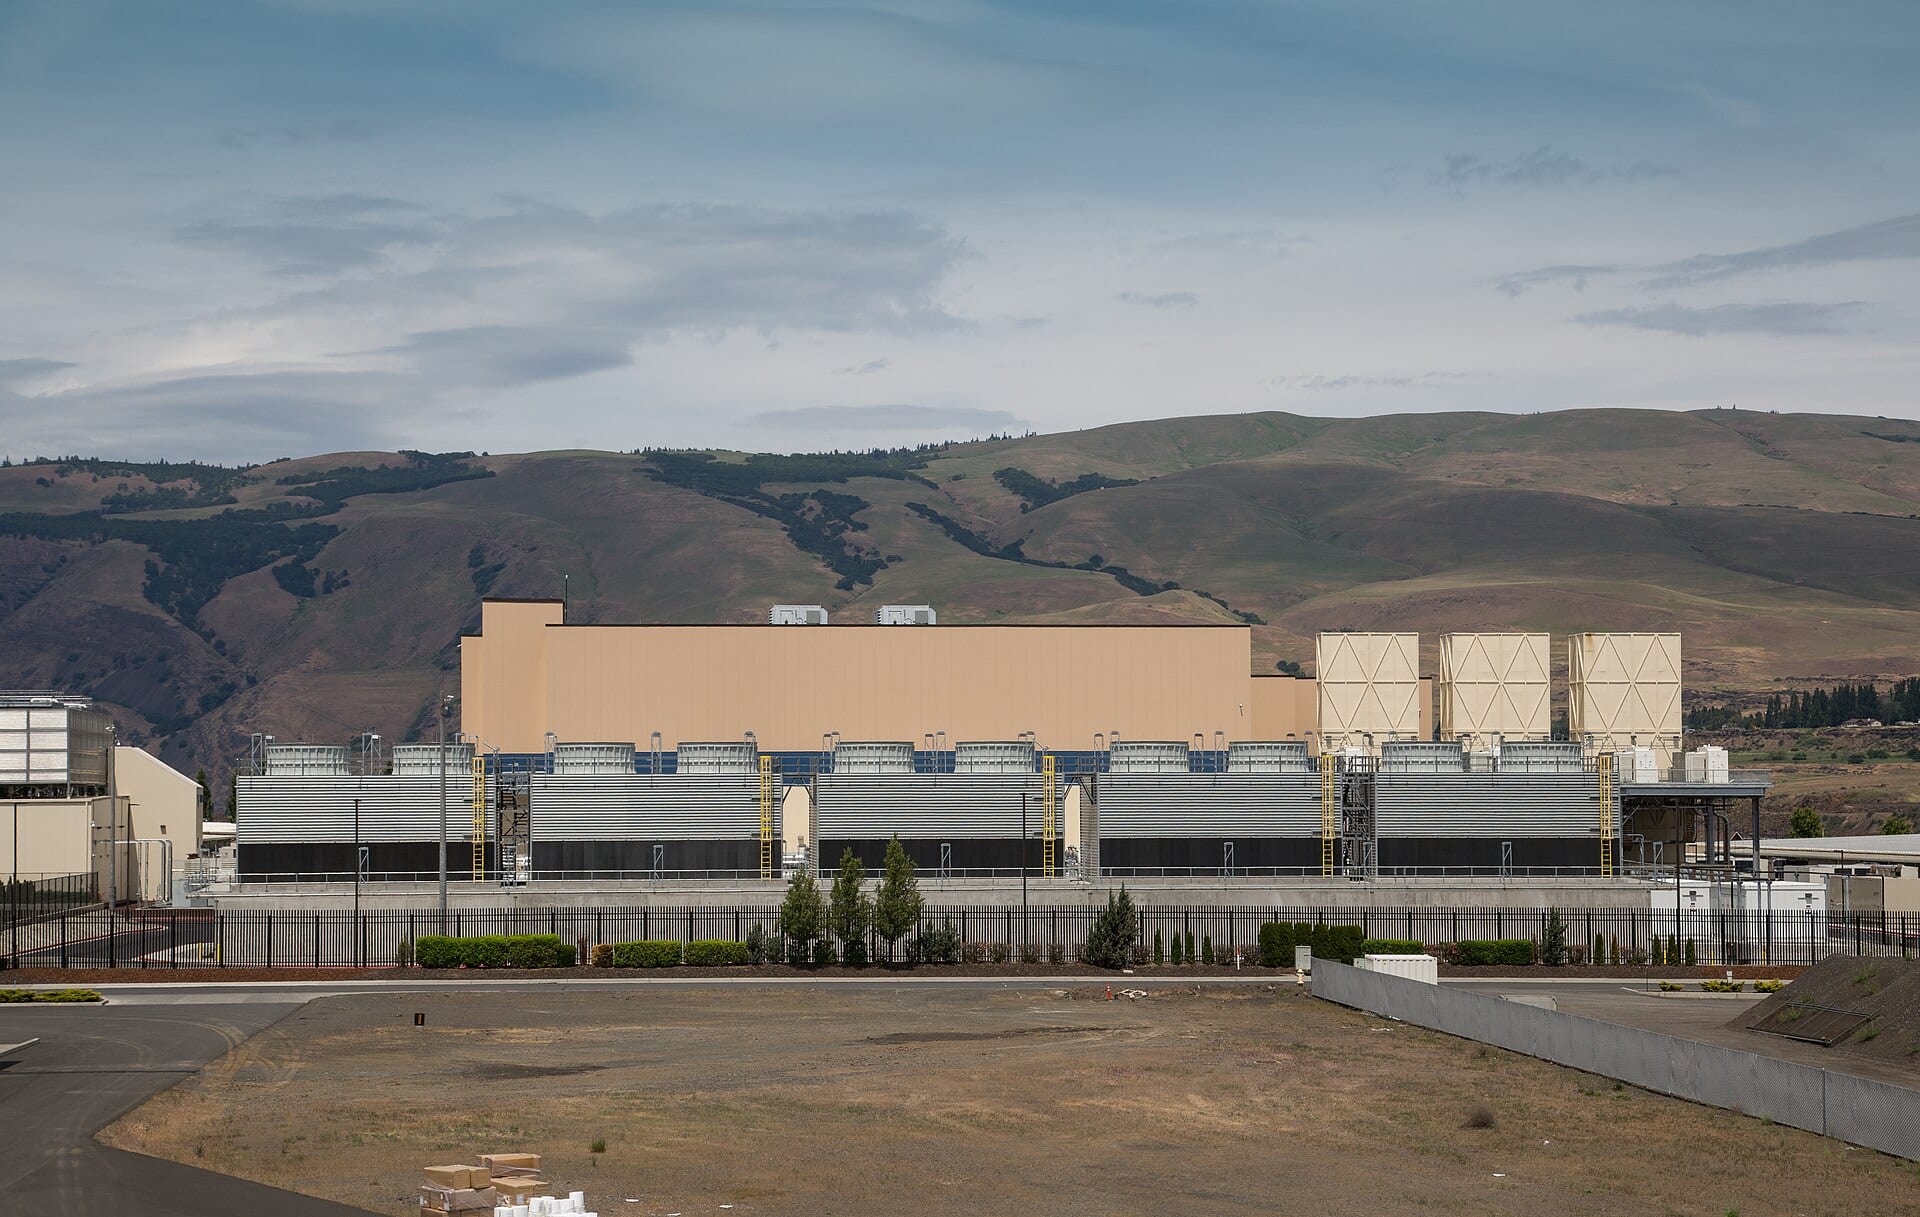
The data centre segment, broken out standalone from 3QFY2026, booked fourth-quarter profit before tax of RM244.3 million, up more than 300% quarter on quarter, the number behind the re-rating 5. MBSB Research estimates contractual escalation catch-up made up about 30% of segment revenue and half of PBT; stripped out, the underlying business earned roughly RM122 million on RM320 million, a 38% margin, from 150MW of live capacity 5.
The houses value that business anywhere from RM1.40 to RM5.13 per share, a 3.7-times spread that is a fight about future capacity, not the reported quarter 5. A buyer at RM5.66 against a RM6.52 average target is underwritten by that run rate: roughly RM122 million of underlying PBT a quarter from 150MW, if the catch-up does not repeat 5.
150MW is live and earning; the pipeline being valued runs to 4.5GW
- Capacity (MW)
- Estimate
Data
| Capacity (MW) | |
|---|---|
| Live, FY2026 | 150MW |
| Contracted, FY2026 | 298MW |
| MBSB est, end-FY2027 (estimate) | 258MW |
| JPM est, FY2030 (estimate) | 898MW |
| Stated ambition, 2030 (estimate) | 2,400MW |
| Sedenak, theoretical (estimate) | 4,500MW |
The bill for the ambition
FY2026 shows the cost side: attributable net profit fell 33.7% to RM1.69 billion on revenue of RM22.02 billion 5. The build took RM7.91 billion of capex, cash dropped to RM8.65 billion from RM12.22 billion a year earlier, and borrowings stood at RM39.88 billion at end-June 5.
Cash fell by nearly a third in FY2026 while borrowings stood near RM40 billion
Data
| RM billions | |
|---|---|
| Cash, FY2025 | RM12.22B |
| Cash, FY2026 | RM8.65B |
| Capex, FY2026 | RM7.91B |
| Borrowings, end-FY2026 | RM39.88B |
The funding plan is a RM10 billion sukuk for the data centre business, expected by end-2026, which Hong Leong Investment Bank sees paving a possible IPO, while management obtains a credit rating and weighs a corporate listing over a REIT 5. YTL Power has announced no listing 5.
The assets are real; the timing is the bet
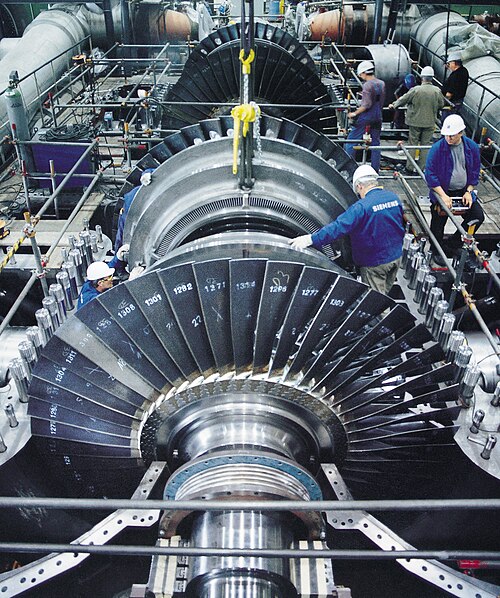
PowerSeraya gets a 600MW hydrogen-ready plant by end-2027, and Singapore's regulated household tariff rose 17% into the September quarter 5. Seven reserved Siemens turbines cover 5.25GW of potential capacity, sized by TA Securities at RM450–500 million of annual profit if fully deployed 57. Managing director Yeoh Seok Hong calls energy "the foundation of the AI economy" 7.
SIPP Power has bought 145 acres at Sedenak Tech Park West, with an option on 400 more, toward the stated 2.4GW 8. JP Morgan flags potential colocation oversupply in Johor 5.
What decides it
Nothing in the filings says the family is selling; Keong Hann himself holds 3.19 million YTL Power shares and two million options, and the record shows heirs seated beside the decision 14. Watch the sukuk pricing and any listing filing before end-2026, and the first quarter without the catch-up, which MBSB expects to open with live capacity still at 150MW 5. The stock is pricing the listing. The family has only sized the sukuk.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.