Zoom opened its speech AI to rivals and wired in Meta's Muse; the market still pays 8.4 times earnings
The CTO opened Zoom's Scribe speech API to the note-taking startups it competes with and wired meetings into Meta's Muse, the agent Amazon blocked. The earnings say AI is a business; the opened layers are the gamble.
 Vincent Jiang · 2 min read
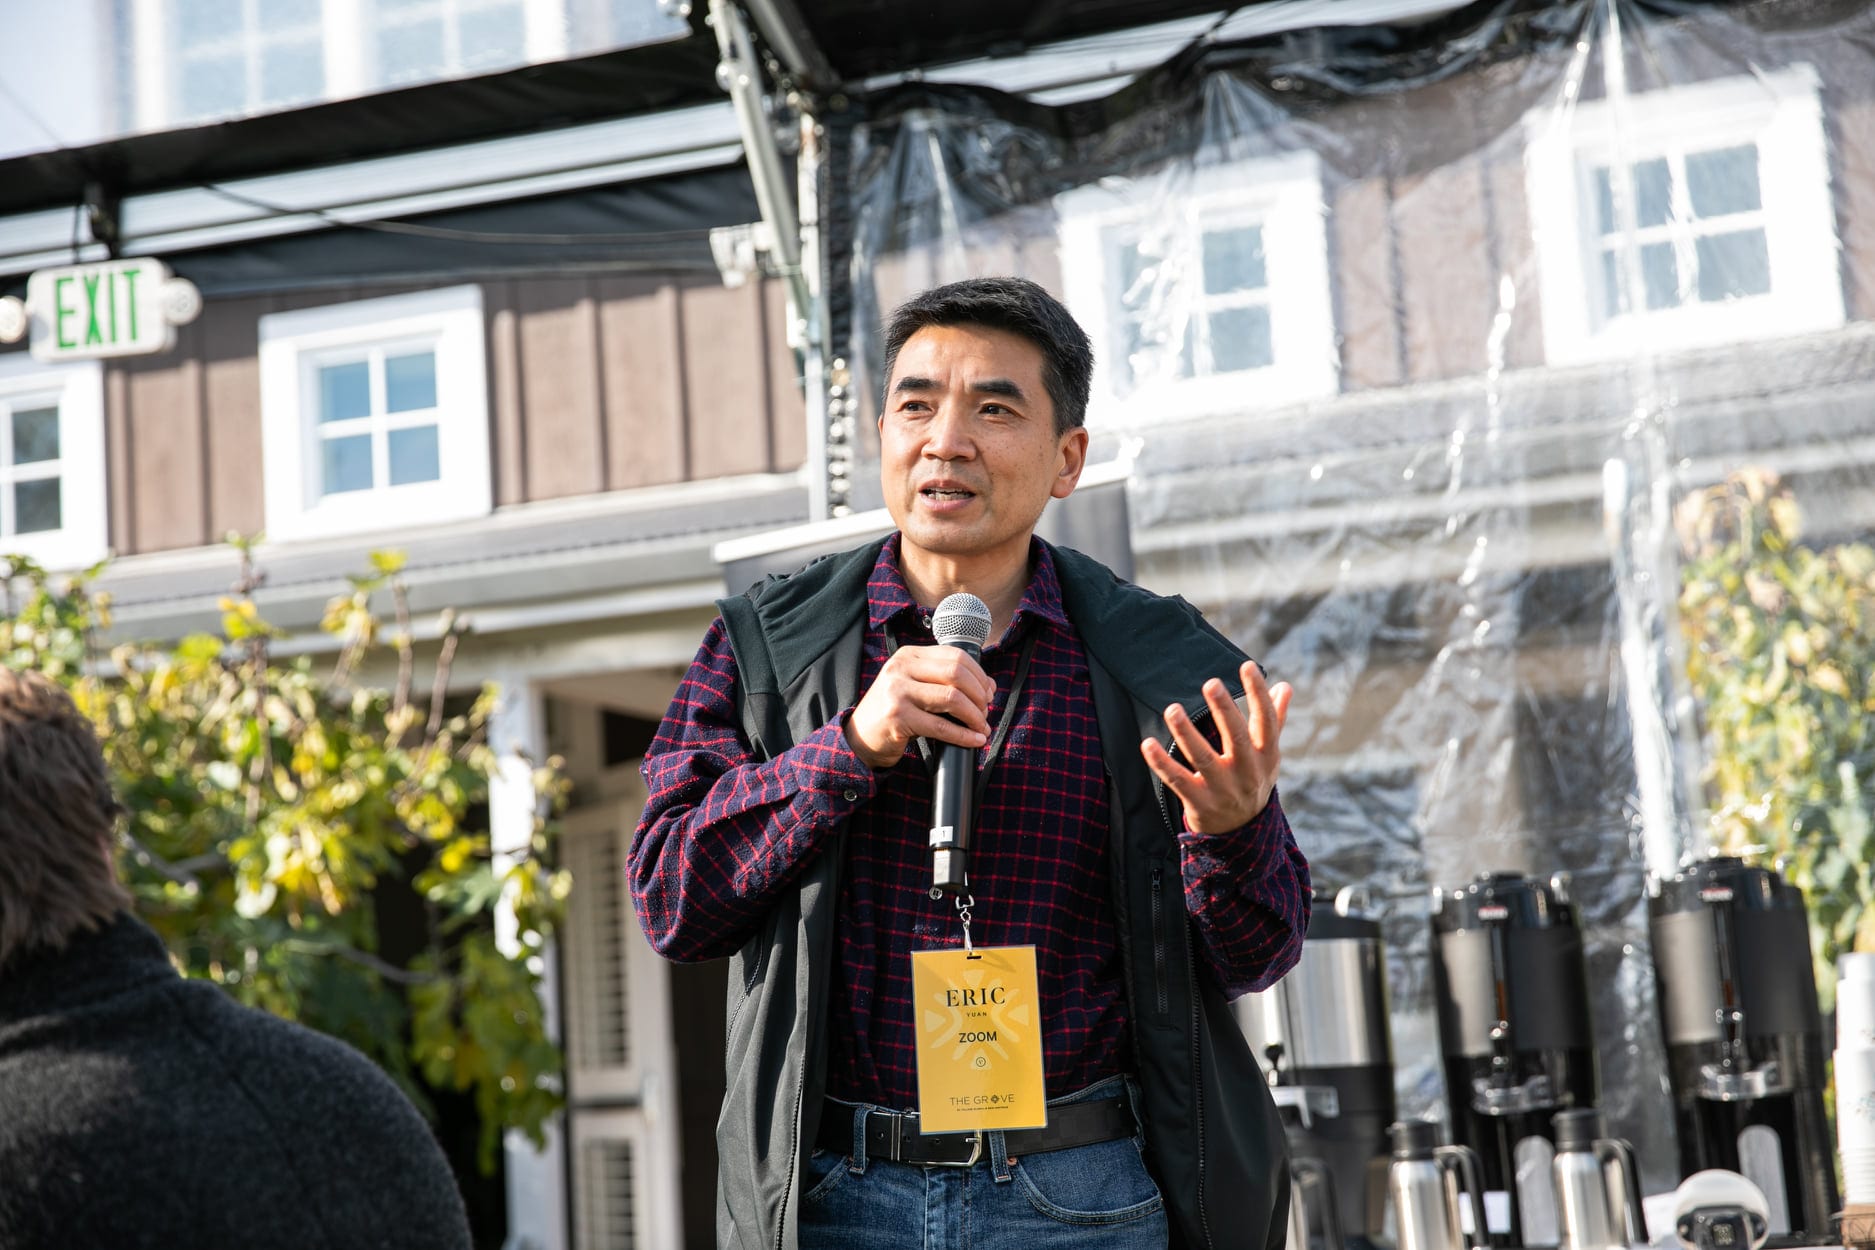
Zoom spent the week of October 5 handing away the two layers its AI story rests on. Zoom wired its meeting intelligence into Meta's Muse, the consumer shopping agent Amazon blocked from its site rather than let an outside agent learn its customers 25. The next day, chief technology officer XD Huang told TNW that the speech recognition behind My Notes, Zoom's flagship meeting-notes tool, is now open to anyone as the Scribe API, and that AI note-taking startups, the companies built on Zoom calls, are in talks to switch to it 1.
The layer below the product is free
Huang frames the shift as "C2C", conversation to completion 1. "2026 would be the year of completion," he said 1. Scribe has topped the Open ASR Leaderboard of more than 60 speech systems since its first version 1. That is a genuine asset being commoditized. Amazon kept Muse out at any cost; Venn launched "super agents" on October 6 on the explicit pitch that real estate should refuse outside agents entirely 5. Zoom chose the open door, and opened the seat itself to an agent layer that could replace it.
The other answer: charge inside the seat
Zoom's own earnings say its AI is a business, not a giveaway. Every one of its top 10 fourth-quarter fiscal 2026 deals included paid AI features, seven were competitive displacements of rival contact-center vendors, and one major US retailer signed a near-seven-figure-ARR deal for Zoom Virtual Agent across more than 1,100 stores 3. Fiscal 2026 revenue reached $4.869 billion, up 4.4% 3. Enterprise revenue grew 7.8% year over year in fiscal Q2 2027 and is 62% of the total 4.
Enterprise growth at 7.8% is pulling against a 3.9% company guide
- Total revenue
- Enterprise
- Estimate
Data
| Total revenue | Enterprise | |
|---|---|---|
| FQ2'27 | 4.9 | 7.8 |
| FQ3'27 guide (estimate) | 3.9 | — |
Why the market shrugs
The market still pays 8.4 times earnings against 21.5 for the median S&P 500 company, and the multiple is flattered: $3.3 billion of trailing net income against only $1.2 billion of operating income, so most of the profit making Zoom look cheap did not come from operations 4.
Net income has outrun operating income twelve quarters running, and hit $1.5B last quarter
- Operating income
- Net income
Data
| Operating income | Net income | |
|---|---|---|
| Q3 '23 | 0.17 | 0.14 |
| Q4 '23 | 0.17 | 0.3 |
| Q1 '24 | 0.2 | 0.22 |
| Q2 '24 | 0.2 | 0.22 |
| Q3 '24 | 0.18 | 0.21 |
| Q4 '24 | 0.23 | 0.37 |
| Q1 '25 | 0.24 | 0.26 |
| Q2 '25 | 0.32 | 0.36 |
| Q3 '25 | 0.31 | 0.61 |
| Q4 '25 | 0.25 | 0.67 |
| Q1 '26 | 0.31 | 0.43 |
| Q2 '26 | 0.31 | 1.54 |
Against that sits $7.2 billion of cash and securities on a $27.2 billion market value, and a $1.6 billion buyback last fiscal year 4. But management guided fiscal Q3 2027 growth to 3.9% at the midpoint, below the 4.9% delivered in fiscal Q2 4.
The bet a buyer makes here is that the opened layers turn into tolls. At the next print, two signals decide it: whether opened-layer usage converts into paid SKUs, and whether fiscal Q3 lands above the 3.9% guide.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.