Analysts still call Teradata a Buy, but its own 10-Q says $1,068 million of contracts can be canceled
Wall Street still rates Teradata a Buy on $700 million of cloud ARR. The 10-Q filed November 6 shows more than half the contract base can be canceled for convenience, and this year's profit is mostly a legal settlement.
 Vincent Jiangthree-minute read
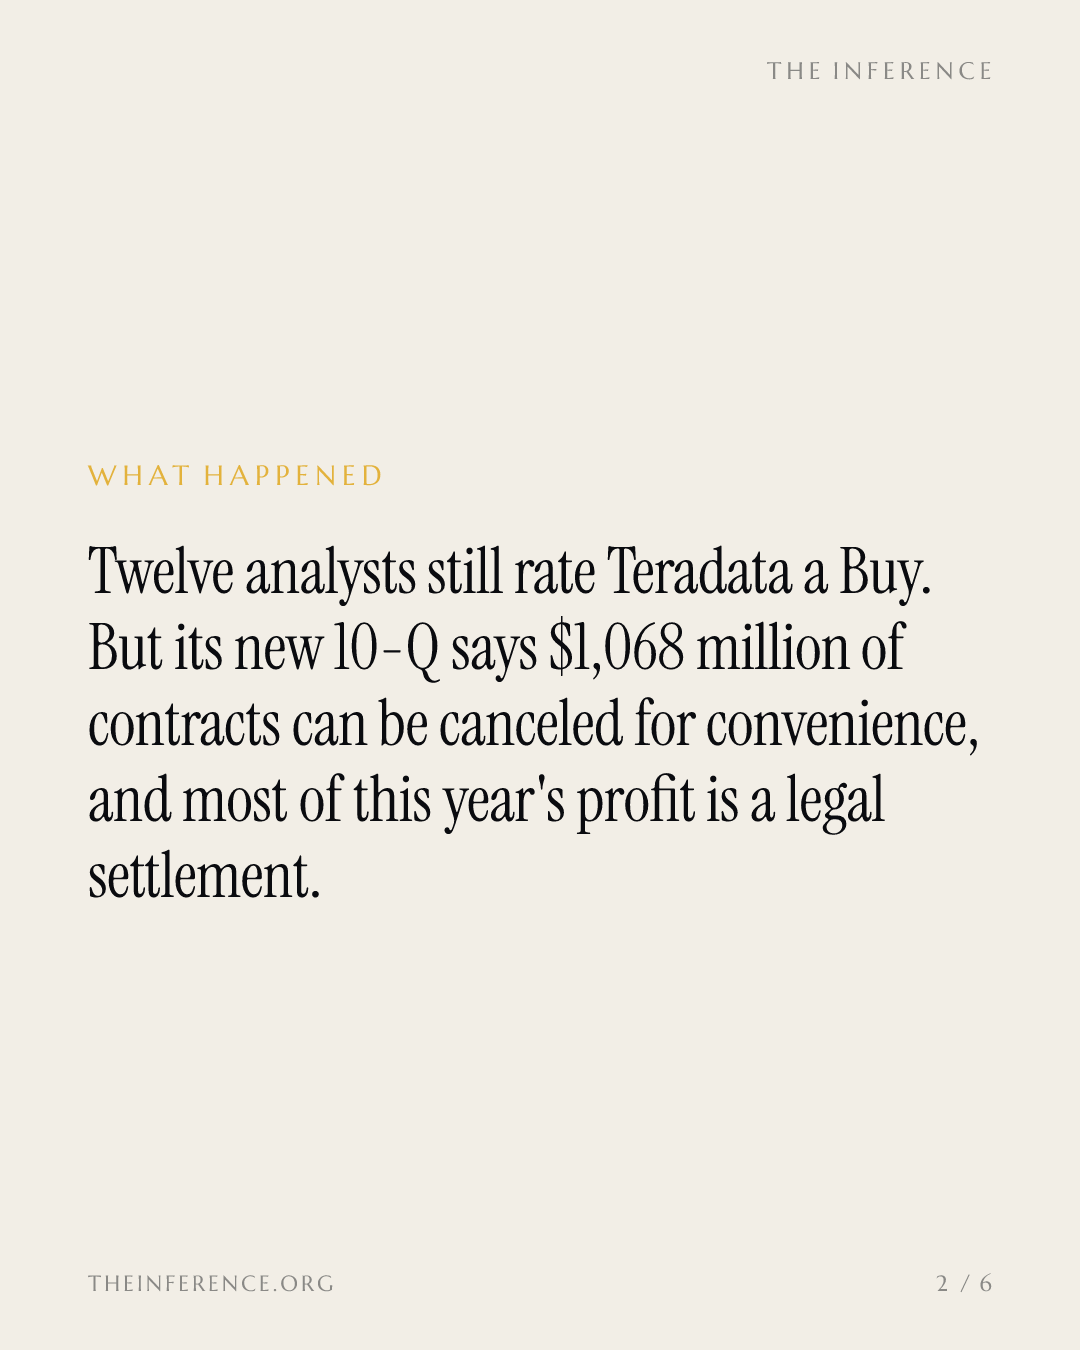
Twelve analysts still call Teradata−1.92% — Teradata, down 1.92 percent today a Buy. The average price target is $34.50 against a $31.80 share price, Citi+0.62% — Citi, up 0.62 percent today raised its target to $40 on October 30, and the bull case rests on one number: Public Cloud annual recurring revenue of $700 million, up 11% year on year 13. On November 6, the company's own 10-Q told a less comfortable story about what stands behind that number 13.
The contract base behind the ARR is mostly revocable
The filing values firm orders not yet performed at $1,997 million 1. Of that, $1,068 million sits under contracts customers may cancel for convenience, and Teradata expects only about $492 million of next-year revenue from non-cancelable contracts 1. A subscription annuity is not what the paper describes. It is a renewal-risk business, one notice letter at a time.
The cloud line is growing, but the ground under it is not
Total ARR of $1.512 billion grew just 1% 1. The 10-Q's own ARR table shows where the growth came from: Public Cloud ARR rose to $700 million from $633 million, while Subscription ARR fell to $744 million from $765 million and legacy maintenance fell to $68 million from $92 million 1. Management attributes the declines largely to customers migrating to Public Cloud. Migration, not net new demand, is doing the lifting, and total ARR growth of 1% is the tell 1.
Cloud ARR growth is partly migration, not net new demand
Cloud ARR gains of $67 million came while Subscription and maintenance shrank $45 million
- Q3 2025
- Q3 2026
Data
| Q3 2025 | Q3 2026 | |
|---|---|---|
| Public Cloud | 633 | 700 |
| Subscription | 765 | 744 |
| Maintenance | 92 | 68 |
The headline numbers flatter the year
Q3 revenue fell 4% to $399 million from $416 million, recurring revenue slipped to $359 million from $366 million, and net income eased to $38 million from $40 million 1.
The nine-month net income of $419 million, up from $93 million, rests on the SAP−5.56% — SAP, down 5.56 percent today legal settlement: a $480 million gross payment received in March, $121 million in fees, roughly $359 million net before taxes, and $326 million of the nine-month operating cash flow jump to $598 million 1. Strip the settlement and the operating engine shows income from operations of $66 million for nine months, down from $151 million 1.
Net income quintupled while operating income fell by more than half
- 9M 2025
- 9M 2026
Data
| 9M 2025 | 9M 2026 | |
|---|---|---|
| Income from operations | $151M | $66M |
| Net income | $93M | $419M |
The market took the print as a beat: adjusted EPS of $0.70 came in 21% above consensus, though billings fell 28% year on year 4. Meanwhile management repurchased about 4.5 million shares at an average $29.55, with $377 million of authorization remaining, authorization the filing notes is not an obligation 1.
The strongest counter is the one Wall Street holds
Citi's $40 target and five Buy ratings assume migration converts to expansion and the cancelable book sticks 3. That is a bet, not a disclosure. The filing gives no churn rate, and until a 10-Q shows how much of the $1,068 million cancelable book survives renewal, the cloud-ARR line should be priced as revocable revenue, not a fortress of contracted growth 1. The next reading arrives with the Q4 report in February 1.
The next reading arrives in February
Get Platforms by email, free
The cloud, data and developer software AI is built on. In our daily email, every weekday.