ZoomInfo beat and raised its year, yet trades at 1x sales: the bet is whether AI usage ever bills
ZoomInfo beat on revenue and raised its year, yet trades at 1x sales because seat licenses are being swapped for AI usage that draws down prepaid credits before it bills anything. The late-Q4 GTM1 launch is the trigger that decides whether holders or shorts collect.
 Richard Tangtwo-minute read
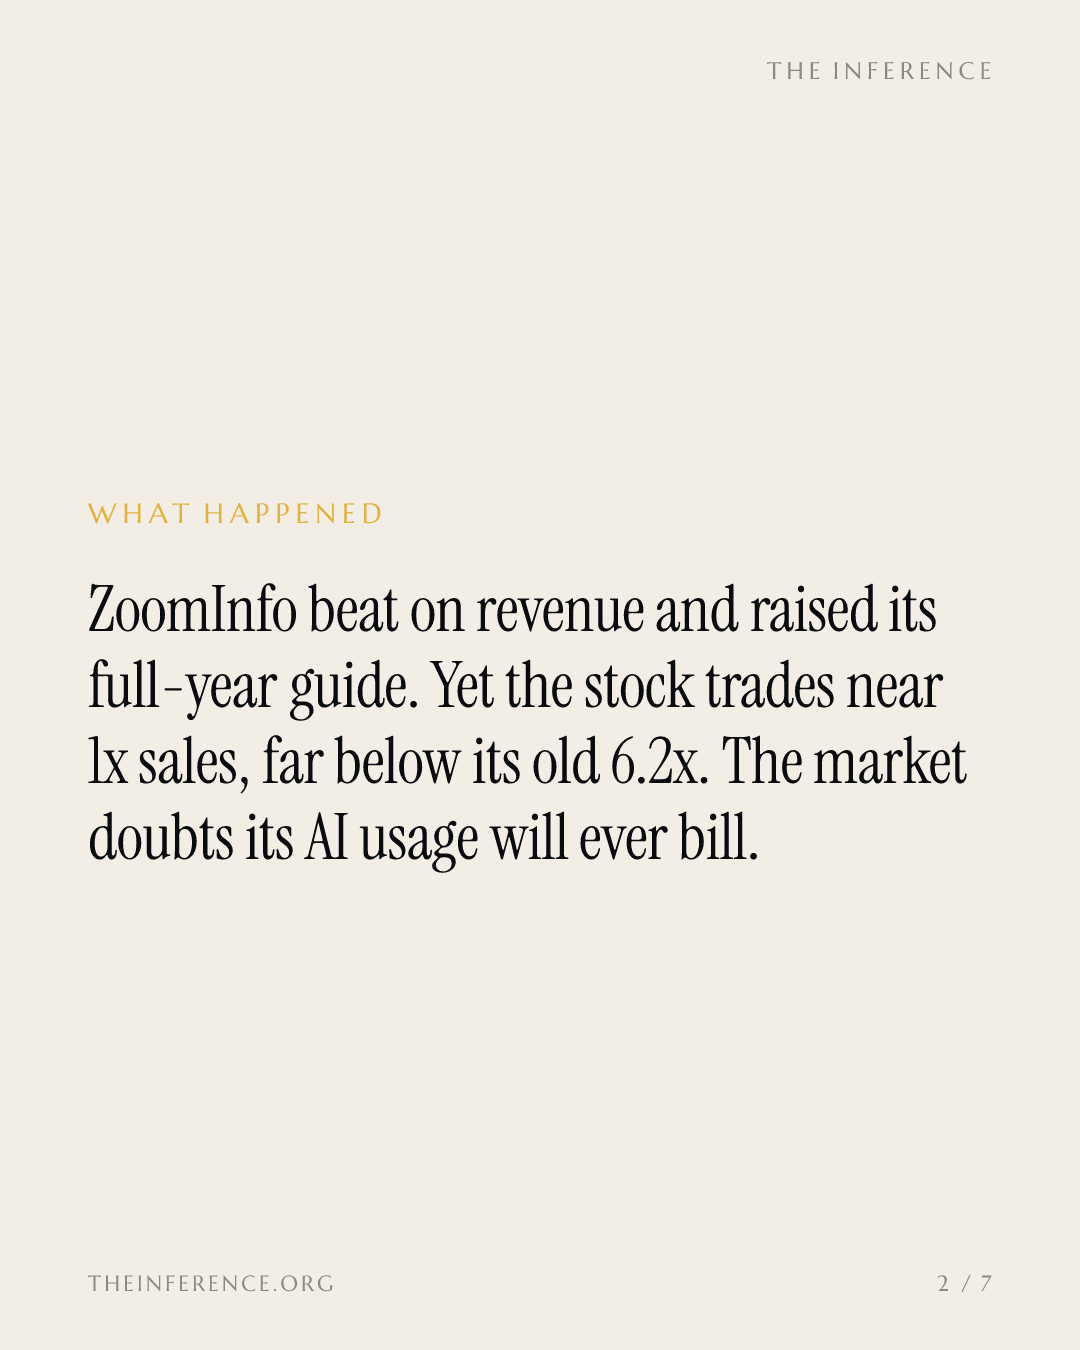
ZoomInfo−1.56% — ZoomInfo, down 1.56 percent today, the go-to-market data provider, beat on revenue, raised its full-year guide and still trades at a price-to-sales ratio of 1.03 against its own 6.2 historical median 1. That gap is the story: the market refuses to pay for a 39% adjusted operating margin because management is deliberately swapping per-seat licenses for AI usage whose revenue has not started 2. The Q3 raise is flow-through of the quarter, not a changed outlook 2, and the Q4 guide of $294 million to $297 million means the decline continues 34.
Usage doubled, but it draws down credits customers already bought
The mechanics are honest. Customers building custom AI agents on ZoomInfo's data through MCP servers and APIs doubled their consumption sequentially 2, but management says that usage draws down credit commitments already purchased before it generates any incremental revenue 2. The seats are not given away; the revenue is deferred.
Net revenue retention fell to 88% on weak software-vertical upsells, and upmarket annual contract value is flat 12.
Revenue has drifted down for four quarters, and Q4 guidance points lower
ZoomInfo's revenue has fallen for four straight quarters, and guidance points lower
- Revenue
- Estimate
Data
| Revenue | |
|---|---|
| Q4 '25 | $319.1M |
| Q1 '26 | $310.2M |
| Q2 '26 | $310.4M |
| Q3 '26 | $308.8M |
| Q4 '26 guide (estimate) | $295.5M |
A company swapping seats for deferred usage looks, in the revenue line, like it is shrinking. The new guide points lower still 3.
Piper sees a trough, RBC sees a shrinking seat base
So who pays, and who could win. Shareholders pay the bill for now, but they own a business signaling $405 million to $425 million in 2026 unlevered free cash flow 5, retiring discounted debt 2 and holding 77% of contract value upmarket 2.
Free cash flow fell for three straight quarters, to $33.4 million in Q3
Data
| Free cash flow | |
|---|---|
| Q4 '24 | $85.6M |
| Q1 '25 | $104.4M |
| Q2 '25 | $86.9M |
| Q3 '25 | $70.4M |
| Q4 '25 | $127.1M |
| Q1 '26 | $88.7M |
| Q2 '26 | $69.6M |
| Q3 '26 | $33.4M |
Piper Sandler upgraded the stock on November 5, to Neutral from Underweight with a $4 target; RBC kept an Underperform with a $3.50 target, exactly where the shares closed 3. The bears' case is that usage never bills. The bulls' case is management's: win-backs from cheaper rivals up 10%, approaching a growth trough 2. Both cannot be right yet, and the record does not settle it.
GTM1 launches late in the fourth quarter
The test is dated. GTM1, the AI platform replacing per-seat licenses with data and AI consumption credits, launches late in Q4, and Q4 guidance assumes no benefit from it 2. Watch whether consumption converts into billings after existing credits are exhausted. If it does, the Q3 print is the low point; if credits stay free, the 1x price is fair 2.
Get Platforms by email, free
The cloud, data and developer software AI is built on. In our daily email, every weekday.