AppLovinがプラットフォームを開放、広告主にはまだ「宿題」が残る
AppLovinの広告システムで最も難しいのは広告制作そのもの――創業者のアダム・フォロウヒCEOはそう語る。ゲーム広告主以外への拡大を目指す中、年率53%の成長事業を制約する構造的課題となっている。
 Vincent Jiang · 2 min read
8月5日、アダム・フォロウヒ最高経営責任者(CEO)はアナリストに対し、AppLovinの広告システムにおける最大の課題は「依然として広告制作そのもの」だと語った4。
見出しの裏にある数字
これは四半期売上高が前年同期比53%増の19億2400万ドルという数字を報告している事業にとって重要な意味を持つ。8月5日に発表されたAppLovinの暫定決算であり、ゲーム広告主以外の分野への拡大は次なる成長機会の柱と位置づけられている1。
分析師はすでに織り込みを進める
9月14日、モルガン・スタンレーは目標株価を650ドルから450ドルに引き下げたが、投資判断「オーバーウェイト(市場平均を上回る)」は据え置いた。エバーコアも9月1日、過去のeコマース広告主向け支出の推計値が高すぎたことを認め、目標を引き下げた。いずれも報道されたアナリストの見解であり、新たな業績情報ではない7,8。
広告主が先に仕上げるべきこと
実務的に重要なのは、AppLovinが次の売上を得るために、広告主が何を仕上げなければならないかだ。
フォロウヒは6月22日の発表で、紹介要件を撤廃し、キャンペーン作成をほぼワンクリックで実現すると述べた。AppLovin Adsは自社の推薦システム「アクソン(Axon)」を活用し、モバイルゲーム内の広告主と見込み購入者を結びつける。プラットフォームはすべての利用者に開放された5。
だが8月時点で、高品質な30〜60秒の動画をすぐに提供できる段階には達していないとフォロウヒは認めた。小規模事業者は限られたテスト予算でリターン目標の達成にも苦戦している。同社はそのため中規模ブランドへの注力に切り替えている。これらはボトルネックについての同社の説明であり、独立して計測された失敗率ではない4。
現在の導入手順は残された作業を具体的に示している。購入トラッキングの検証、システムが学習するのに十分なコンバージョン予算の確保、そして動画広告の継続的なテストだ。アルゴリズムが効果を証明する前に、オンラインショップ側は資金、素材、運用の手間を投入しなければならない6。
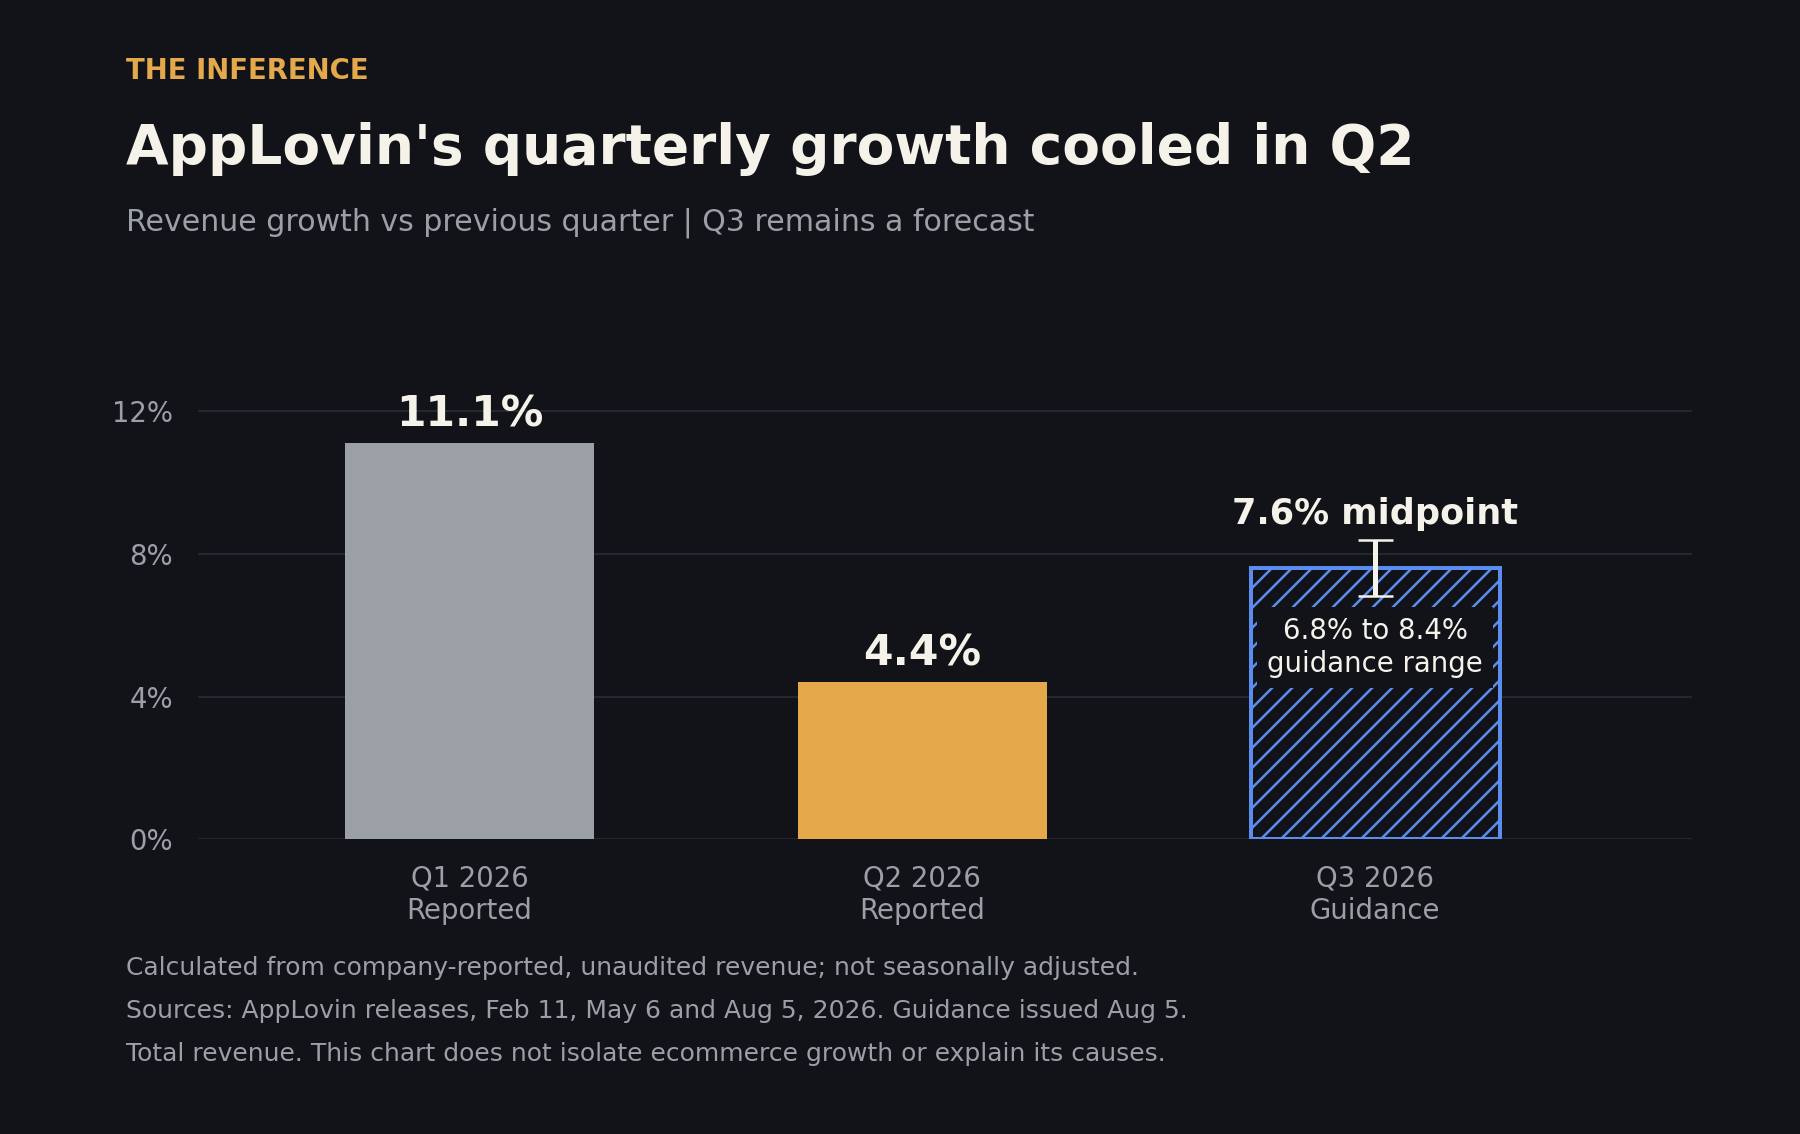
これは拡大に伴う制約事項だ。経営陣は第2四半期の減速について、主にゲーム向けモデルの改善タイミングが原因だと説明している。減速全体をeコマース分野の失敗と結びつけるのは、現時点の証拠を超えた過大評価になる4。
AI導入のコストには、顧客がまだ自ら行わなければならない作業が含まれる。
強気派にも根拠はある
強気派には裏付けがある。トリプルホエール(Triple Whale)の9月3日の報告は、AppLovinに支出している755店舗を対象に調査し、条件を満たした店舗の61%で比較対象チャネルを上回る帰属リターンを確認した。7つの地域ホルドアウトテストのうち5つで、統計的に有意なプラスの売上効果も報告された9。
これはAppLovinと提携する測定プロバイダーによる単一情報源の証拠だ。キャンペーンが成果を生みうることを裏付ける一方、小規模事業者の多くが導入を成功させられるかどうかは未解明のままだ10。
フォロウヒにとって次に示すべき成果指標は、新規登録、キャンペーン開始、そして持続的な黒字支出を結びつけるものになるはずだ。より優れたクリエイティブツールが、外部支援への依存を減らして小規模広告主にこのプロセスを完走させるかどうかが注目される。
新規広告主のうち、黒字で支出を続けているのが何社かを注視したい。
How this brief was made
01Gathered & sourced307 channels · 1,871 articles▾
Agents swept 307 channels and ingested 1,871 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated10 claims · 12 data feeds▾
Every one of 10 load-bearing claims was checked against primary sources, with 12 live data feeds reconciling the figures and charts.
- 1AppLovin Q2 2026 financial results, Aug 5 2026 (company-claimed and unaudited primary disclosure: revenue of $1,923,686 thousand and Q3 guidance of $2,055M to $2,085M. The SEC copy is the same source, not a second one).
- 2AppLovin Q1 2026 financial results, May 6 2026 (company-claimed and unaudited: revenue of $1,842,449 thousand, used as a chart input).
- 3AppLovin Q4 2025 earnings exhibit, Feb 11 2026 (company-claimed and unaudited: revenue of $1,657,944 thousand, the denominator for Q1 sequential growth. Labelled unaudited, and distinct from the later audited annual statements).
- 4AppLovin Q2 2026 earnings call, Aug 5 2026 (management's own statements, read in a third-party transcription: the video-generation limitation, the focus on midsized brands, and the gaming-model explanation for slower growth. Audio was not independently transcribed).
- 5AppLovin's announcement opening the platform, Jun 22 2026 (company-claimed: the referral requirement removed and one-click creation described as an aspiration, not a completed capability. AppLovin Ads is the platform; Axon is the recommendation system).
- 6AppLovin launch checklist, accessed Sep 14 2026 (company product instructions establishing the remaining customer work: tracking, learning budget, creative adaptation and repeat testing. The video duration is guidance rather than an eligibility rule, and the documentation discloses no failure or churn rate).
- 7Morgan Stanley price-target cut to $450 from $650, Overweight retained, Sep 14 2026 (the action is corroborated across ratings trackers; the client note was not accessed, and an analyst's conclusion is not an operating result. It is a $200 reduction, not a $200 target).
- 8Evercore ISI price-target cut, reported Sep 1 2026 (single-source account of the firm describing its own historical ecommerce-spend estimates as too high; the underlying note was not accessed, and analyst estimates are not company disclosures).
- 9Triple Whale report on AppLovin advertisers, updated Sep 3 2026 (single-source provider research over a selected cohort of 755 shops: 61% of qualifying shops showed higher attributed ROAS, and five of seven geographic tests were positive and significant. Shared-channel attribution can double count credit, the tests do not all measure the same revenue, and the study does not measure signup failures).
- 10AdExchanger on AppLovin's ecommerce and consumer expansion, Aug 5 2026 (reporting of company statements; it confirms the Triple Whale relationship described on the call rather than independently verifying operating claims).
03Reviewed & edited1 human editor▾
One editor read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.