앱러빈, 플랫폼 공개했지만… 광고주에게 남은 과제
아담 포루히 앱러빈 CEO는 광고 시스템의 가장 큰 난관이 여전히 광고 제작이라고 지적한다. 연간 53% 성장하는 이 사업이 게임 광고주를 넘어 확장하려는 데 이것이 제약으로 작용하고 있다.
 Vincent Jiang · 2 min read
8월 5일, 아담 포루히 CEO는 분석가들에게 앱러빈 광고 시스템의 최대 장애물이 여전히 광고 제작이라고 말했다.4
헤드라인 뒤에 숨은 매출
분기 매출 19억2400만 달러, 전년 대비 53% 증가 – 이는 8월 5일 발표된 앱러빈의 미감사 실적이다. 게임 광고주를 넘어선 확장이 향후 성장 기회로 주목받고 있다.1
애널리스트들은 이미 이 이야기에 할인을 적용하기 시작했다
9월 14일, 모건스탠리는 비중확대 등급을 유지하며 목표 주가를 650달러에서 450달러로 낮췄다. 에버코어는 9월 1일 목표를 하향 조정하면서 역사적 전자상거래 광고주 지출 추정이 과대했음을 시인했다. 이는 보도된 애널리스트 의견일 뿐, 새 운영 실적은 아니다.7,8
광고주가 먼저 해결해야 할 과제
핵심은 앱러빈이 다음 수익을 내기 전에 광고주가 무엇을 완료해야 하느냐다.
포루히 CEO는 6월 22일 출시 발표에서 추천 요건을 폐지하고 원클릭 캠페인 생성을 구상한다고 밝혔다. 앱러빈 광고는 Axon 추천 시스템을 통해 모바일 게임 내 잠재 구매자와 광고주를 연결한다. 플랫폼은 모든 이에게 열렸다.5
하지만 8월, 그는 시스템이 고품질 30~60초 비디오를 아직 안정적으로 제공하지 못한다고 인정했다. 소규모 상인들도 제한된 테스트 예산으로 수익 목표를 맞추기 어려웠다. 이에 경영진은 중견 브랜드에 집중하고 있다. 이는 병목 현상에 대한 회사 측 설명이지, 독립적으로 측정된 실패율이 아니다.4
현재 출시 체크리스트는 구매 추적 검증, 시스템 학습을 위한 충분한 전환 확보, 적응형 비디오 광고의 반복 테스트를 요구한다. 온라인 상점은 알고리즘이 가치를 입증하기 전에 자금, 소재, 관심을 투입해야 한다.6
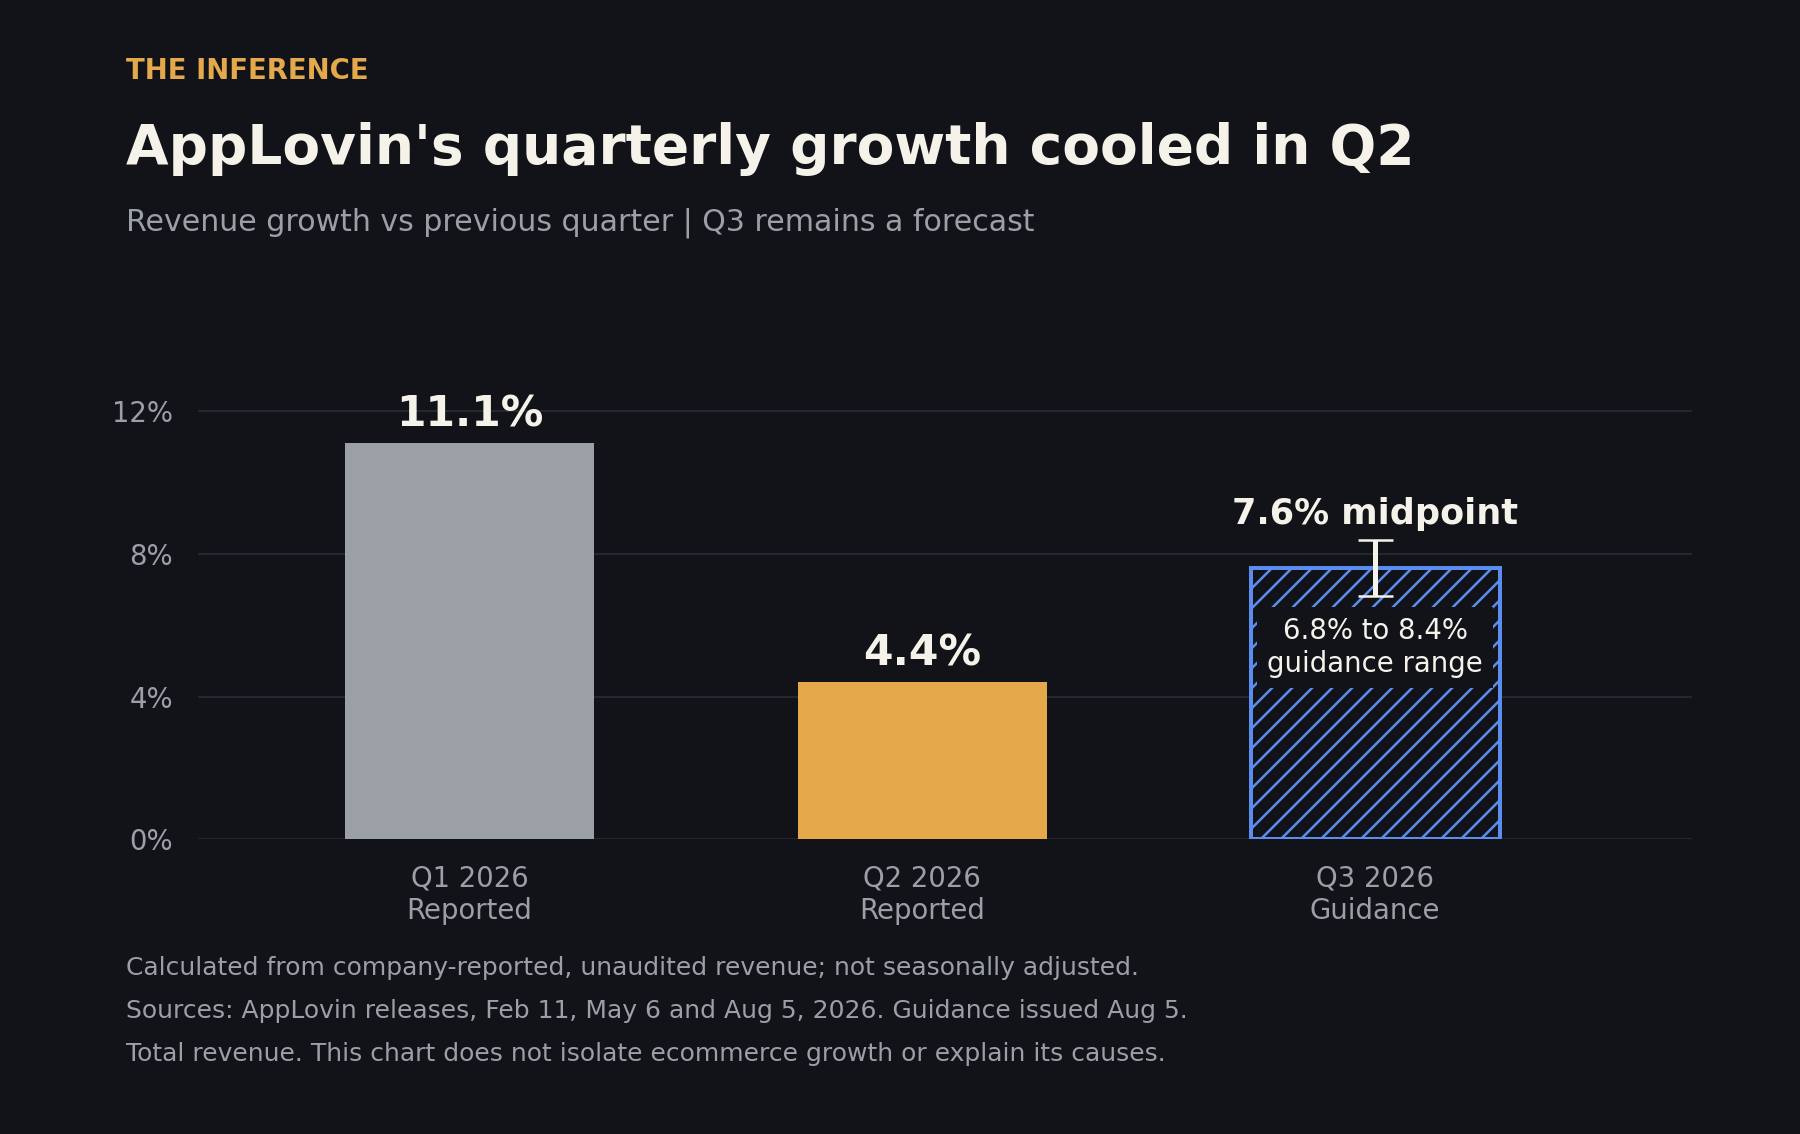
이는 확장 제약이다. 경영진은 Q2 성장 둔화를 주로 게임 모델 개선 시기 탓으로 돌렸다. 전체 둔화를 전자상거래 실패로 보는 것은 근거를 과장하는 것이다.4
AI 도입 비용에는 고객이 아직 해야 할 일이 포함된다.
강세 시나리오에는 증거가 있다
강세 시나리오에는 근거가 있다. 트리플 웨일의 9월 3일 보고서는 755개 앱러빈 지출 상점을 분석, 적격 상점의 61%에서 비교 채널 대비 높은 귀속 수익을 확인했다. 7개 지리적 홀드아웃 테스트 중 5개에서 긍정적이고 통계적으로 유의미한 수익 효과도 보고됐다.9
이는 앱러빈이 협력하는 측정 제공업체의 단일 출처 증거다. 캠페인이 결과를 낼 수 있다는 점을 뒷받침하지만, 소기업이 성공적으로 시작할 수 있는지는 여전히 미지수다.10
포루히 CEO의 다음 스코어보드는 가입, 캠페인 출시, 지속적 수익 지출을 연결해야 한다. 더 나은 창의 도구가 소규모 광고주가 외부 도움 없이 그 과정을 완료할 수 있게 하는지 주목할 필요가 있다.
신규 광고주 중 수익을 내며 지출을 유지하는 비율을 지켜봐야 한다.
How this brief was made
01Gathered & sourced307 channels · 1,871 articles▾
Agents swept 307 channels and ingested 1,871 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated10 claims · 12 data feeds▾
Every one of 10 load-bearing claims was checked against primary sources, with 12 live data feeds reconciling the figures and charts.
- 1AppLovin Q2 2026 financial results, Aug 5 2026 (company-claimed and unaudited primary disclosure: revenue of $1,923,686 thousand and Q3 guidance of $2,055M to $2,085M. The SEC copy is the same source, not a second one).
- 2AppLovin Q1 2026 financial results, May 6 2026 (company-claimed and unaudited: revenue of $1,842,449 thousand, used as a chart input).
- 3AppLovin Q4 2025 earnings exhibit, Feb 11 2026 (company-claimed and unaudited: revenue of $1,657,944 thousand, the denominator for Q1 sequential growth. Labelled unaudited, and distinct from the later audited annual statements).
- 4AppLovin Q2 2026 earnings call, Aug 5 2026 (management's own statements, read in a third-party transcription: the video-generation limitation, the focus on midsized brands, and the gaming-model explanation for slower growth. Audio was not independently transcribed).
- 5AppLovin's announcement opening the platform, Jun 22 2026 (company-claimed: the referral requirement removed and one-click creation described as an aspiration, not a completed capability. AppLovin Ads is the platform; Axon is the recommendation system).
- 6AppLovin launch checklist, accessed Sep 14 2026 (company product instructions establishing the remaining customer work: tracking, learning budget, creative adaptation and repeat testing. The video duration is guidance rather than an eligibility rule, and the documentation discloses no failure or churn rate).
- 7Morgan Stanley price-target cut to $450 from $650, Overweight retained, Sep 14 2026 (the action is corroborated across ratings trackers; the client note was not accessed, and an analyst's conclusion is not an operating result. It is a $200 reduction, not a $200 target).
- 8Evercore ISI price-target cut, reported Sep 1 2026 (single-source account of the firm describing its own historical ecommerce-spend estimates as too high; the underlying note was not accessed, and analyst estimates are not company disclosures).
- 9Triple Whale report on AppLovin advertisers, updated Sep 3 2026 (single-source provider research over a selected cohort of 755 shops: 61% of qualifying shops showed higher attributed ROAS, and five of seven geographic tests were positive and significant. Shared-channel attribution can double count credit, the tests do not all measure the same revenue, and the study does not measure signup failures).
- 10AdExchanger on AppLovin's ecommerce and consumer expansion, Aug 5 2026 (reporting of company statements; it confirms the Triple Whale relationship described on the call rather than independently verifying operating claims).
03Reviewed & edited1 human editor▾
One editor read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.