벤딩스푼스, 추락한 유니콘 사냥…성장 대부분은 '돈 주고 산 것'
벤딩스푼스(Bending Spoons)의 2026년 2분기 매출은 전년 동기 대비 126% 늘었다. 유기적 성장률은 3%였다. 미로(Miro)가 이 인수 모델의 다음 시험대다.
 Vincent Jiang · 2 min read
175억 달러에서 퇴장까지
안드레이 후시드가 창업한 미로는 2022년 1월 기업가치 175억 달러를 기록했다.1
벤딩스푼스와 맺은 9월 10일자 계약이 시사하는 지분가치는 약 17억9000만 달러로, 90% 가까이 낮아진 것이다.1,2
업무 흐름 속 자리를 사들이다
루카 페라리가 이끄는 벤딩스푼스는 8월 에어테이블 인수를 발표해 9월 4일 거래를 마쳤다. 미로는 이미 다른 업무용 도구 하나를 같은 소유주 아래 두게 한 인수에 이어지는 셈이다.3,4
미로는 약 6억 달러의 연간반복매출(ARR)을 올리고 있고, 이 가운데 거의 90%가 비즈니스·엔터프라이즈 고객에서 나온다. 이들 팀의 업무는 제품 안에 자리 잡고 있다. 덕분에 새 주인은 없었다면 직접 쌓아야 했을 고객 관계를 물려받는다.2
새 주인의 대가
페라리는 자기 팀이 실질적으로 개선할 수 있는 예측 가능한 비즈니스를 우선한다고 말한다.5
그런 변화는 아플 수 있다. 벤딩스푼스는 2024년 9월 위트랜스퍼 직원의 75%를 줄이는 계획을 세웠다.6 에버노트의 2025년 매출 성장은 구독자당 지출 증가에서 나왔고, 구독자 수 감소가 일부를 상쇄했다.10
이런 전례 탓에 미로의 직원과 고객은 통합 계획을 꼼꼼히 들여다봐야 할 이유가 있고, 경영진이 이들에 대해 들려주는 비용 이야기 역시 주의 깊게 읽어야 할 이유가 있다.
헤드라인 뒤의 성장
벤딩스푼스는 2026년 2분기 매출 7억400만 달러를 보고했다. 전년 동기 대비 126% 증가한 수치다. 유기적 매출 성장률은 3%였다.7,8
유기적 성장률은 같은 사업을 기간을 맞춰 비교해 구하며, 인수 이전의 추정 매출까지 포함한다. 사업을 더해 총매출이 뛰는 것보다 포트폴리오 내부의 성장을 가늠하는 더 나은 잣대다.7
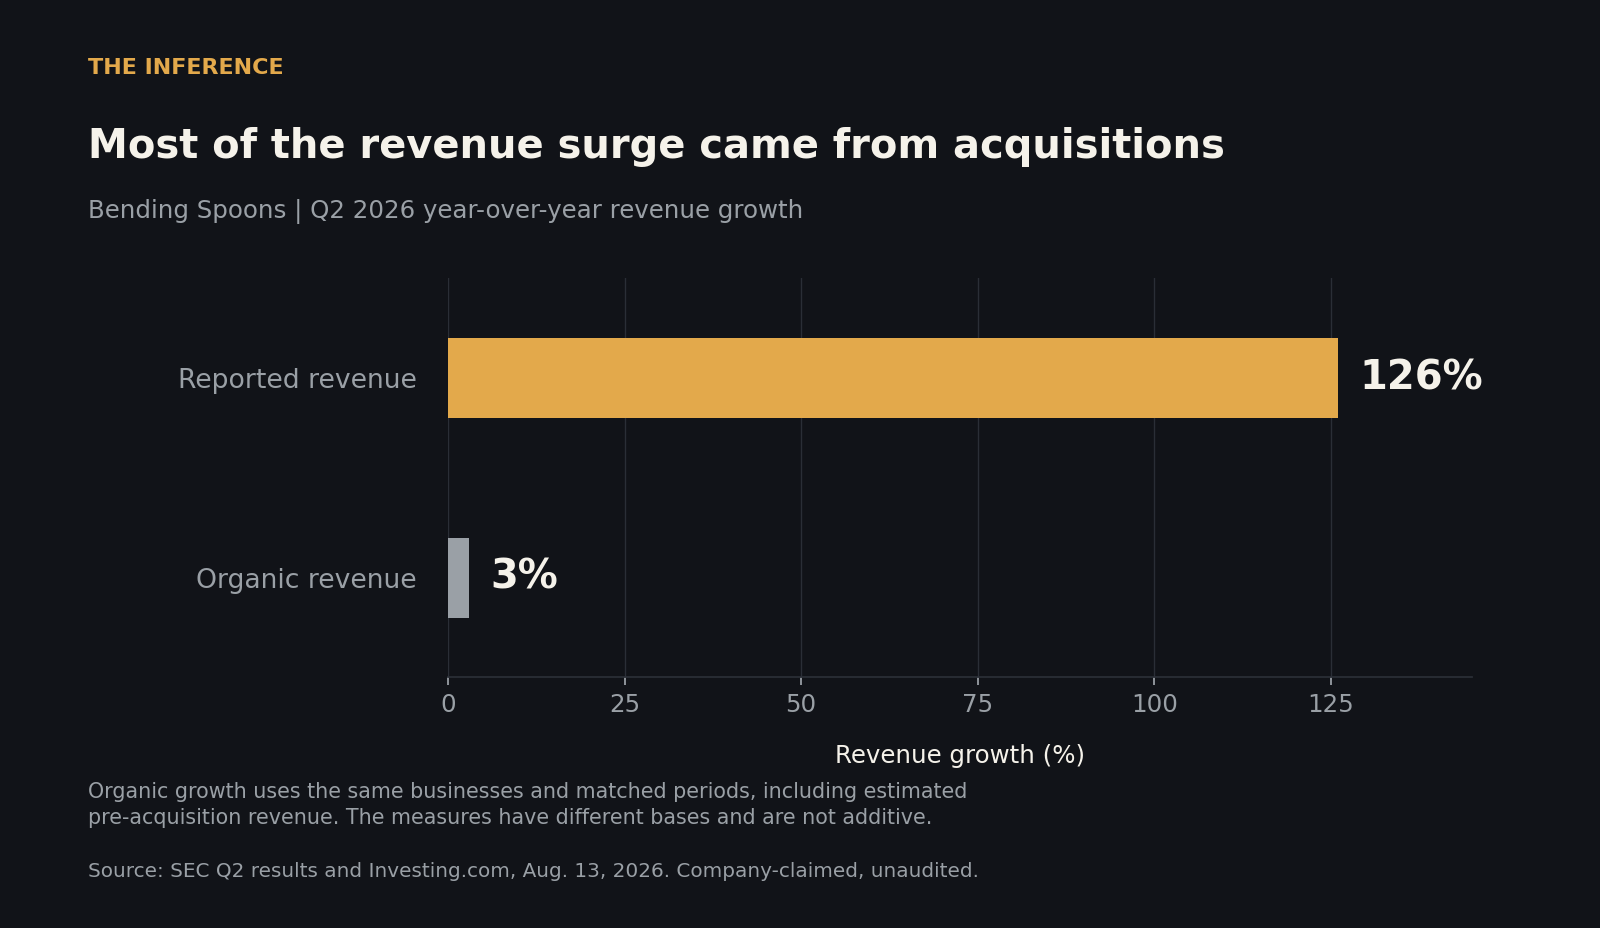
확장의 대부분은 인수가 차지한다. 그래서 새로운 인수 기회에 접근할 수 있는가, 인수한 기업을 통합해낼 수 있는가가 성장 스토리의 핵심이 된다.7,8
재건은 실재할 수 있다
페라리는 2분기에 AOL, 이벤트브라이트, 비미오에서 이뤄진 70건이 넘는 제품 개선을 언급했다. 벤딩스푼스는 또 2억4000만 달러의 영업이익을 기록했다고 밝혔다.7,9
더 나은 엔지니어링과 더 조인 비용은 쓸모 있는 소프트웨어를 지속시킬 수 있다. 풀리지 않은 문제는 소유주와 함께 고객이 얼마나 이득을 보느냐다.
첫 갱신을 주목하라
미로 인수는 승인 절차를 남겨두고 4분기에 종결될 것으로 예상된다. 이후 주목할 것은 가격 정책, 고객 유지율, 제품 안정성, 유기적 성장이다.2
다음 갱신이 시험대다. 벤딩스푼스가 산 것이 고객의 충성심인지, 아니면 고객이 떠나는 데 드는 비용에 불과한지가 드러난다.
How this brief was made
01Gathered & sourced228 channels · 1,367 articles▾
Agents swept 228 channels and ingested 1,367 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated10 claims · 35 data feeds▾
Every one of 10 load-bearing claims was checked against primary sources, with 35 live data feeds reconciling the figures and charts.
- 1TechCrunch report on Miro's $17.5B round, Jan 5 2022 (company-claimed valuation; historical round corroborated by SiliconANGLE).
- 2Dow Jones via MarketScreener on the Miro agreement, Sep 10 2026 (company-claimed ARR and customer mix; implied equity value includes net cash, and the Q4 closing remains conditional).
- 3Reuters via MarketScreener on the Airtable terms, Aug 4 2026 (the $1.285B enterprise value and roughly $2.25B implied equity value are different measures).
- 4SEC filing, Airtable closing announcement, Sep 4 2026 (primary record of completion; it does not restate final consideration).
- 5Axios interview with Luca Ferrari, Jul 1 2026 (single-source executive interview; management intent, not established product outcomes).
- 6TechCrunch on the WeTransfer restructuring, Sep 8 2024 (company-confirmed historical plan; no equivalent Miro cuts have been announced).
- 7SEC filing, Q2 2026 results and metric definitions, Aug 13 2026 (company-claimed and unaudited; a filing is not an SEC endorsement).
- 8Investing.com Q2 earnings coverage, Aug 13 2026 (editor-reviewed, AI-assisted report; figures checked against the filing, and its erroneous IPO-quarter description is excluded).
- 9The Motley Fool transcript of the Aug 13 earnings call, Aug 20 2026 (company-claimed product improvements from speaker text; no independent product audit).
- 10Forbes operating profile of Bending Spoons, Jul 1 2026 (reported price increases and company-claimed subscriber and revenue directions).
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.