CoreWeave Launches $3 Billion of Convertibles and Parks 35 Million Shares Behind It
The AI-cloud operator launched a $3.0 billion convertible due 2033 at an indicated 2.375–2.875% coupon and parked a 35 million-share equity program behind a 30-day lockout — the day after the Fed's first hike since 2023. The sequencing tells you which capital market CoreWeave still thinks is open, and who is being asked to fund it.
 Richard TangSeptember 18, 2026 · 4 min read
One CoreWeave filing this morning opens two doors. Through the first: $3.0 billion of convertible senior notes due April 1, 2033, with a $500 million option for initial buyers, indicated at a 2.375–2.875% coupon and a 22.5–27.5% conversion premium, pricing expected after tonight's close 123. Through the second: an equity distribution agreement with eleven banks to sell up to 35 million Class A shares — and a promise to the convert buyers that none of those shares move for at least 30 days after the notes' purchase agreement 1. I read the order as the point. CoreWeave is telling you which market it believes is still open to it, and it is not the straight credit market.
The day after the Fed, a different aisle
The timing makes that read hard to escape. On Wednesday the Federal Reserve raised rates for the first time since July 2023 — a unanimous 25 basis points to 3.75–4%, with the dot plot penciling in one more hike — and Chair Kevin Warsh volunteered that "the so-called hyperscalers are out in the market raising funding," calling that competition for capital one reason the 10-year Treasury sits near 5%, its highest since 2023 7. The morning after, CoreWeave skipped the aisle where its own outstanding senior notes cost 8.500% to 9.750% 2 and went to the one where buyers accept under 3% in cash.
That gap is the whole trade, and the buyer pays it knowingly. A convert holder at an indicated ~2.6% midpoint 3 is not lending on CoreWeave's credit; he is buying a call option on the stock roughly a quarter above today's price and taking token interest for the wait. CoreWeave's own deck models exactly this — a $3.5 billion convert at 2.625% dropping its weighted average interest rate from 8.3% at mid-year to 7.8% pro forma, on a debt stack that has already fallen from 14.9% in 2023, which the company says saved it about $1.1 billion of annualized interest from Q2 2025 to Q2 2026 3.
Dilution as credit-rating medicine
The equity door is the backup that is also the plan. At Wednesday's close the 35 million shares were worth about $2.92 billion 4; the banks take up to 2.0% of gross — on my arithmetic, near $58 million if the program sells out at that price 14. Even these future sales are hedged, through collared forward agreements with a floor below 100% and a cap above it 1. And the filing says the proceeds may go to "support of its objective of migrating its enterprise credit profile toward investment grade" 1. That is the honest sentence in the document: equity is the credit-rating medicine, dilution is the dosage, and the capped calls only lift the dilution wall so high before shareholders pay above the cap 2.
Six-and-a-half-year money against a four-year book
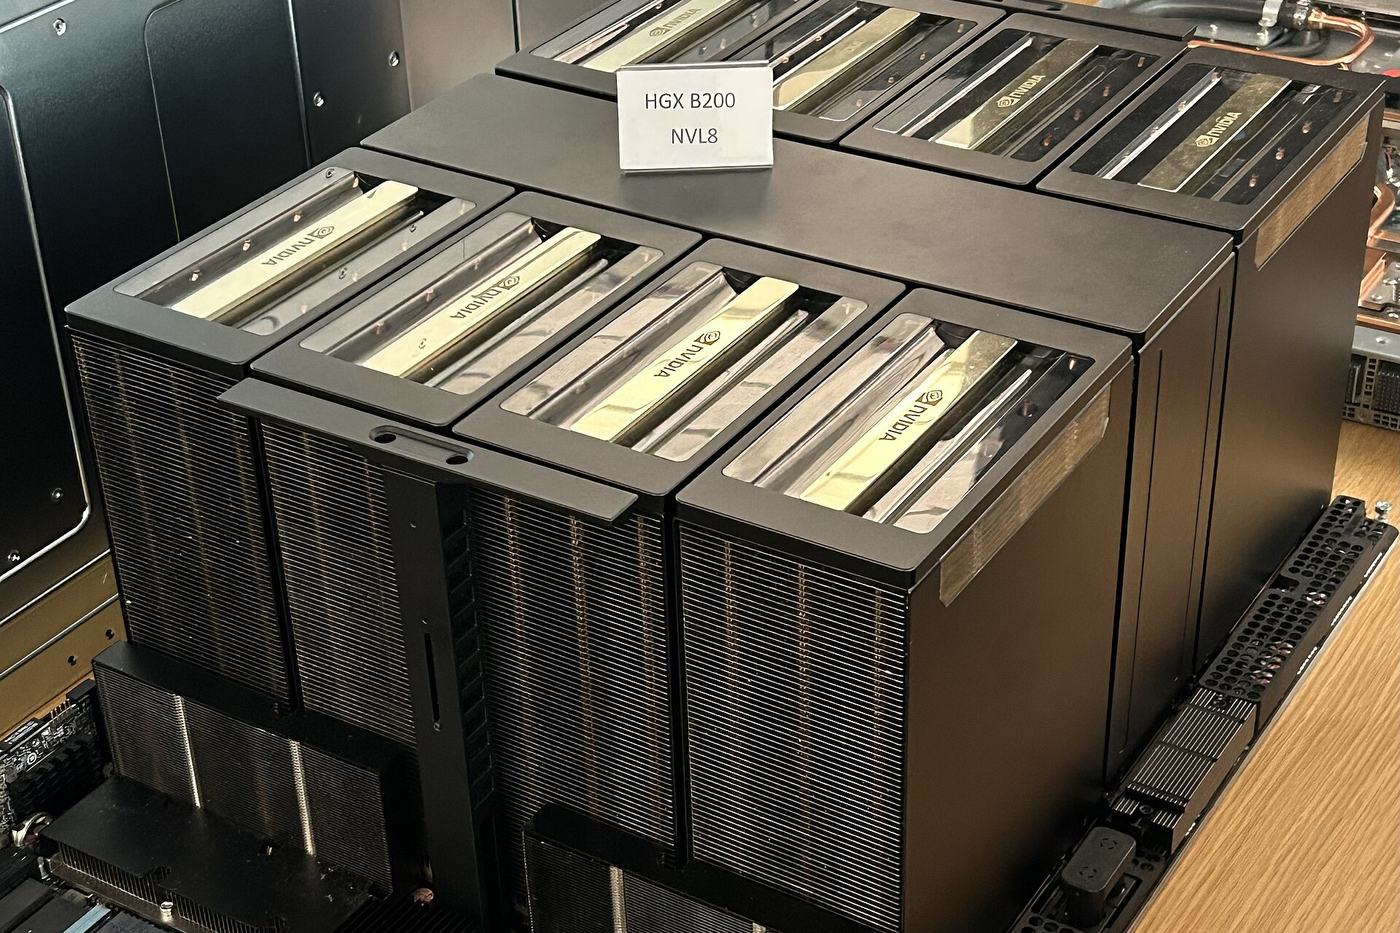
What the cheap money buys is time the contracts don't have. Revenue backlog was $104.2 billion at mid-year, up 246%, with $25 billion more signed early in Q3 and contracted power at 4.2 gigawatts; the newest short-dated deals, running three to six months, price around $40 million per megawatt annualized 345. But 21% of that backlog recognizes inside 24 months and another 39% inside 48; only 40% stretches past four years 3. The notes run six and a half years. Meanwhile Q2 interest expense was $640 million, Q3 is guided to $860–940 million, and 2026 capex to $35–39 billion 6. Convert buyers are the ones underwriting 2033 against a book that mostly turns over by 2030.
- Recognizes within 24 months21%21%
- Recognizes in 24–48 months39%39%
- Recognizes beyond 48 months40%40%
Data
| Slice | Value | Share |
|---|---|---|
| Recognizes within 24 months | 21% | 21% |
| Recognizes in 24–48 months | 39% | 39% |
| Recognizes beyond 48 months | 40% | 40% |
The market's first verdict was a shrug downward: shares near $80, off more than 4% on the day while the S&P rallied, 16% lower over the past week 6. The bottleneck for this company has not been demand for months. It is the cost of capital, and the decisive question is whether volatility and stock are permanently cheaper than credit. Watch two things: where the notes actually price tonight, and whether the ATM fires after day 30. My guess is CoreWeave hopes it never has to — that the convert prices well inside the indicated range and the equity door stays a threat it never uses. But it filed the machinery anyway, the day after the Fed said rates are going higher. Companies build backup doors when they are unsure of the main one.
How this brief was made
01Gathered & sourced208 channels · 1,122 articles▾
Agents swept 208 channels and ingested 1,122 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated7 claims · 23 data feeds▾
Every one of 7 load-bearing claims was checked against primary sources, with 23 live data feeds reconciling the figures and charts.
- 1CoreWeave, Inc. Form 8-K (Items 7.01, 8.01, 9.01), filed with the SEC, 17 September 2026
- 2CoreWeave press release, "CoreWeave Announces Proposed $3.0 Billion Convertible Senior Notes Offering" (Exhibit 99.1 to Form 8-K), 17 September 2026
- 3CoreWeave investor presentation for the convertible notes offering (Exhibit 99.2 to Form 8-K), 17 September 2026
- 4CNBC, "CoreWeave launches $3 billion convertible debt sale," 17 September 2026
- 5The Deep Dive, "CoreWeave Seeks $3B Debt, 35M-Share Sale as AI Compute Pricing Surges," 17 September 2026
- 624/7 Wall St., "Why CoreWeave Is Tumbling Hard While the Market Is Soaring," 17 September 2026
- 7Fox Business, "Federal Reserve hikes interest rates for first time since 2023 amid stubborn inflation," 16 September 2026
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.