Dell says 6,500 companies bought AI factories. Barclays says it is mostly memory prices.
Michael Dell gave the first customer count for AI factories: 6,500 enterprises, the base doubling in three quarters. Barclays calls the same quarter memory inflation, and the power layer below both is running short.
 Richard Tang · 3 min read
Michael Dell gave the first count of enterprises buying his "AI factory" systems this week: the customer base doubled in three quarters. Barclays+0.79% — Barclays, up 0.79 percent today looked at the same quarter and called the growth largely memory-price inflation. Both cannot fully hold, and the shape of Dell's revenue says the demand is real.
The customer base doubled in three quarters
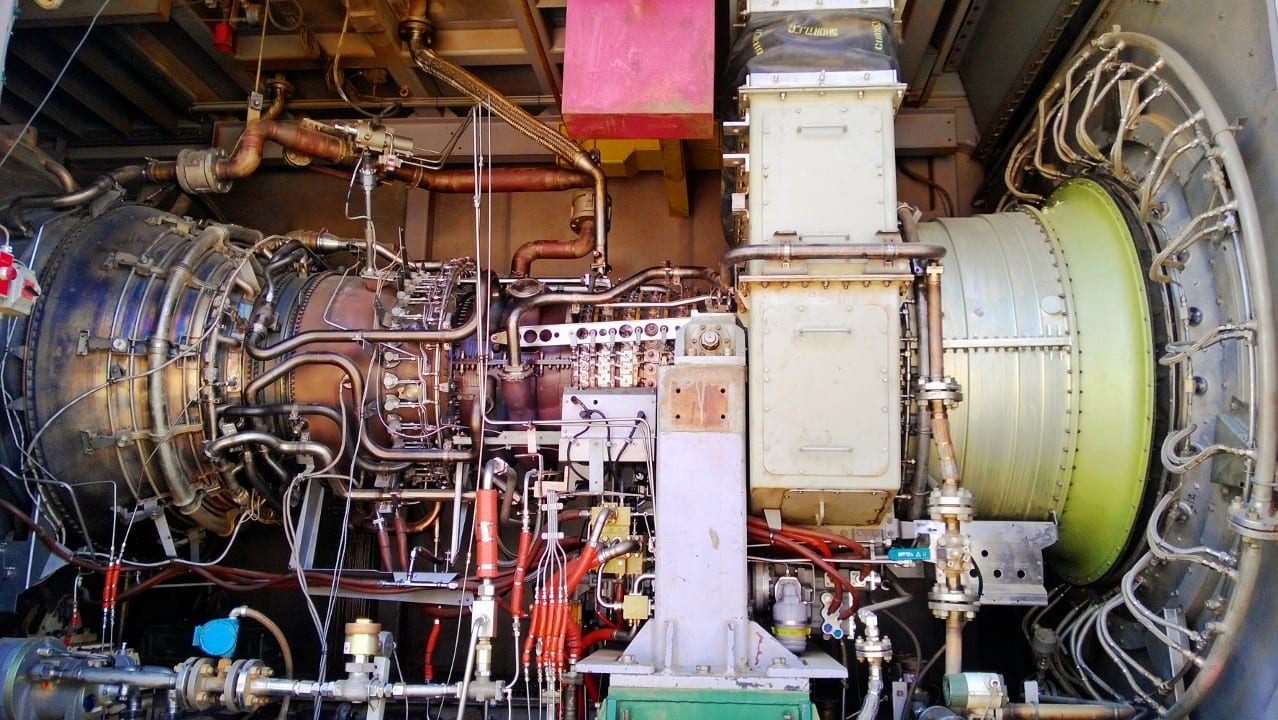
Michael Dell, Dell Technologies'+1.70% — Dell Technologies, up 1.70 percent today founder and CEO, told the Wall Street Journal it took eight quarters to sign 3,200 companies for private AI factory deployments, then only the last three quarters to add 3,300 more, reaching 6,500 in total 1. The product is physical: a box about six feet tall and 3,000 pounds, drawing as much power as 100 to 300 US households, selling for around six figures 1. Dell cites delivery speed as proof it can execute: half the servers for SpaceX's−0.61% — SpaceX, down 0.61 percent today Colossus AI supercomputer, built in about six weeks against a typical six-month timeline 1. His read, per the interview, is that enterprises want AI inference close to their own data, inside plants and offices, and that adoption is still in its "early stages" 1.
Barclays reads the same quarter as memory inflation
Barclays cut Dell to Equal Weight on October 14, writing that strong enterprise revenues are "more of a function of memory costs" than a move to enterprise AI, with businesses allocating only about 5% of IT budgets to AI and about a quarter of that to hardware 2. Dell's operating chief Jeff Clarke conceded "there's a notion of inflation inside our growth" 8. Barclays analyst Tim Long expects Dell's AI server revenue to roughly triple to $75 billion this year at roughly 5% margins, then decelerate as memory prices normalize 10. Either the signed demand is real or the revenue rise is memory passed through; Long's own model concedes the demand exists. And the quarterly revenue curve is hard to explain with parts prices alone: flat near $23 billion for two years, then $33.8 billion, $43.8 billion and $46.97 billion in the three quarters to July 2026, with AI orders a record $60.9 billion and a $95 billion backlog 7.
Dell's revenue ran flat for two years, then stepped up sharply
Data
| Quarterly revenue | |
|---|---|
| Q3 '23 | 22.25B |
| Q4 '23 | 22.32B |
| Q1 '24 | 22.24B |
| Q2 '24 | 25.03B |
| Q3 '24 | 24.37B |
| Q4 '24 | 23.93B |
| Q1 '25 | 23.38B |
| Q2 '25 | 29.78B |
| Q3 '25 | 27.01B |
| Q4 '25 | 33.38B |
| Q1 '26 | 43.84B |
| Q2 '26 | 46.97B |
The constraint moved down to power and memory
Both camps agree the bottleneck is no longer chips. Dell expects the memory shortage to worsen through 2027, with new fabs producing only from 2029, and has said the crunch could run to 2030 14. Barclays extended its peak-cycle call on October 20 to the power layer: vendors of transformers and switchgear face pricing pressure as AI labs consolidate and haggle 5. That layer sits in Dell's supply chain. Delta Electronics, a Taiwan-based power-supplies maker selling into AI data centers, warned on October 16 of a 19-gigawatt shortfall in US power for AI data centers by 2028, meaning the grid cannot feed boxes already ordered 6. A backlog that cannot be powered or populated is revenue deferred, not revenue booked.
Margins climbed through the ramp, a signal the demand is not only memory
Data
| Operating margin | |
|---|---|
| Q3 '23 | 6.7% |
| Q4 '23 | 7.6% |
| Q1 '24 | 4.3% |
| Q2 '24 | 5.6% |
| Q3 '24 | 7.1% |
| Q4 '24 | 9% |
| Q1 '25 | 5% |
| Q2 '25 | 6% |
| Q3 '25 | 7.8% |
| Q4 '25 | 9.3% |
| Q1 '26 | 8.3% |
| Q2 '26 | 11.5% |
Wall Street still rates Dell a Moderate Buy with a mean target near $600, above the post-selloff price 12. The number that decides the dispute is the operating margin in the November 23 report: memory inflation flatters revenue, but only real AI demand keeps margins climbing 3.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.