Index funds carry AXT's 425% run; Beijing gates the order book
BlackRock's October 5 filing puts 14.3% of AXT in passive hands, one S&P small-cap fund above 5% on its own. Customers have paid real cash up front, but every shipment out of China waits on a Beijing permit, and the first test lands on October 29.
 Vincent Jiang · 3 min read
Passive money owns the register
BlackRock reported 9,359,639 shares of AXT on October 5, 14.3% of the company as of September 30, in a Schedule 13G/A that certifies the stock was not acquired to influence control 1. Inside that number sits iShares Core S&P Small-Cap ETF, alone above 5% of AXT, more than a third of BlackRock's stake 1. That is index plumbing, not a view on indium phosphide. It is what S&P's September 21 addition of AXT to the SmallCap 600 does to a register: trackers must buy, and the stock rose as much as 16.4% that day 2.
Fast money stacked on top
The trading around the stock matches the run. Tradr announced a 2X short AXTI daily ETF on August 13 for sophisticated traders; the stock has swung from $3.70 to $143.16 in a year 3. Retail is calling for $95 4. Hedge funds fell to 33 holders from 37, while the survivors lifted committed capital 34% to $487.9 million 2. After a 425.2% rise this year 8, the buyer still accumulating at scale is the index machine.
The cash customers actually paid
The demand story does hold dollars. In the second quarter AXT received prepayments of $22.3 million and $25.4 million from Coherent and Casela; in July Lumentum signed a six-year capacity reservation, $43.5 million due within 30 business days and a second $43.5 million whose terms settle in 2028, terms The Inference traced on October 1 567. InP backlog runs well over $100 million into 2027 5. But each deposit posts as a liability and becomes revenue only when wafers ship 5.
Customers have paid AXT more up front than its record quarter earned
- Estimate
Data
| Value | |
|---|---|
| Coherent (Q2 prepayment) | $22.3M |
| Casela (Q2 prepayment) | $25.4M |
| Lumentum (2026 deposit) | $43.5M |
| Lumentum (2028, contemplated) (estimate) | $43.5M |
One permit from revenue
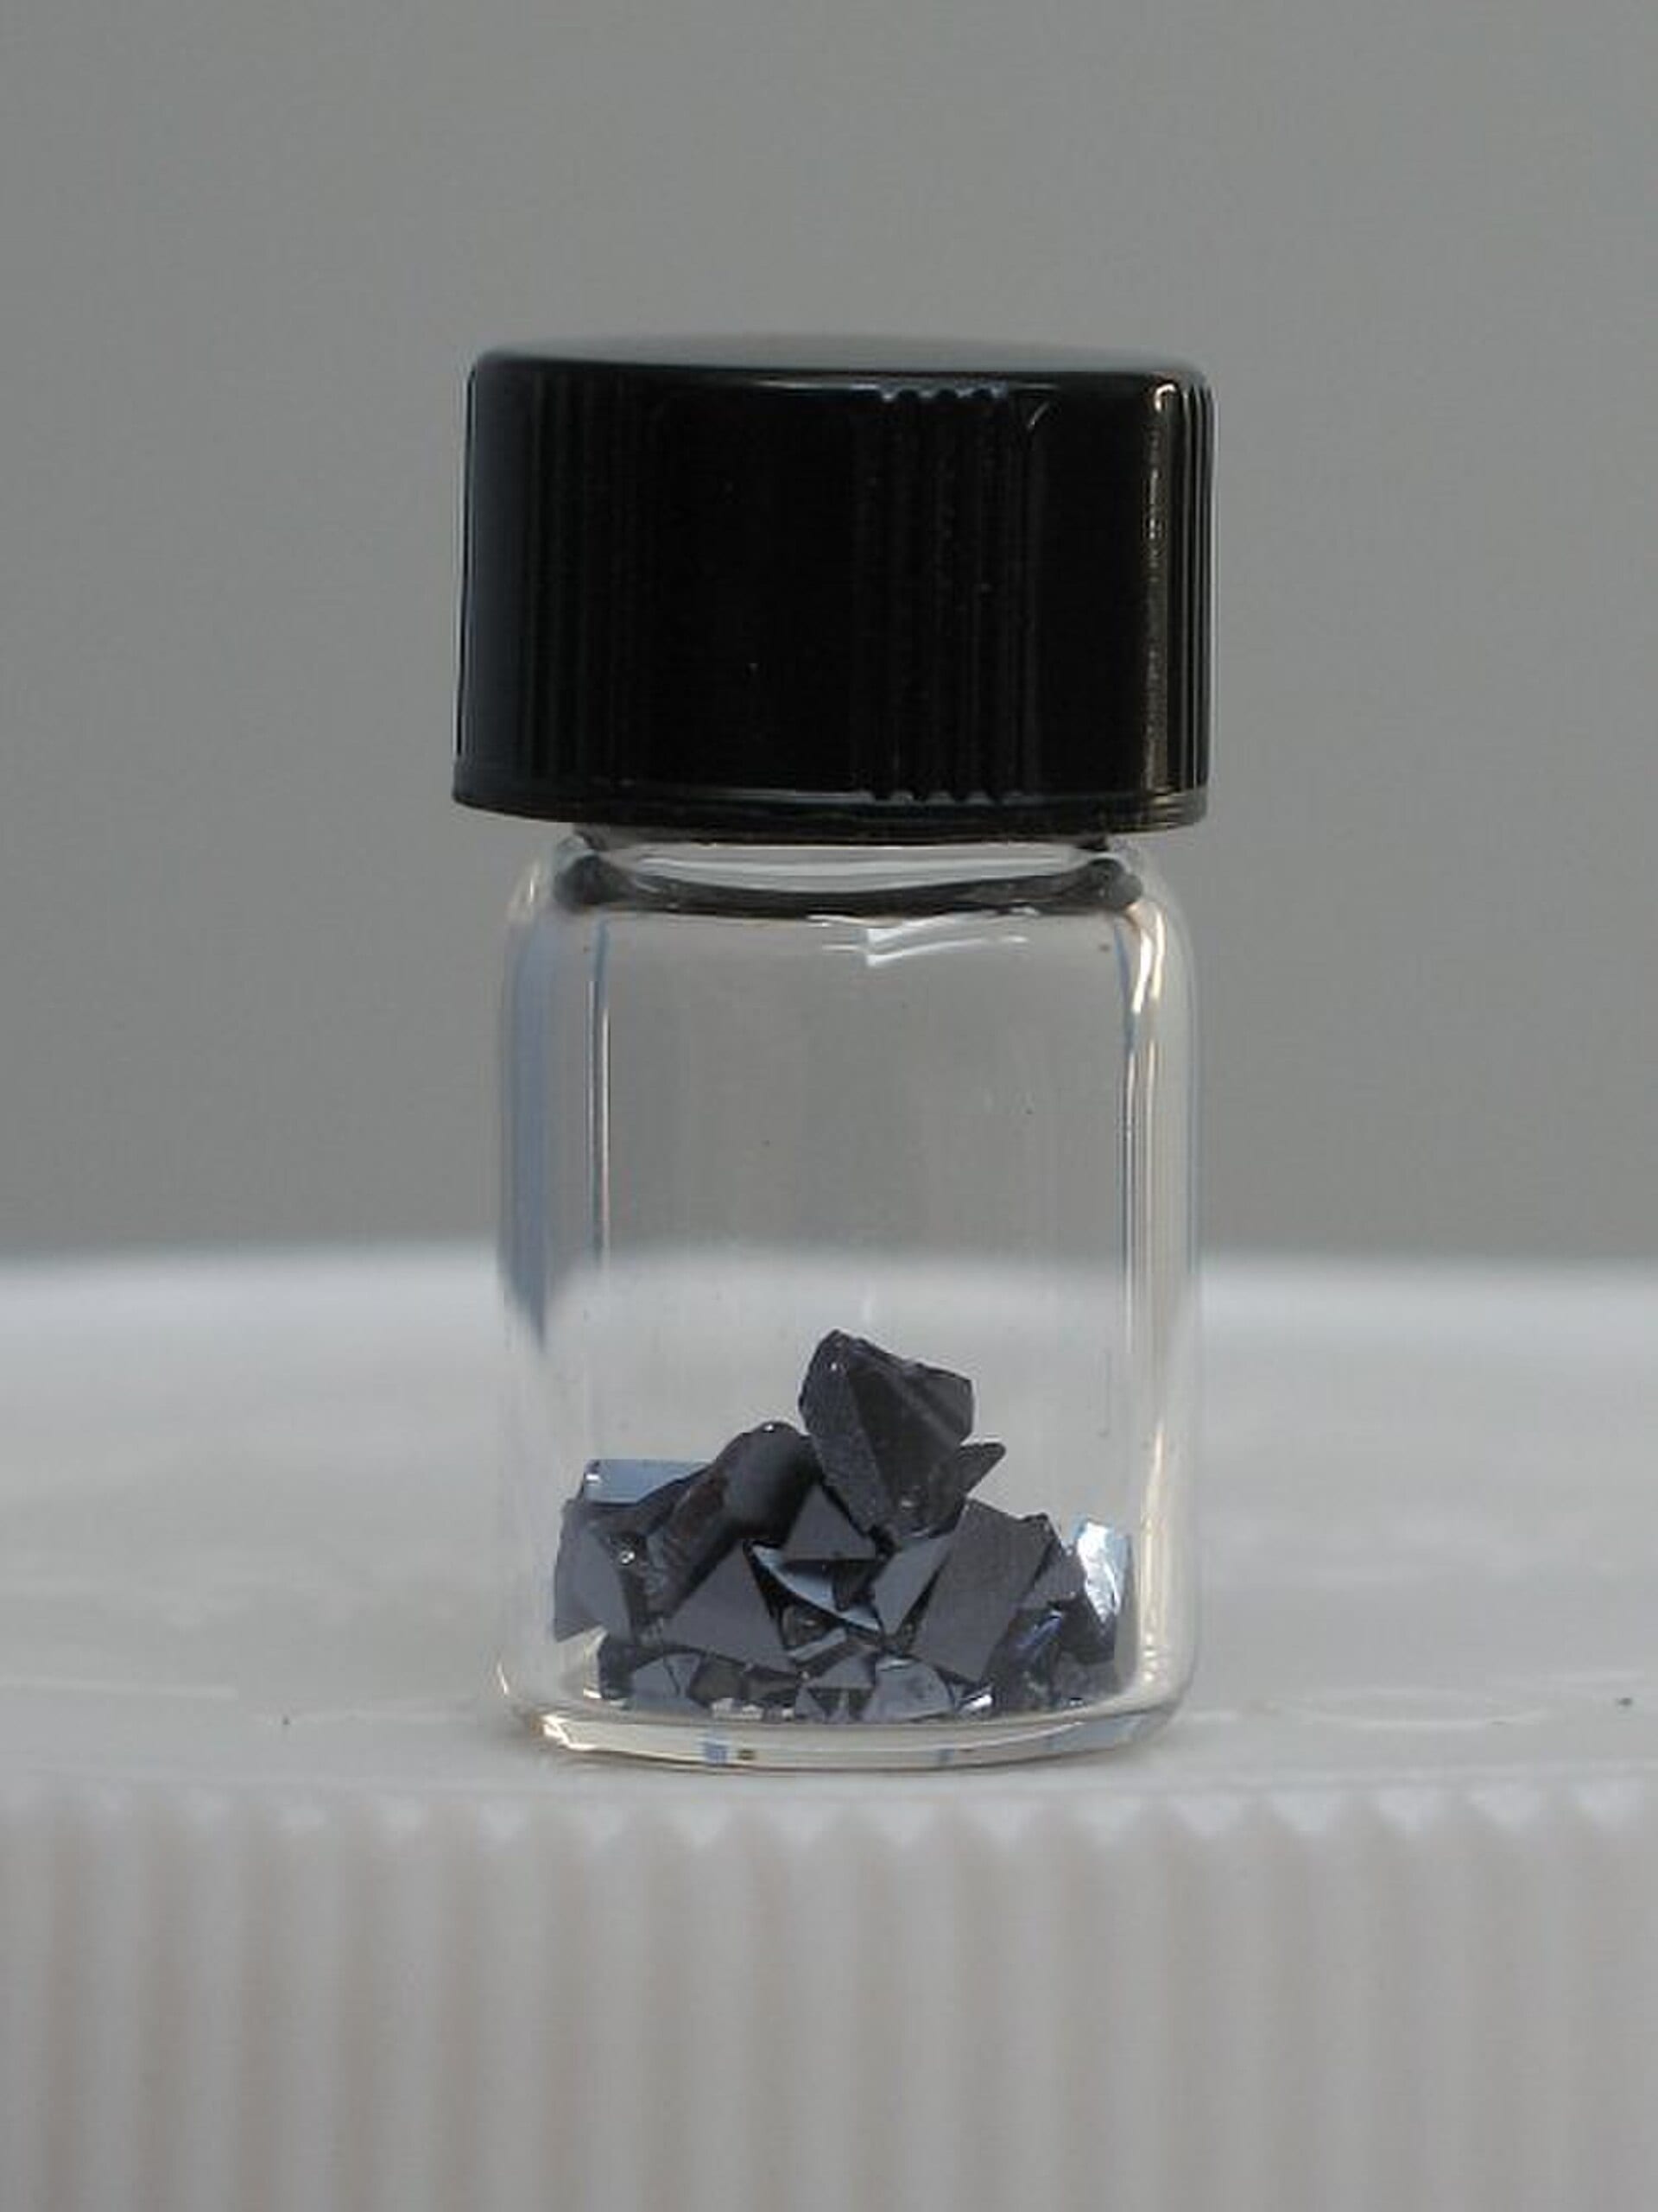
All of AXT's substrates are grown at three plants in China, and every shipment leaving the country needs a Ministry of Commerce license, under controls in force since February 4, 2025, and never suspended 67. In a August 13 filing AXT called permits its most significant challenge and said it could not estimate when U.S. approvals would arrive, after a January outlook cut followed a permit shortfall 6. The $66 million third-quarter guide counts only revenue already permitted or exempt, and China, over half of second-quarter sales, needs no permit at all 5. The deposits are dollars; the revenue is paperwork.
Who pays at 14 times sales
At 14.19x forward sales against a 5.25x industry average, a Value Score of F and a Hold rank 8, the stock is a re-rating standing on one record quarter after three flat years.
A 425% re-rating built on one record quarter
Data
| Revenue | |
|---|---|
| Q3 '23 | $17.37M |
| Q4 '23 | $20.43M |
| Q1 '24 | $22.69M |
| Q2 '24 | $27.92M |
| Q3 '24 | $23.65M |
| Q4 '24 | $25.11M |
| Q1 '25 | $19.36M |
| Q2 '25 | $17.97M |
| Q3 '25 | $27.96M |
| Q4 '25 | $23.04M |
| Q1 '26 | $26.92M |
| Q2 '26 | $47.59M |
October 29 is the first real test
The bull case is real: gross margin went from 8% to 44.9% in a year, the InP capacity doubling runs ahead of schedule, and consensus sees 146.4% revenue growth in 2026 58. What the multiple adds is the assumption that permits keep arriving, which management says it cannot predict 5. AXT itself sold $632 million of stock on April 22 and ended June with $748.8 million of cash 5. The next reading lands after the close on October 29: revenue against the $66 million already permitted, and the first conversion of customer deposits into shipped wafers 10.
Gross margin went from 8% to 44.9% in a year
Data
| Gross margin | |
|---|---|
| Q3 '23 | 10.7% |
| Q4 '23 | 22.6% |
| Q1 '24 | 26.9% |
| Q2 '24 | 27.4% |
| Q3 '24 | 24% |
| Q4 '24 | 17.6% |
| Q1 '25 | -6.4% |
| Q2 '25 | 8% |
| Q3 '25 | 22.3% |
| Q4 '25 | 20.9% |
| Q1 '26 | 29.6% |
| Q2 '26 | 44.9% |
Deepdive
AI-generated from this story and its cited sources. Not investment advice.