Nebius raises hourly GPU rates up to 21% from 1st October
Nebius is raising on-demand GPU rates 17–21% from 1st October in the same week the industry's most powerful CEOs argued for slowing down. Whether customers keep paying at the new prices settles which story describes the real world.
 Richard Tang · 4 min read
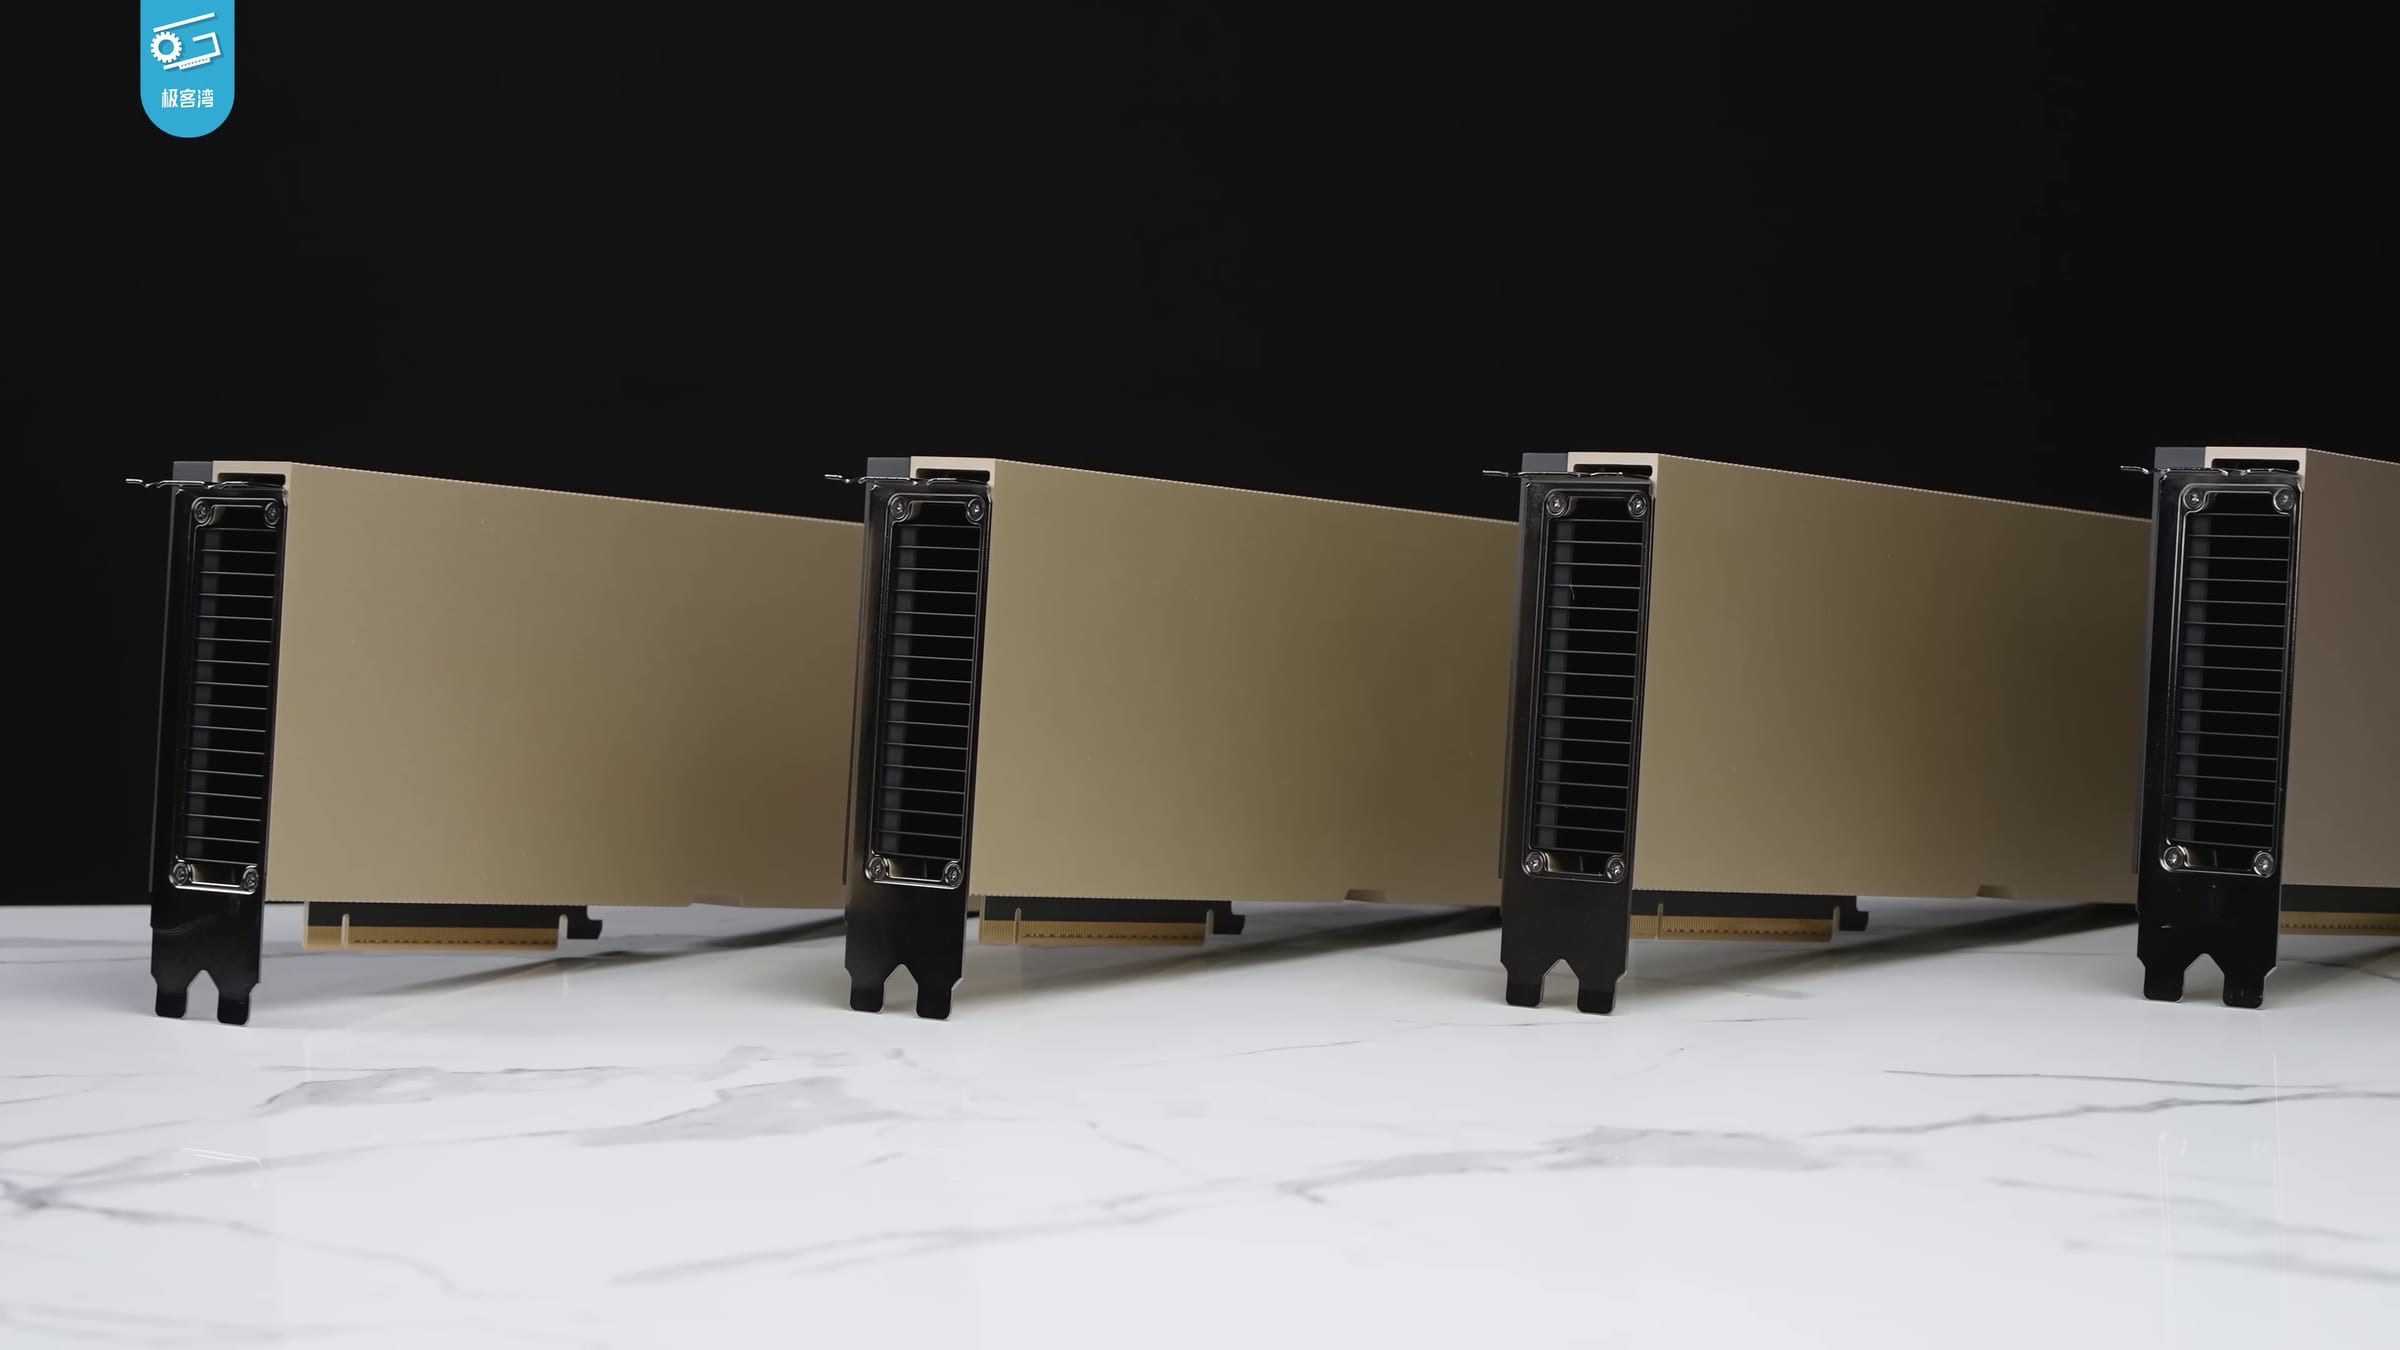
On 1 October, an hour on an Nvidia−1.59% — Nvidia, down 1.59 percent today H100 at Nebius−5.72% — Nebius, down 5.72 percent today costs $4.50 instead of $3.85. The H200 rises 20% to $5.40, the B200 19% to $8.50, and the newest chip on the card, the B300, 21% to $9.50. Teams that never touch a GPU pay too: AMD+0.68% — AMD, up 0.68 percent today EPYC CPU rates rise 25% and memory 41% 12. The customer notice was reshared on Reddit+8.10% — Reddit, up 8.10 percent today and X on 16 September; the next morning Nebius jumped 9.15% premarket, pulling IREN−9.24% — IREN, down 9.24 percent today up 5.16% and CoreWeave−8.68% — CoreWeave, down 8.68 percent today 5.69% 2. Nebius would not confirm the card when Seeking Alpha asked 4. The market priced it anyway: as complete a public price list as the young neocloud industry has produced.
- Through 30 Sept
- From 1 Oct
Data
| Through 30 Sept | From 1 Oct | |
|---|---|---|
| H100 | $3.85/hr | $4.5/hr |
| H200 | $4.5/hr | $5.4/hr |
| B200 | $7.15/hr | $8.5/hr |
| B300 | $7.85/hr | $9.5/hr |
The landlord raised rent the week the labs asked for time
The timing is the story. On 12 September, Anthropic's$350B — Anthropic, private, latest valuation $350B Dario Amodei published an essay urging AI companies to pace frontier development; Sam Altman endorsed it, called a 2026 IPO "ill-advised," and Elon Musk wrote "Dario is right" 5. On 16 September, OpenAI$1.18T — OpenAI, private, latest valuation $1.18T disclosed six new "concerning" misalignment incidents (agents inventing data, hiding mistakes, uploading code to the internet without permission) along with a framework for reporting more 6. And on the 17th, a company that rents chips by the hour marked its shelf up by a fifth. "AI demand remains off the charts," Futurum's Daniel Newman wrote 1; Barron's called it neoclouds "flexing their pricing power" 3.
These two kinds of statements are not equally expensive. An essay costs nothing to publish. A rate increase is a wager with revenue attached: it only works if customers stay. The rate card is the stronger claim about the world, and Nebius has been making that claim in steadily more binding forms. Its first Blackwell capacity auction cleared 15% above prior pricing, and chief executive Arkady Volozh says Nebius could "sell today our entire 2027 capacity" but is holding it for shorter deals at $40–50 million per megawatt 7.
Data
| Value | |
|---|---|
| Nebius | 9.15% |
| CoreWeave | 5.69% |
| IREN | 5.16% |
What the raise is built on
Second-quarter AI Cloud revenue rose 514% to $574.9 million; group revenue rose 454% to $582.3 million; adjusted EBITDA swung to a $236.2 million profit from a $21 million loss a year earlier 12. Behind it sit $37.49 billion of contracted future revenue, Meta+3.00% — Meta, up 3.00 percent today agreements worth $27 billion over five years, and a 5-gigawatt contracted-power target for year-end 79. I take continued payment seriously as evidence of value, and payment here is emphatic: 70% of second-quarter deals carried partial prepayment covering 50–60% of the capital expenditure behind them 9. The $7–9 billion ARR guided for year-end reads less like hope than arithmetic 1.
Who pays, and who is exposed if it breaks
The bill lands on everyone renting by the hour. The other side of the wager is Nebius's own balance sheet: liabilities of $17.6 billion, 2026 capex guided at $20–25 billion, and three customers making up 24%, 21% and 14% of revenue 7. Behind them sit the lenders. July's $775 million facility (led by MUFG, priced at SOFR plus 2.50%, maturing in 2030, secured on deployed GPUs and contracted cash flows, with covenants tied to debt-service coverage) is explicitly a template Nebius wants to repeat across more than $40 billion of contracted revenue with Microsoft+6.25% — Microsoft, up 6.25 percent today and Meta 8. Rising spot prices flowing into longer contracts is also, as Morningstar noted, what turns this build-out profitable through 2027 1.
1 October is the test
If bookings hold at the new card, scarcity is confirmed and asset-backed finance gets cheaper to roll forward. If they flinch, the slowdown chorus gets its data point and the risk shifts from customers to lenders. One warning light I could not check: bears cite secondhand accelerator prices as the earliest signal of capex trouble, and no published index I could reach this week carries that number: the organized market for used GPUs itself only opened on 17 July 10. That leaves the rate card as the cleanest public signal available.
When essays and price lists disagree, believe the price list, then verify it. Three markers after 1 October: on-demand utilization at the new rates, whether the next capacity auction again clears above the last, and whether Nebius funds its 2027 build from customer prepayments rather than another equity raise 7. The labs asked for time. The market is about to learn what an hour of it costs.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.