Altman and Amodei Want More Time. These companies have to pay for it
CoreWeave, Nebius, IREN and WhiteFiber have capacity to build and customers to serve. A slower frontier could protect software incumbents while testing the financing behind the AI cloud boom.
 Vincent Jiang · 5 min read
The founders ask for breathing room
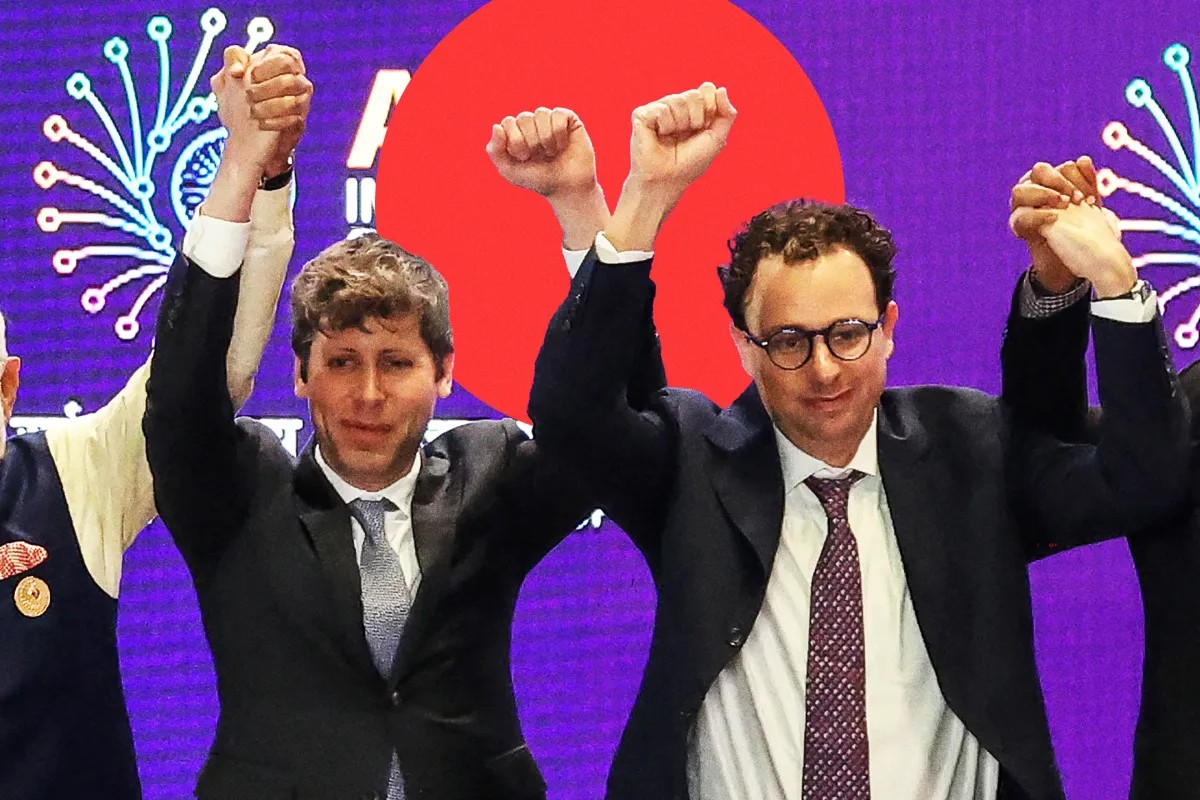
Sam Altman and Dario Amodei want more time before building more powerful AI. For investors financing the machinery, more time can mean more interest.
Validated: On September 12, Amodei proposed slowing frontier capability gains and admitting permanent outside evaluators. Altman backed the proposal on X and pledged comparable access at OpenAI$500B — OpenAI, private, latest valuation $500B. Elon Musk also endorsed Amodei's position.1,2
Analysis: The clearest potential beneficiaries are established software vendors. The most exposed business model is the neocloud: a specialist renting computing capacity whose expansion requires financing before revenue arrives. CoreWeave−9.27% — CoreWeave, down 9.27 percent today, Nebius−9.45% — Nebius, down 9.45 percent today, IREN−7.96% — IREN, down 7.96 percent today and WhiteFiber−8.13% — WhiteFiber, down 8.13 percent today face that timing problem, with different financial cushions.
The market starts sorting the bill
Validated: During September 14 trading, chip stocks fell while software shares rallied. Oil and interest-rate worries also weighed on markets, so the session cannot isolate the slowdown's effect.3,4
The investment distinction: slowing improvements in intelligence versus slowing purchases of computing capacity. Those can happen together. Neither guarantees the other.
Running existing models for customers, known as inference, could keep growing while frontier researchers spend longer testing successors. That would favor a different mix of AI spending, with less urgency around ever larger training runs and more emphasis on reliable deployment. This is a scenario, not an announced spending cut.
What X agreed to, and what it did not
Primary record: Amodei explicitly excludes a blanket training halt. Anthropic's$350B — Anthropic, private, latest valuation $350B immediate pledge concerns embedded evaluators; industry coordination and international agreements remain proposed next steps. Possible limits on training compute are subjects for negotiation.1
His warning about rogue agents potentially overrunning the internet within six to twelve months is a forecast, not an established timetable.1
The commercial inference is uncomfortable: rules that slow challengers and raise compliance costs can protect today's leading labs. That does not establish an improper motive. David Sacks has challenged the demand for government-enabled coordination; his cartel characterization is an accusation, not a legal finding.5
Altman's subsequent clarification that pacing does not mean stopping makes the boundary essential. The public endorsements establish agreement on direction, not an enforceable global spending freeze.6
The stocks with time to gain, and bills to pay
Scenario analysis: These are relative business exposures if meaningful pacing occurs, not price targets or claims that the stocks are cheap.
| Stocks | Potential effect | What could overturn it |
|---|---|---|
| Salesforce (CRM), ServiceNow (NOW), Adobe+0.68% — Adobe, up 0.68 percent today (ADBE) | The clearest reprieve: more time to retain customers, integrate AI and defend subscription pricing before stronger agents can replace existing workflows. | Today's models may already be capable enough to disrupt them. Slower progress could also weaken their own AI products.17 |
| CrowdStrike (CRWD), Palo Alto Networks (PANW) | Potential additional security spending as businesses harden networks and police agent access. | Model alignment research does not automatically become endpoint or firewall revenue. Contract growth must confirm the story.7 |
| CoreWeave (CRWV) | Direct exposure if weaker future GPU rentals collide with capital commitments and substantial interest expense.10 | Existing contracts and inference demand can sustain utilization.8,9 |
| Nebius (NBIS) | Rapid expansion makes the timing of new capacity, billing and customer payments critical.11 | Expected customer prepayments and contracted demand can finance part of the buildout.11 |
| IREN (IREN), WhiteFiber (WYFI) | The next round of GPU deployments could face weaker bookings or less attractive financing.20,22 | IREN reports largely sold-out 2026 capacity; WhiteFiber has multiyear cloud agreements.20,22 |
| Nvidia−3.89% — Nvidia, down 3.89 percent today (NVDA), Broadcom−5.24% — Broadcom, down 5.24 percent today (AVGO), Vertiv (VRT) | Exposed if customers cut accelerator, networking, power or cooling orders.15,16 | Safety work and inference still need infrastructure. Nvidia's data-center sales cannot all be classified as frontier training.12 |
| Alphabet−0.82% — Alphabet, down 0.82 percent today (GOOGL), Microsoft−1.38% — Microsoft, down 1.38 percent today (MSFT) | Possible cash-flow relief if lower capital spending preserves existing revenue. | They also sell cloud capacity and AI products. Lost growth or idle infrastructure could outweigh the savings. |
| SoftBank Group (9984.T) | A separate risk: Altman ruled out a 2026 OpenAI IPO, delaying a potential liquidity event for an investor in the company.4,18 | A deferred listing does not establish that OpenAI's underlying value has fallen. |
The neoclouds have their own clocks
CoreWeave supplies the clearest evidence of the financing burden. Its company-reported, unaudited results for the quarter ended June 30 show approximately $9.4 billion in capital spending against $2.58 billion in revenue, about 3.6 times as much.8,9
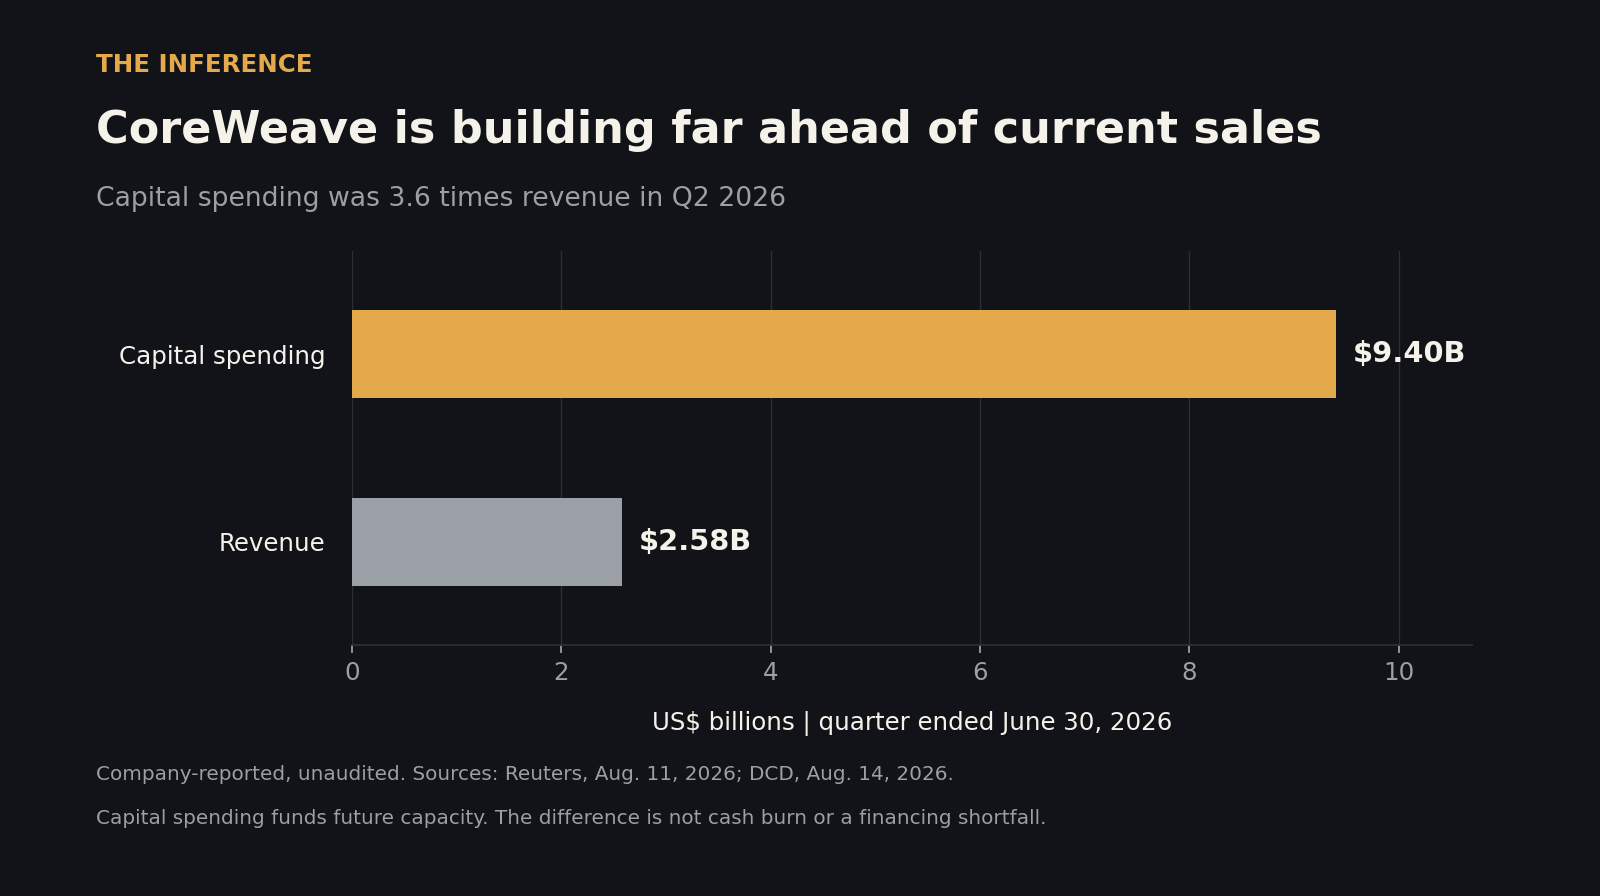
Its quarterly net interest expense was $640 million, roughly 25% of revenue, according to its unaudited filing. That is an expense comparison, not a debt-service coverage ratio.10,14
The inference: fewer future bookings can hurt equity long before existing contracts disappear. This extends our earlier examination of CoreWeave's financing burden.
Nebius is building ahead of revenue. Its unaudited June-quarter figures show roughly $5.7 billion in capital spending against $582.3 million in revenue, approximately ten times quarterly sales. That measures investment relative to current sales, not cash burn or insolvency risk.11,19
Data
| Value | |
|---|---|
| CoreWeave | 3.6x |
| Nebius | ~10x |
The cushion matters: Nebius said in August that it expected more than $9 billion in customer prepayments during 2026 and had more than $40 billion in customer commitments. Expected prepayments are not cash already collected.11 The bear case requires a deterioration in new contracts, payment timing or future rental economics. A slower frontier could still leave Nebius busy serving existing models.
IREN is financing a new business. The company is shifting from bitcoin mining toward AI cloud services. Reuters reported on August 28 that it secured $2.8 billion in new financing for AI chip purchases and signed a multiyear deal with an unnamed frontier lab. IREN said its 2026 compute capacity was largely sold out.20,21 The exposed variable is demand for subsequent capacity: weaker bookings could make the next expansion harder to finance, even while existing customers keep paying.
WhiteFiber must turn contracts into billable capacity. The GPU-cloud and colocation provider reported in August more than $540 million in new multiyear cloud agreements since May, with some deployments targeting 2027.22,23 These are contract values spread across years, not current revenue. Its August filing described outstanding financing and delivery milestones.23 Signed demand offers protection; weaker future rental demand could still undermine the economics of further expansion.
The shared risk is spending committed before revenue arrives. CoreWeave's interest expense makes that burden especially visible; the other names require their own assessments of funding, delivery and customer payments.
The strongest case against the selloff
The safety rationale deserves its full weight: Amodei argues safeguards are falling behind capabilities. Avoiding a serious failure could preserve customer trust and the industry's ability to operate. His proposal also acknowledges the difficulty of slowing without losing ground to China.1
And the infrastructure defense has receipts. CoreWeave reported a $104.2 billion backlog at June 30, while management described growing inference demand and continued demand for older chips. These remain company claims, not proof every future dollar will arrive.8,9
If existing models become safer and more useful, adoption could absorb capacity that frontier training no longer needs. The hardware bear case requires spending or pricing to weaken; an endorsement on X does not establish either.
Watch the orders after the speeches
Altman is scheduled to speak at Dreamforce on September 15, an immediate opportunity to specify implementation.13
Then watch evaluator appointments, actual capability restrictions, revised capital budgets and rental renewals. For the neoclouds, add customer prepayment receipts, deployment dates and financing terms. Software beneficiaries need retention and pricing to hold. Infrastructure suppliers need orders to survive.
The frontier can wait; the interest meter cannot.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.