Nine banks lifted Freeport-McMoRan targets to as high as $92 on a copper squeeze Freeport says ends in 2027
Nine banks lifted Freeport-McMoRan targets between September 29 and October 9, taking the top mark to $92. The October 2 update behind the raises schedules Grasberg back near full capacity only by the end of 2027, with third-quarter unit costs 5% above plan and 60,000 ounces of gold deferred.
 Vincent Jiang · 3 min read
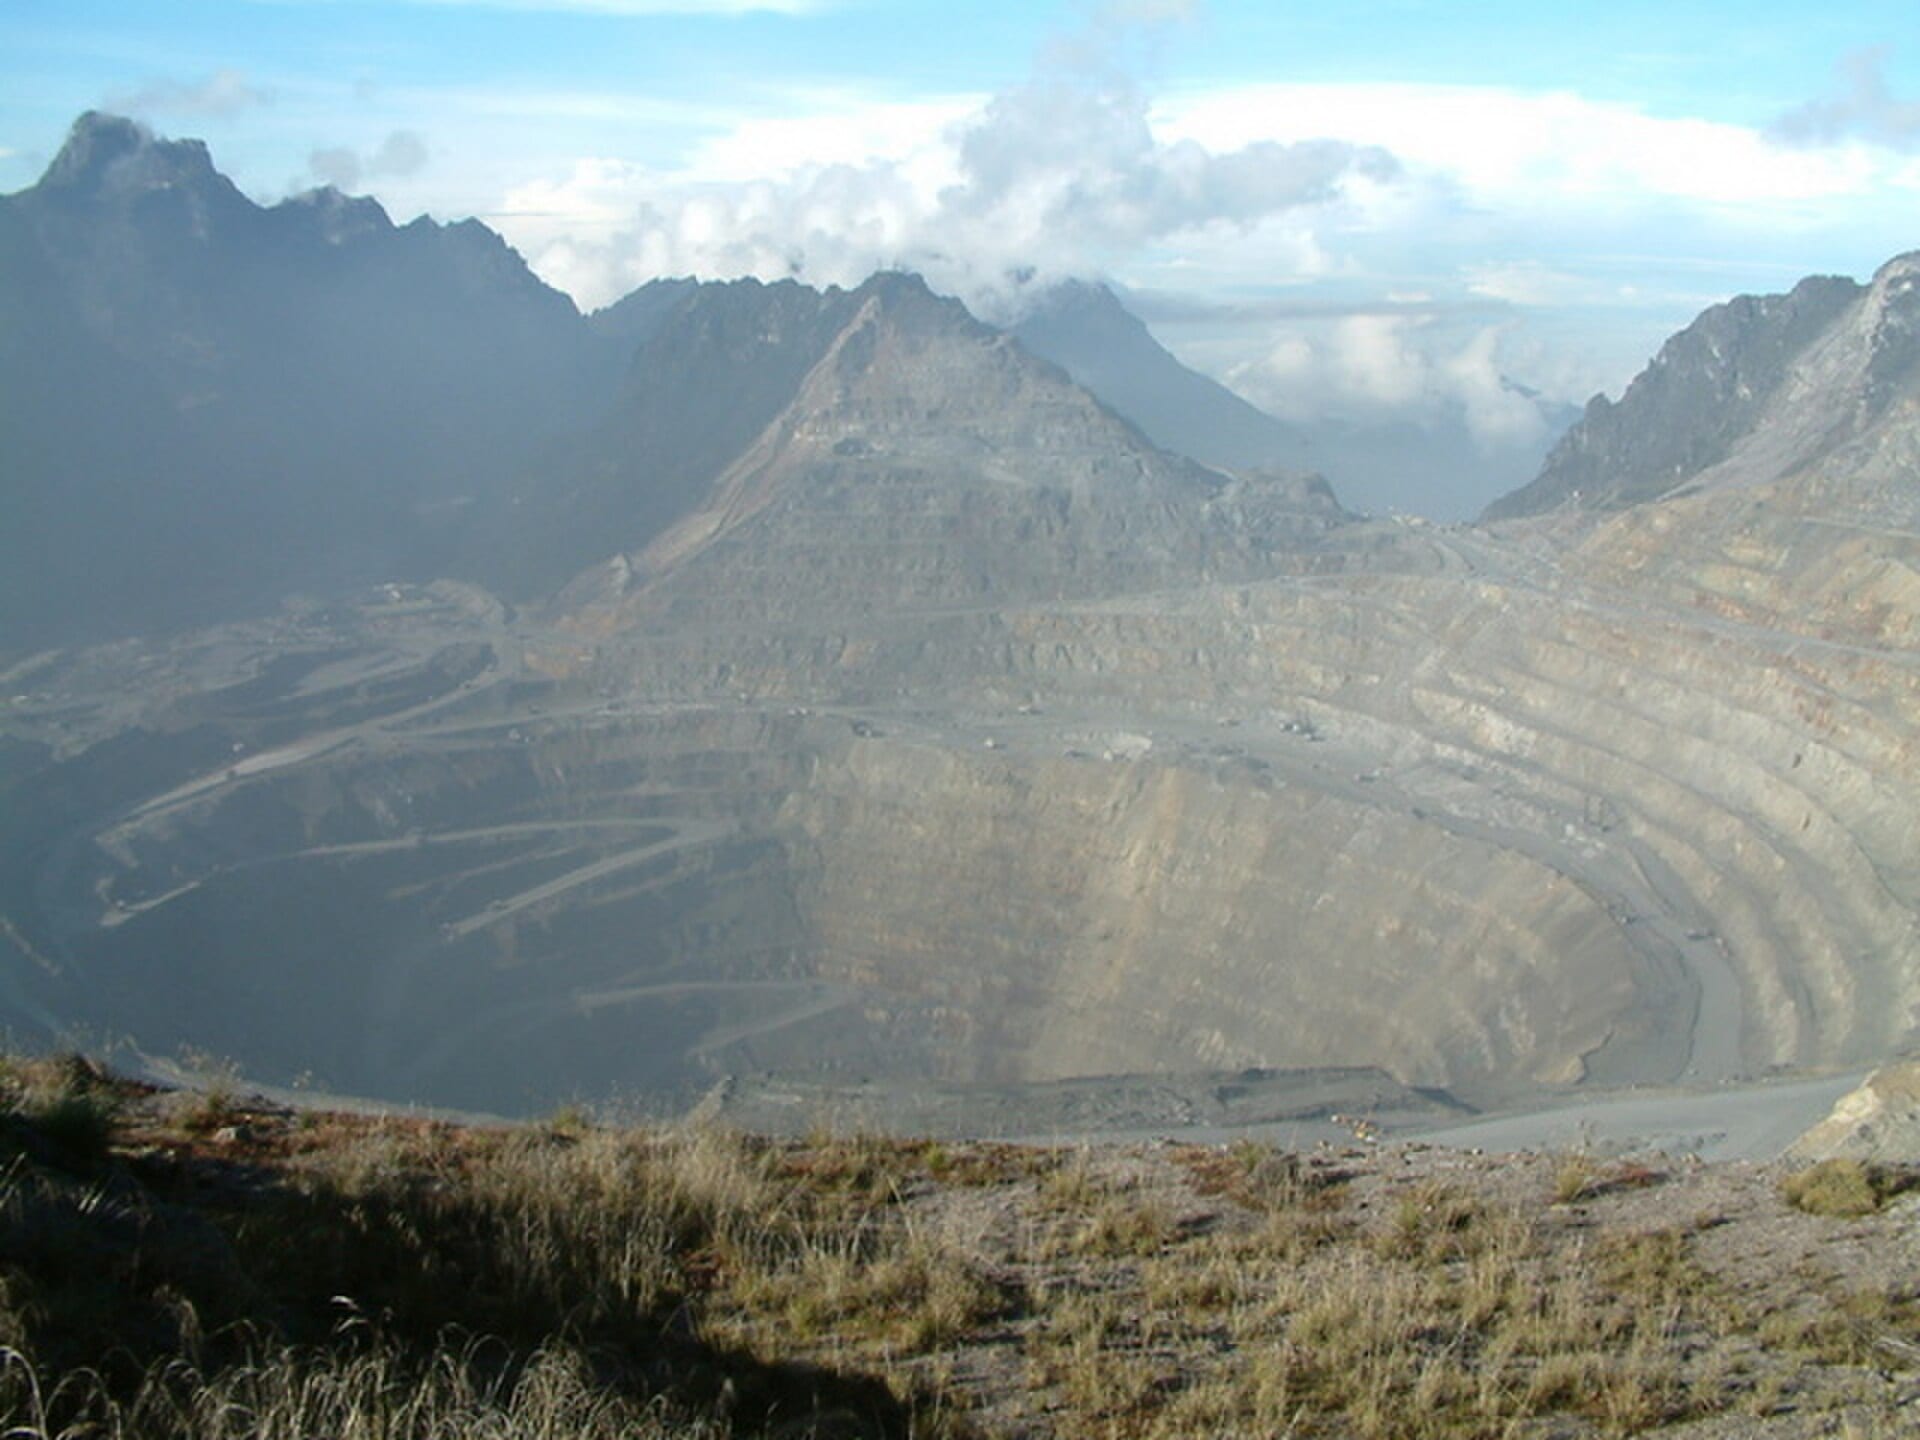
The mine behind the copper record is two-thirds broken
Grasberg is milling about 140,000 metric tons of ore a day, Freeport+3.57% — Freeport, up 3.57 percent today said on October 2, roughly 67% of its normalized rate before the September 2025 mud rush 1. The rush killed seven workers and shut, for nearly a month, the world's second-largest copper mine and its largest gold mine, a district that supplies more than a quarter of Freeport's output 2. Even so, analysts say the recent run to record prices owes more to tariff-driven stockpiling and thin growth in mine supply than to any single outage 34.
Nine raises, eight in five sessions
Nine banks raised their Freeport targets between September 29 and October 9, and eight of them moved in the five sessions after the October 2 update 5. JPMorgan went to $92 from $77, Jefferies to $90 from $82, UBS to $88 from $77, Wells Fargo to $87 from $70 5. The stock closed October 9 at $73.69, up 45% for the year, against a 23-analyst consensus of $77.55; the month's targets span $47 to $92 56.
Every new target since September 29 sits above Freeport's $73.69 close
- Estimate
Data
| Value | |
|---|---|
| JPMorgan (estimate) | $92 |
| Jefferies (estimate) | $90 |
| UBS (estimate) | $88 |
| Wells Fargo (estimate) | $87 |
| BMO Capital (estimate) | $85 |
| Barclays (estimate) | $83 |
| Deutsche Bank (estimate) | $80 |
| BNP Paribas (estimate) | $80 |
| CICC (estimate) | $78 |
The update the banks marked up is not clean
Copper is on plan: about 830 million pounds produced, 750 million pounds to be sold, and a realized price above $6.50 a pound 1. Gold is not: about 230,000 ounces produced, only 100,000 selling, 60,000 deferred into the fourth quarter, and unit net cash costs about 5% above July's $2.00 a pound, which Freeport pins on the missing gold credits rather than operating inflation 1. The trend behind that figure is less innocent: second-quarter unit costs ran $1.97 a pound, up 74% year over year, and the full-year guide is about $1.90 against $1.65 in 2025 7.
Unit net cash costs are up 27% since 2025, and the gold shortfall is why
- Unit net cash costs, $ per pound
- Estimate
Data
| Unit net cash costs, $ per pound | |
|---|---|
| FY2025 | $1.65/lb |
| Q2 2026 | $1.97/lb |
| Q3 plan | $2/lb |
| Q3 implied (estimate) | $2.1/lb |
| FY2026 guide (estimate) | $1.9/lb |
Grasberg mill rates do not reach pre-incident norm again until end-2027
- Mill throughput, % of pre-incident rate
- Estimate
Data
| Mill throughput, % of pre-incident rate | |
|---|---|
| Pre-incident norm | 100% |
| Q3 2026 actual | 67% |
| Mid-2027 target (estimate) | 80% |
| End-2027 target (estimate) | 100% |
The bull case is a deficit Freeport does not control
The upgrade case rests on scarcity elsewhere: Chile, the biggest producer, cut output 6.6% in the first half of 2026, new mines take about a decade to build, and tariff front-running is pulling metal into US inventories 34. Copper settled at a record $6.89 a pound on September 9, up 40% in a year 4. Forward earnings carry the story, 19.9 times against an industry average of 22.2, with 2026 consensus up about 59% 7. And the growth engine is producing now: leaching yields roughly 200 million pounds a year, targeted at 300 million by year-end 89.
The record that argues the other way
The stock trades at 36.4 times trailing earnings against a five-year median of 29.0, one valuation model puts fair value at $49.75, and insiders sold $46 million of stock over 12 months without buying a share 10. This ramp has slipped before: April's guidance cut took 2026 copper sales to 3.1 billion from 3.4 billion pounds and the second-half Grasberg outlook to 65% from 85% of capacity, and Morgan Stanley dropped the stock to Equal Weight at $66 11.
Two dates can break the marks
Earnings land October 27, the first print against the raised bar, and the Bagdad doubling decision closes by year-end 1. Then Freeport's own clock: 80% of capacity in mid-2027, near full capacity by December 2027 1. The banks are pricing a shortage whose expiry date is printed in the press release they upgraded on.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.