Nvidia pays Ibiden, Samsung Electro-Mechanics and Unimicron for substrate capacity; AT&S fell 18.6%
Nvidia is paying Ibiden, Samsung Electro-Mechanics and Unimicron to reserve production of the substrates that sit under its AI chips. AT&S, the Austrian substrate maker absent from Nvidia's list, is building the same capacity on AMD's and Marvell's commitments, and its stock sits 43% below its high with half-year results due on November 5.
 Vincent Jiang · 3 min read
An 18.6% day that named no company news
AT&S−1.00% — AT&S, down 1.00 percent today, Austria's listed maker of high-end IC substrates, the layered circuit boards a processor sits on and connects through 2, fell 18.6% in Vienna on October 22, the biggest drop in the ATX, Vienna's blue-chip index, which lost 4.6% 1. The day's market report blamed renewed doubts about AI spending and a Wall Street technology rout, with Nasdaq futures down nearly 2%, and named nothing from the company 1.
Nvidia now pays to reserve its suppliers
The day before, at its GTC Berlin event, Nvidia−0.54% — Nvidia, down 0.54 percent today said it would lift substrate capacity for its products 2.5 times within three years 34. Chief executive Jensen Huang's summary: "Demand is extraordinary. Capacity is the constraint." 3
Nvidia is paying for the buildout. Ibiden−1.00% — Ibiden, down 1.00 percent today of Japan receives a multibillion-dollar capacity reservation advance for its Ono plant, which targets triple current capacity and ramps from the first quarter of 2028 3. Samsung Electro-Mechanics−2.01% — Samsung Electro-Mechanics, down 2.01 percent today of Korea joins Nvidia's substrate chain with jointly invested dedicated lines at Sejong and Busan; by 2028, production for Nvidia is projected to take a significant share of its substrate output 32. Taiwan's Unimicron−1.36% — Unimicron, down 1.36 percent today adds capacity from the second quarter of 2027 under an Nvidia reservation agreement 3.
Nvidia's payments are not purchase orders: the reservation advances and co-funded lines hold capacity at those three makers for its products 32.
Kulim is the counterbet, on AMD's and Marvell's money
All three make the substrates AT&S makes, and AT&S appears nowhere in Nvidia's announcement; its expansion is financed from outside that circle 3. On June 15 it unveiled a €1.5–2.0 billion expansion of its Kulim plant in Malaysia, based on agreements with AMD+1.59% — AMD, up 1.59 percent today and one other customer, fully supported and financed by long-term customer commitments 5.
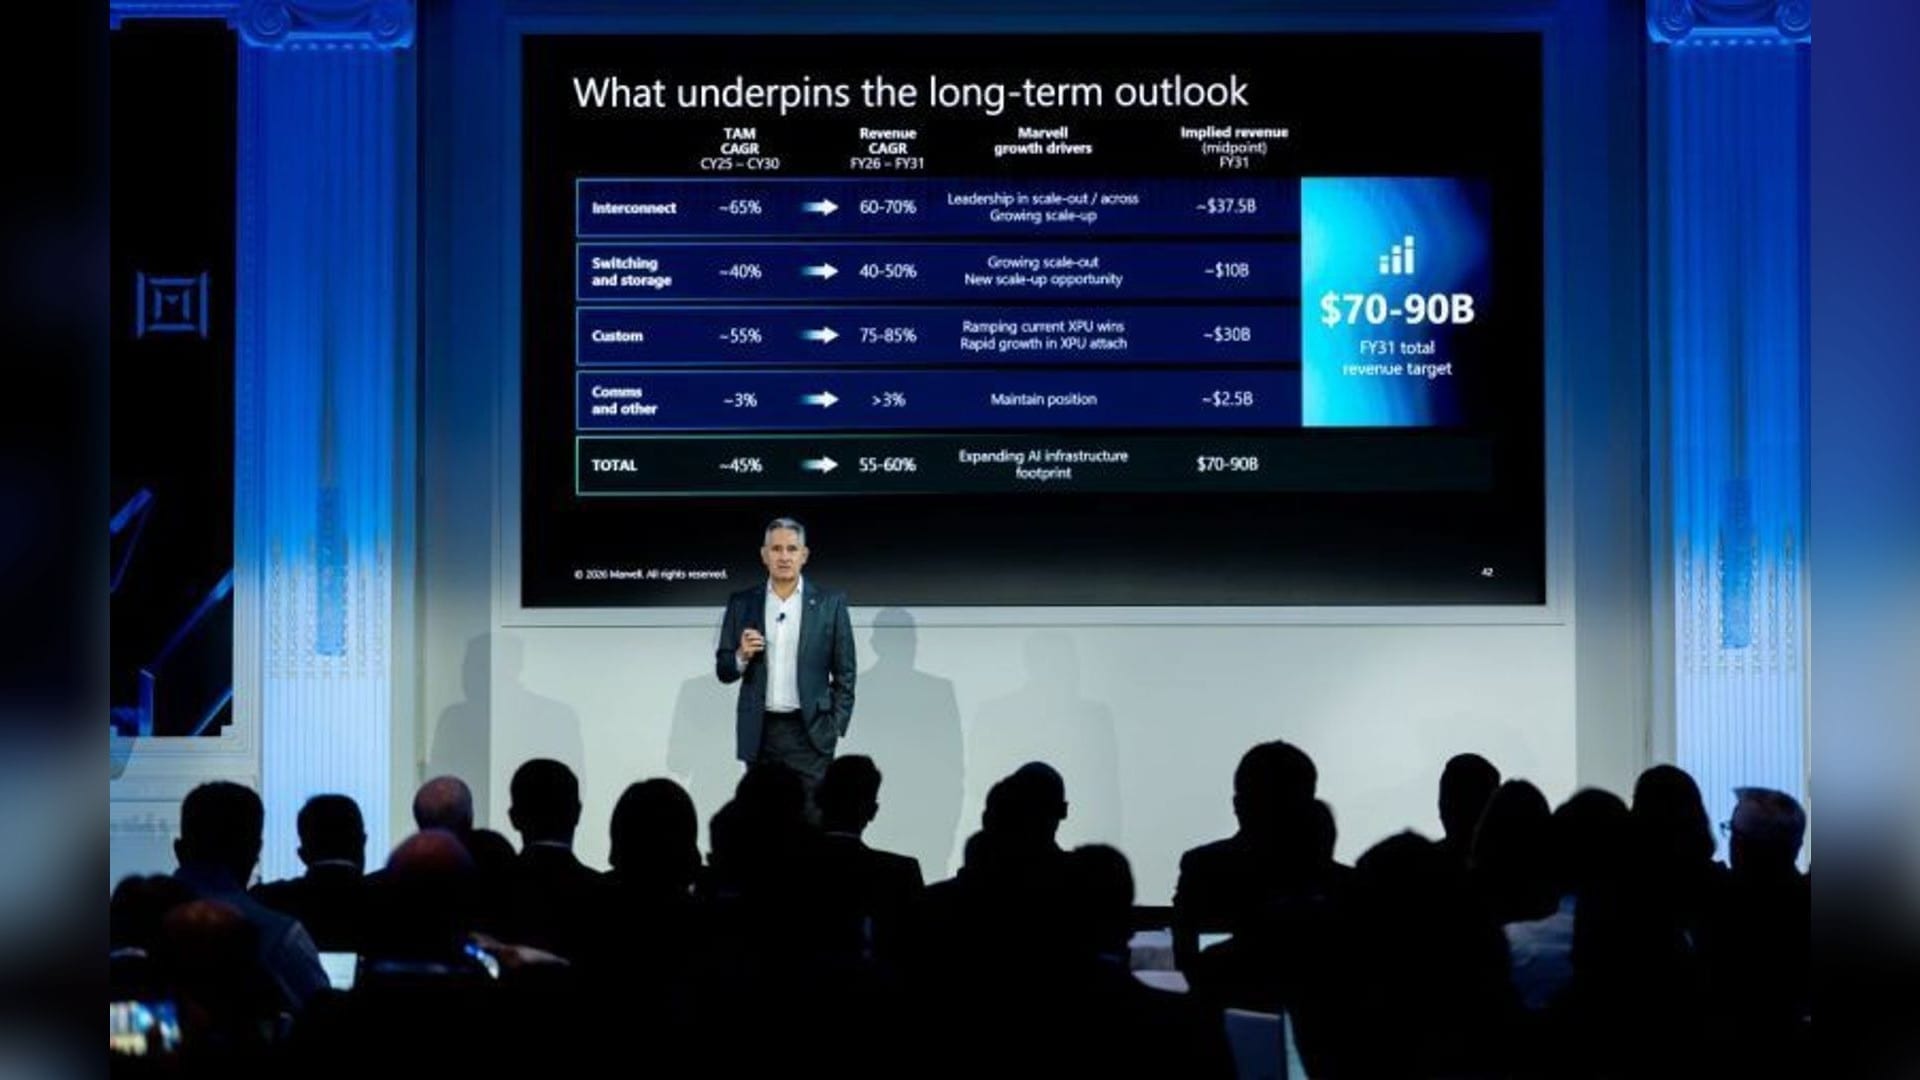
The guidance rose with it: for the 2026/27 financial year, revenue up 45–55% at constant currency, an EBITDA margin of 32–37%, capex of roughly €1.0–1.2 billion, and operating free cash flow still positive 5. On September 22 the second customer was named: Marvell+1.75% — Marvell, up 1.75 percent today, a Silicon Valley designer of data-infrastructure chips 6. Customer prepayments already stood at €907.2 million on June 30 7.
June-quarter revenue rose about 38%; EBITDA more than doubled
- Revenue
- EBITDA
Data
| Revenue | EBITDA | |
|---|---|---|
| Jun 2025 | €398.9M | €70.6M |
| Jun 2026 | €548.7M | €165M |
The June quarter backed the plan. Revenue reached €548.7 million, up about 38% year over year, EBITDA hit €165 million at a 30.1% margin against 17.7% a year earlier, and net income was €40.85 million after a €60.5 million loss 87.
€137.50 against a €380 target
Deutsche Bank's view is €380: the bank raised its target from €320 on October 8 and kept its buy rating 7. The stock market's view is €137.50, the weekend price on October 24, down from €157.80 on October 22 8 and €144.00 on October 23 7, inside a 52-week range of €25.00 to €242.00 9.
Management tightened the balance sheet anyway, redeeming its €350 million 2022 hybrid bond, a bond that counts partly as equity, on October 22 into new financing at roughly half the coupon 9. The bear case is capacity arithmetic: three funded rivals and 2.5 times the substrate supply by 2028 3.
Three sessions took AT&S 43% off its 52-week high; the bank target is €380
Data
| Value | |
|---|---|
| 52-wk high | €242 |
| 22 Oct | €157.8 |
| 23 Oct | €144 |
| 24 Oct | €137.5 |
Two numbers decide it on November 5
The half-year report on November 5 is the first set of results since Marvell signed 8. Two lines in it answer the market's doubt: prepayments from AMD and Marvell, and operating cash flow, which ran at €39.9 million in the June quarter against more than €1.0 billion of planned capex 85. If those two numbers do not improve, the 43% discount stands 85.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.