onsemi's $2.5 Billion AI Promise, Marked Down 9% in a Day
Management says power density turns $15,000 of silicon per rack into more than $115,000, but the architecture that earns it lands in 2028 and beyond. This week the market declined to prepay for it.
 Richard TangSeptember 18, 2026 · 3 min read
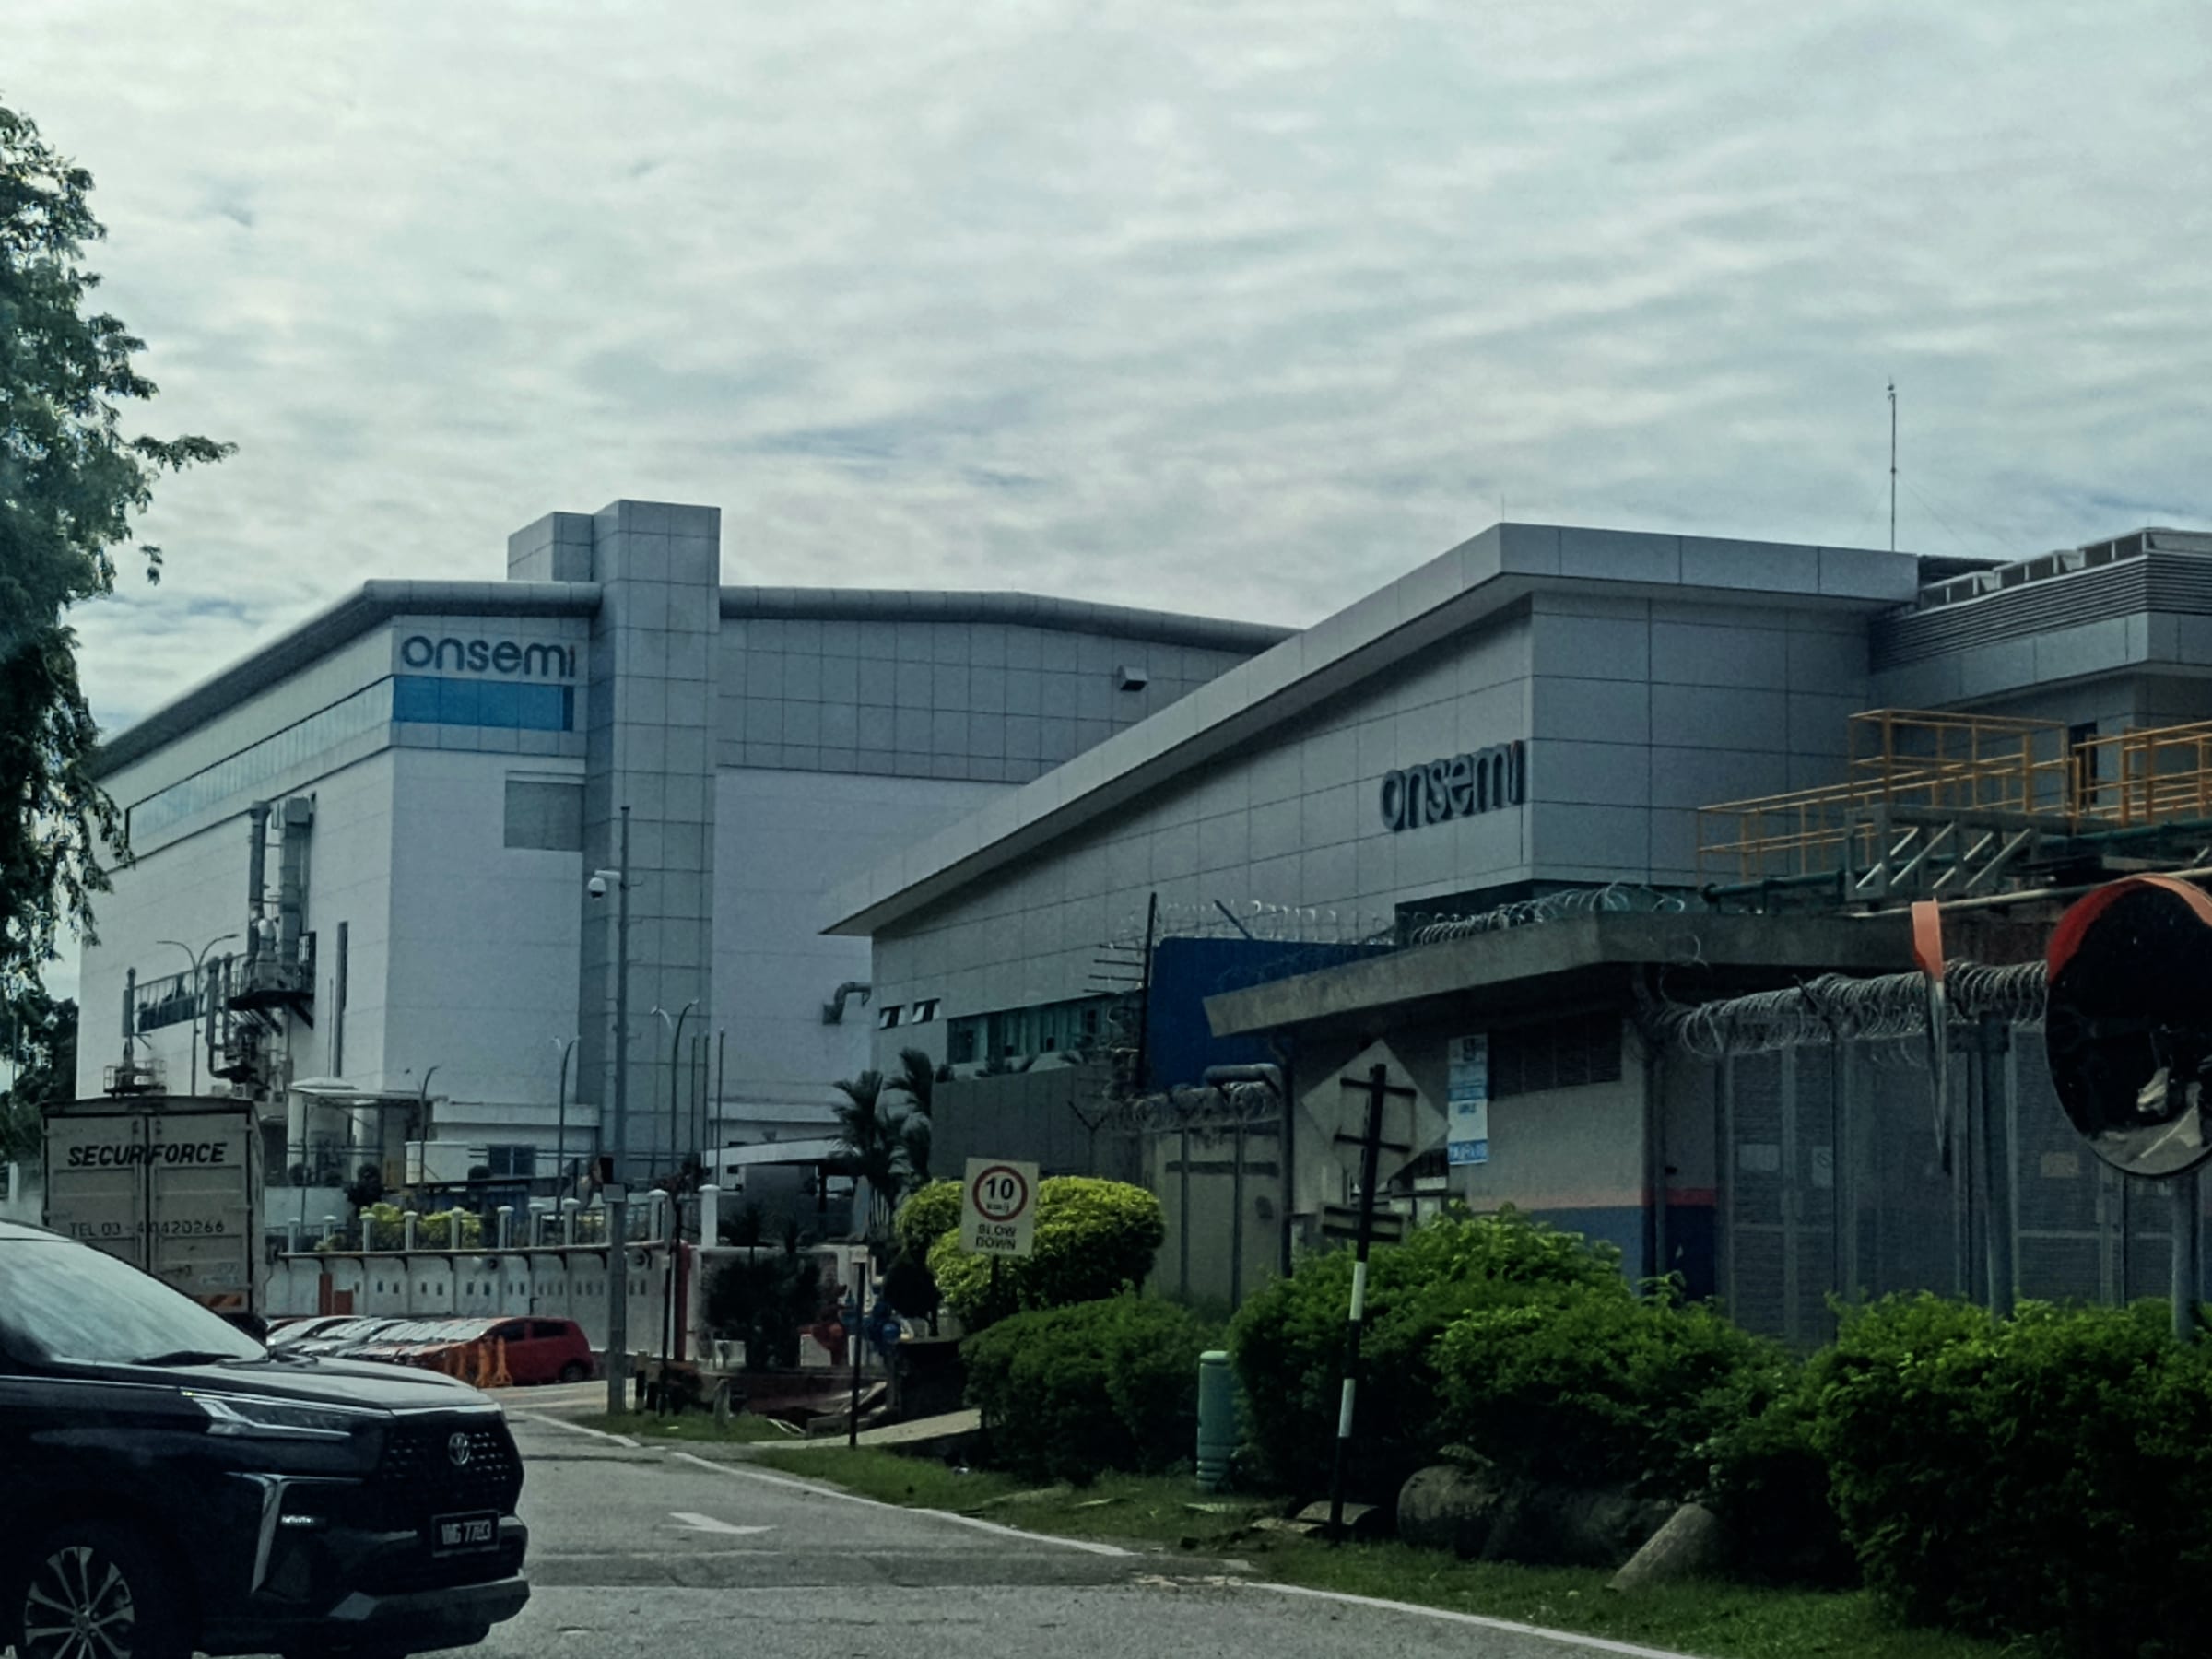
On 16 September, onsemi promised investors revenue of just under $11 billion by 2030 (about two-thirds above this year's $6.6 billion), a 53% gross margin, and a $2.5 billion AI data-center business from a base of less than $250 million 12. The stock closed down 9.02% at $66.60 1. A quarter-point Fed hike that afternoon, the first since July 2023, did not help 3. But the market's real objection was not the Fed; it was the calendar.
The physics is the part nobody disputes
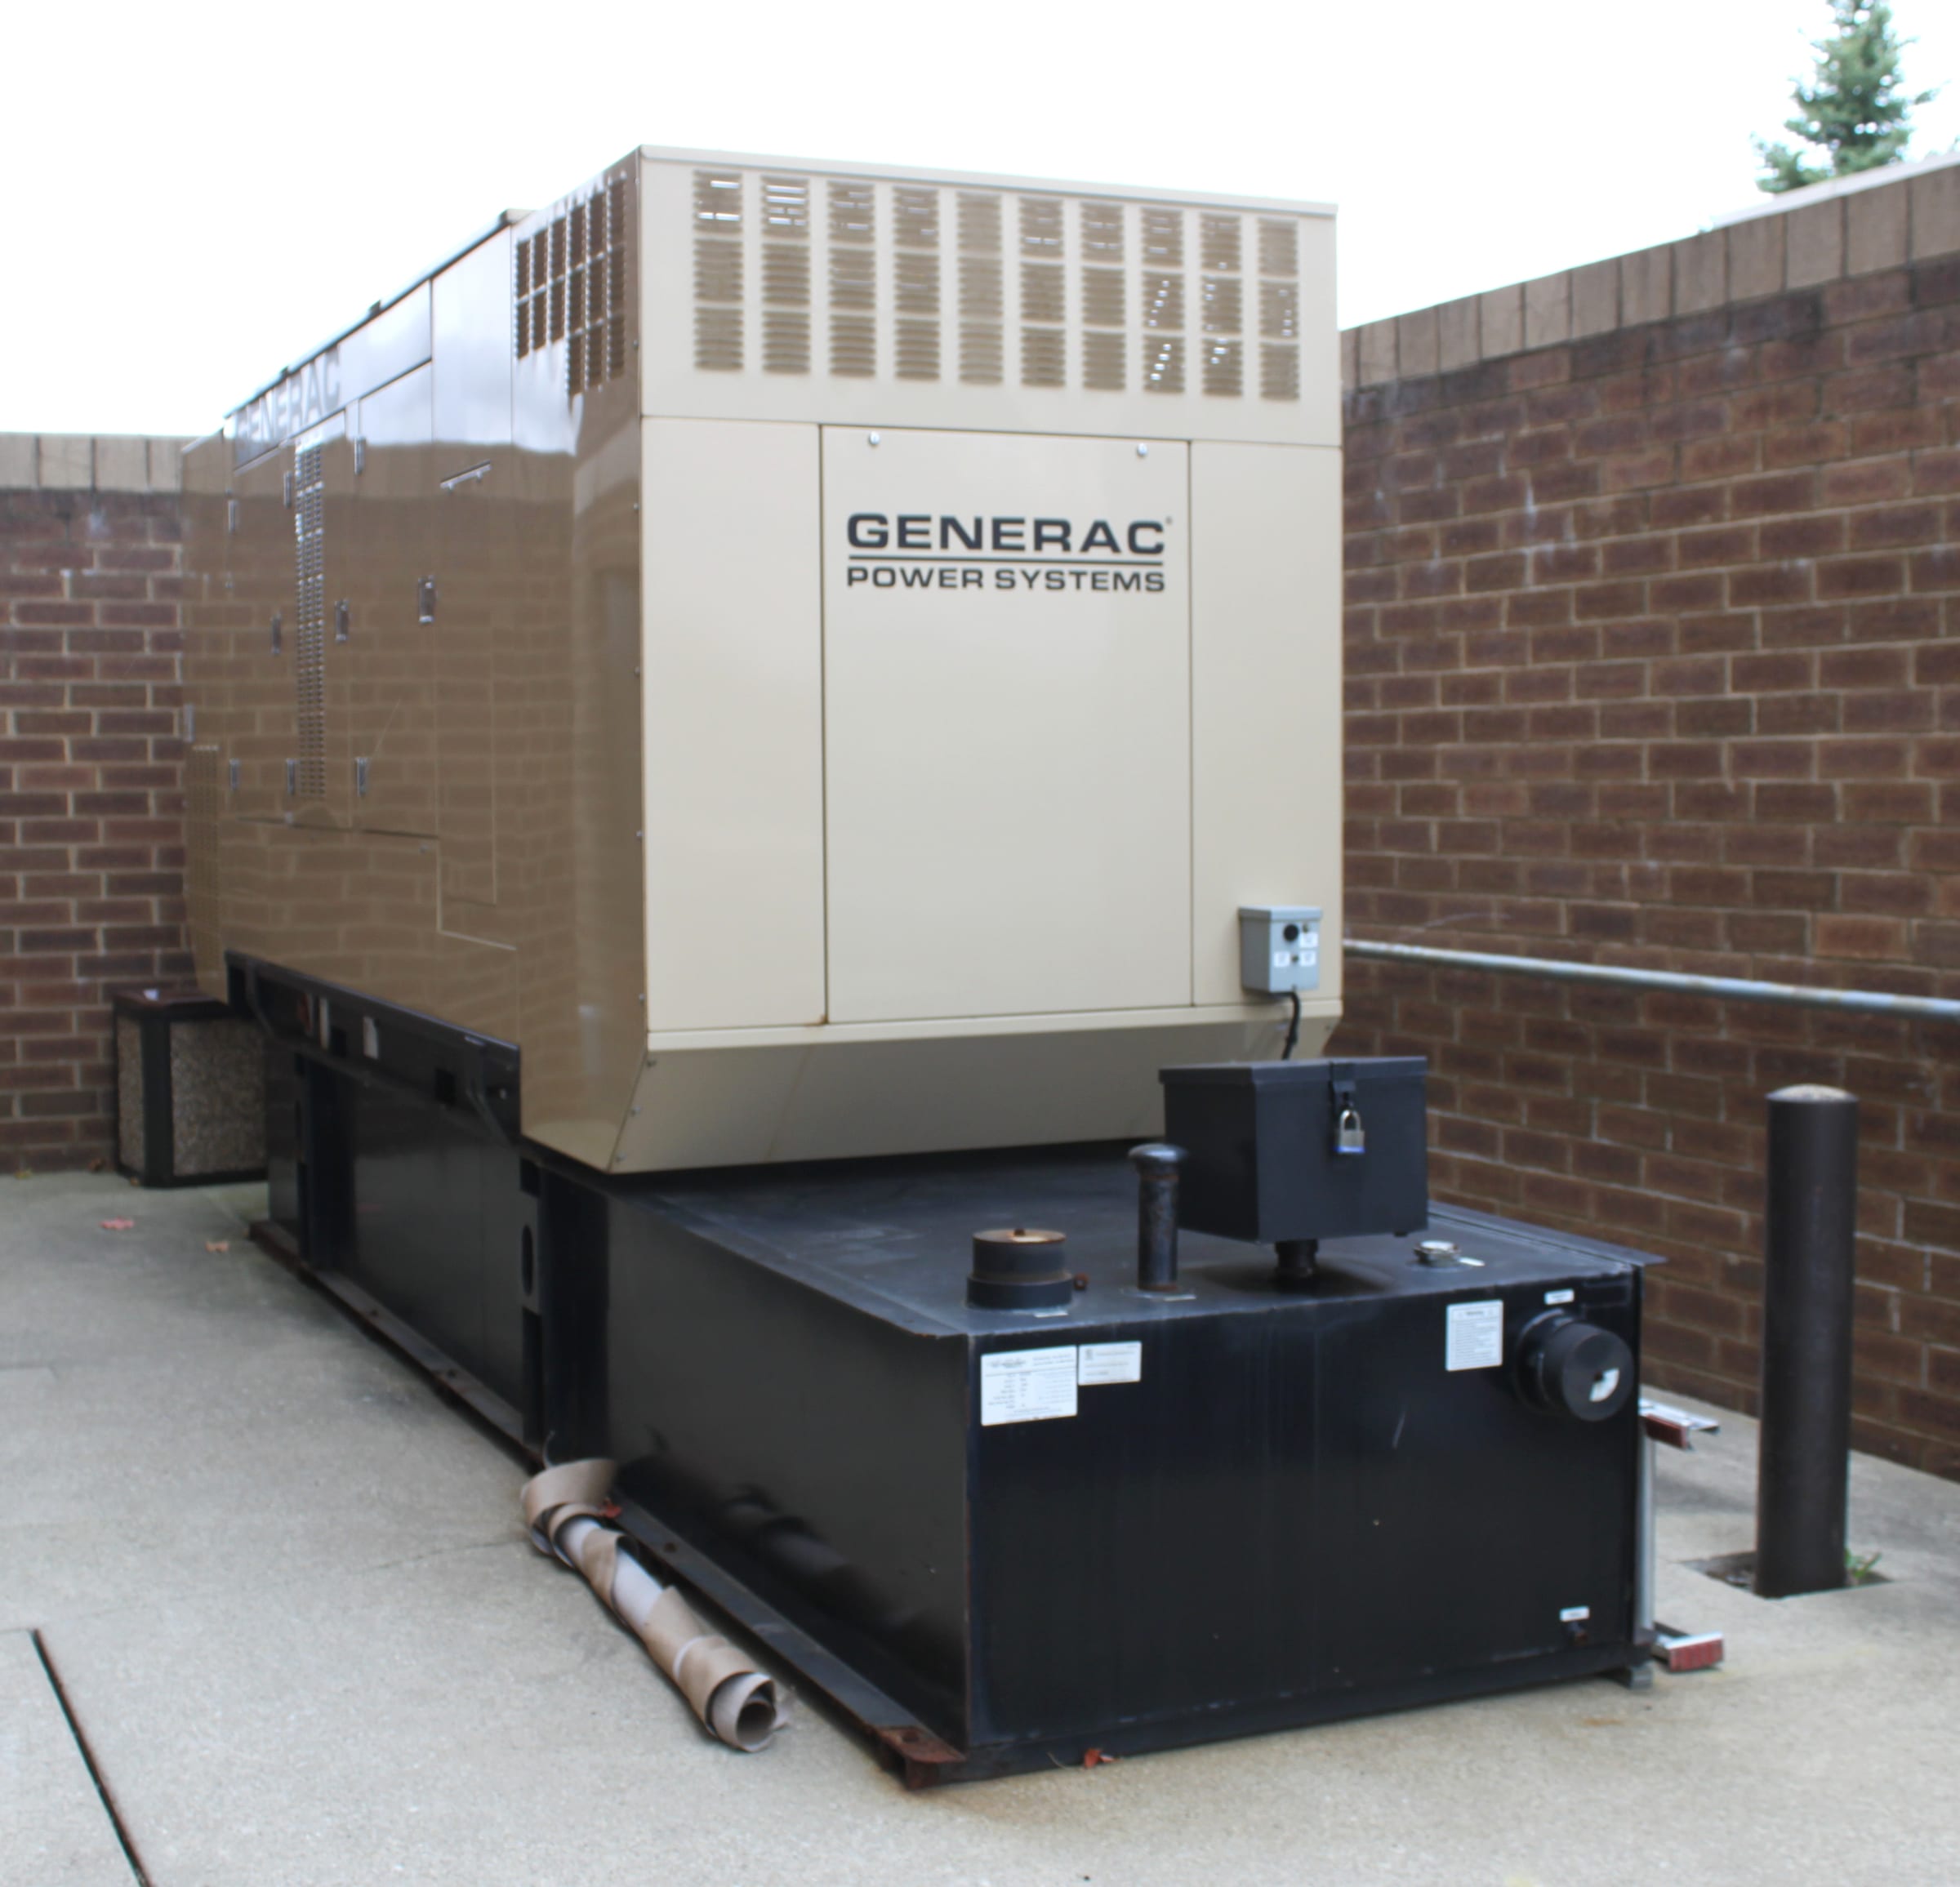
CEO Hassane El-Khoury's argument is that AI's bottleneck has moved past compute and memory to delivering power. "More power is really not enough," he said. "We need better power" 2. Achyut Shah, onsemi's power chief, borrowed a Goldman Sachs line for the problem: "how do you fit the power of 1,000 homes in 1 small cabinet?" 1. The industry's answer is to move racks from today's low-voltage distribution to 800-volt DC and rebuild the power tree around solid-state components 12.
On the company's own estimate, its content per rack climbs from about $15,000 to more than $115,000, roughly 8x 12. El-Khoury claims the vertical GaN built at the Syracuse fab keeps onsemi "probably half a decade ahead" of the field 1.
The payoff lands in 2028, but the promise is priced today
The first high-voltage sidecar racks ramp toward the end of 2027, and the solid-state transformers start "in the end of '28, early '29" 12. The $45 billion AI data-center piece of onsemi's $213 billion 2030 opportunity is mostly a 2028-and-later event 14. The bridge is small: AI data-center revenue above $500 million this year, more than double 2025, doubling again in 2027, inside a company doing about $6.6 billion 12.
Data
| AI data-center revenue | |
|---|---|
| 2026 >$0.5B | $0.5B |
| 2027 >$1.0B | $1B |
| 2030 >$2.5B | $2.5B |
Shareholders fund the wait, with dilution outside the frame
They were asked to underwrite a five-year plan while the pending $6.7 billion all-stock Synaptics deal sits outside the model: 1.35 onsemi shares per Synaptics share, roughly 12% to 14% dilution, FTC clearance already in hand 156. Stifel admired the strategy and still cut its target from $90 to $75, keeping a Hold: the 2030 endpoint landed below what buyers had hoped 7. The 9% was not only macro; even the fans found the promise light.
Hyperscalers get the power; onsemi's fabs carry the risk
The beneficiaries are the hyperscalers: they get the 8x content step whenever it arrives, and they need the power no matter whose silicon delivers it. The risk sits in onsemi's fabs, because the margin recovery runs through factory utilization.
Utilization climbed from 68% at the end of 2025 to about 83% exiting the second quarter, each point worth 25 to 30 basis points of gross margin, most of that already banked 1. The next leg needs automotive growing about 9% a year on flat vehicle production 12, in a business whose revenue fell 15.3% in 2025 1.
November's results settle whether the wait is compounding
The sell-off prices the timeline, not the technology; the market refused to prepay five years of a roadmap whose physics it does not dispute. What settles it arrives in early November: third-quarter results, with the Street at about $1.70 billion of revenue and $0.87 of adjusted EPS 1.
Utilization above 83% and AI revenue tracking past $500 million would say the bridge years are compounding on schedule. A wobble in the automotive order book, and the investors who sold the roadmap will look early rather than wrong.
How this brief was made
01Gathered & sourced372 channels · 1,817 articles▾
Agents swept 372 channels and ingested 1,817 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated7 claims · 19 data feeds▾
Every one of 7 load-bearing claims was checked against primary sources, with 19 live data feeds reconciling the figures and charts.
- 1Yahoo Finance (TIKR), "ON Semiconductor Stock Fell 9% After Its Analyst Day. Here's Where the Stock Could Go in 2026," 17 September 2026
- 2Yahoo Finance (MarketBeat), "onsemi Targets $2.5B AI Data-Center Revenue, Sets Ambitious 2030 Margin Goals," 17 September 2026
- 3CoinDesk, "Fed raises rates by 25 basis points in first hike since July 2023," 16 September 2026
- 4onsemi press release via Yahoo Finance (GlobeNewswire), "onsemi Charts Path to Power the Next Decade of Innovation," 16 September 2026
- 5The Globe and Mail (TipRanks), "ON Semiconductor to Acquire Synaptics in All-Stock Deal," 26 June 2026
- 6Seeking Alpha, "Onsemi receives early termination notice for Synaptics acquisition," 14 August 2026
- 7Seeking Alpha, "onsemi's 2030 outlook falls short; Stifel lowers target," 17 September 2026
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.