Parsons 合同越拿越多,利润却越来越难守住
单季获得19亿美元合同授予,却同时录得1500万美元净亏损。在手订单真实存在,但订单背后的现金,还需一个季度一个季度地证明。
 Vincent Jiang · 6 min read
亏损暴露出 Parsons 真正卖的是什么
凯里·史密斯(Carey Smith)7月对投资者表示,Parsons 正准备退出偏远地区的两份合同,因为那里的人员和物资成本已经过高。1 她领导的这家公司刚刚在单季录得19亿美元合同授予额,同时报告了归属于股东的1500万美元净亏损。2
这正是 PSN 的复杂之处。Parsons 能拿到政府一些最重要难题的项目,却仍难以把解决这些难题赚来的钱留住。
Parsons 把国防技术与基础设施工程结合在一起。投资者买入的,既有技术能力,也有管理层为复杂项目定价、配齐人手并完成交付的能力。
第二季度的问题,恰好出在第二项能力上。未经审计的业绩中,包括拟出售联邦项目约7800万美元亏损,以及基础设施合资企业带来的4100万美元损失。报告调整后 EBITDA 为4200万美元。管理层再做一次正常化调整、剔除上述费用后,得到1.61亿美元。两个数字都包含合并报表企业外部股东应占的收益。2
这些调整能解释为什么一个季度难看、持续业务却可能健康,但不能因此认为这些亏损在经济上无关紧要。
财报文件显示,联邦项目费用中包含约6100万美元预期未来亏损。合资企业费用则反映完工成本估算上调。这些不是仅因收购资产估值下降,而是交付义务本身变贵了。3
对一家做运营的公司来说,问题因此变了:眼下漂亮的在手订单里,有多少是在未来的人员、设备和进度问题暴露之前就定好价的?
庆祝数字之前,先读懂合同
最新公告说明为什么采购术语很重要。9月14日,Parsons 宣布有九项解决方案被认定为具备国防市场授标资格。这增加了接触买方的机会,但并不等于确立了订单金额。4
8月的 COMET 公告更引人注目:Parsons 在一个情报类合同工具中获得一席之地,合并上限超过140亿美元。Parsons 仍需为每一笔订单竞争。PeopleTec 9月也宣布自己进入同一个合同工具。机会是多家共享的。5,6
即便是具体合同延期,也要注意时间口径。8月24日宣布的5.14亿美元导弹防御合同选项,已经为第二季度订单贡献了1.95亿美元。如果把整个标题数字都加到当季中标额里,就会重复计算其中一部分机会。7,2
获得准入、收到订单、确认收入和收回现金,是各自独立的成果。业务每推进一个阶段,投资逻辑才会更强。
网络套件的论据更有力
Parsons 旗下子公司 SealingTech 给出了更具体的乐观理由。国防创新部门(Defense Innovation Unit,DIU)在2025年3月描述了客户的问题:军方网络团队使用的设备互相割裂,带来了互操作性难题。团队需要一种便携式安全运营能力,能在互联网接入和敏感数据传输权限受限的环境中工作。DIU 从92份提交方案中选出了三家原型供应商,SealingTech 是其中之一。8
2026年8月,Parsons 宣布 SealingTech 获得联合网络狩猎套件(Joint Cyber Hunt Kit)为期五年的独家生产协议,上限为7.5亿美元。这个上限只是最大值,不等于保证销售额。但被选中进入生产,是比进入市场平台更实质性的商业里程碑。9
我的推断是,标准化可能改善 Parsons 的经济效益。跨团队复用产品,可以把工程费用分摊到多次交付上;集成和支持则能加深客户关系。但好处取决于重复订单、实际交付成本和支持义务。授标上限和采购决定本身,都不能确定产品利润率。
专长有价值,对手的专长也一样
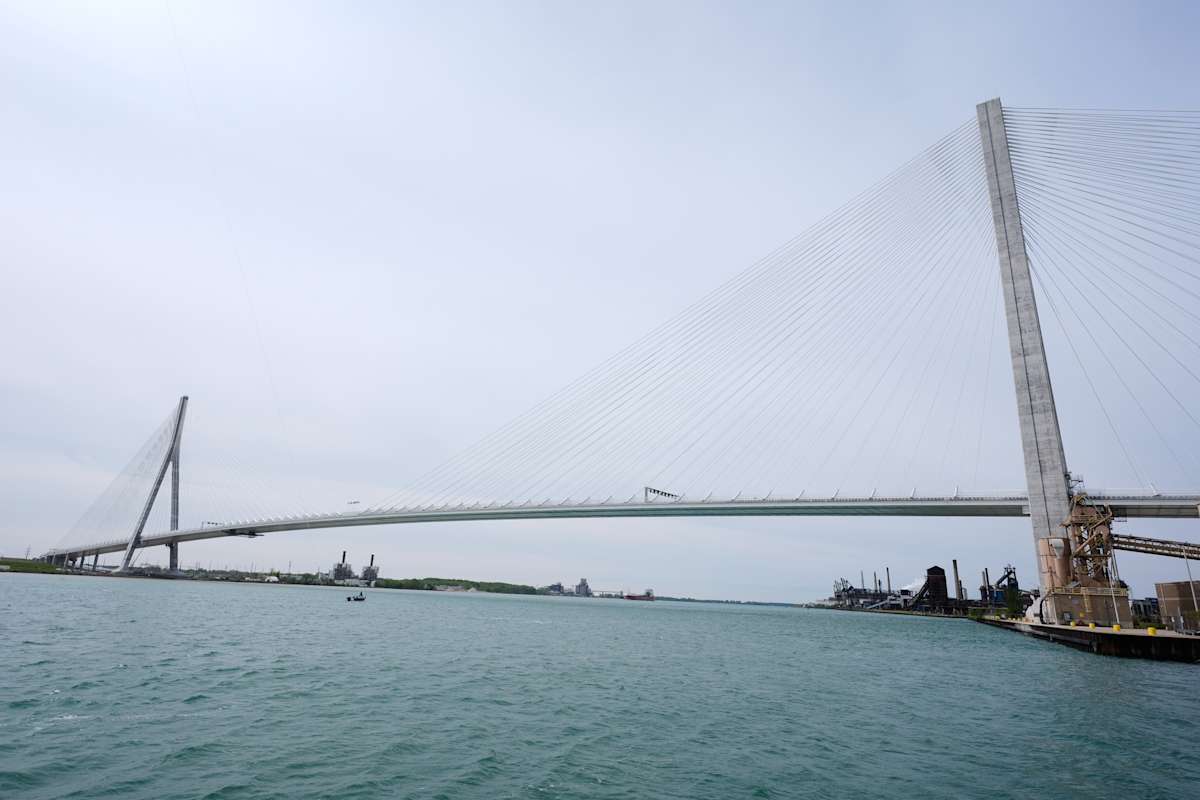
Parsons 的基础设施业务展示了经验积累的价值。温莎-底特律大桥管理局在2018年任命 Parsons 为戈迪·豪国际大桥的业主工程师,职责包括设计审查、检查和合规监督。该管理局报告称,大桥于2026年7月27日通车。Parsons 帮助业主监督交付,但并非项目的设计-施工主承包商。10,11
这种区别很重要。技术监督和承担施工风险,即便在同一项实物资产上,也可能带来截然不同的经济效益。这座大桥只能证明 Parsons 承担了运营角色,并不能确定它就是第二季度亏损的来源。
对客户的熟悉也会让竞争对手受益。今年2月,美国政府问责局(GAO)驳回了一家 Amentum-Parsons 合资企业针对陆军延长 KBR 欧洲物流合同的质疑。连续性和过渡考量,为保留现有承包商提供了理由。关系既能守住现有收入,也会让别人的合同更难被抢走。12
50亿美元估值背后的现金门槛
按9月14日收盘价46.94美元计算,并采用7月21日的股数,Parsons 的估计股权价值约为50亿美元。这只是近似值,并不是完全摊薄的估值。13,3
管理层给出的全年经营现金流中值为4.6亿美元,资本开支约9000万美元。两者相减得到3.7亿美元,股权价值约为该数字的13.5倍。但这一计算尚未扣除合资企业资金投入和支付给外部股东的分配款,并非完全归 PSN 股东可支配的现金。14,3
要达到这个目标,还需要一个强劲的收尾。Parsons 上半年产生了约5400万美元经营现金流。管理层表示,第三季度应产生全年中值约22.5%的现金流,即1.04亿美元。按我的计算,第四季度需要完成约3.03亿美元:接近全年目标的66%。3,14
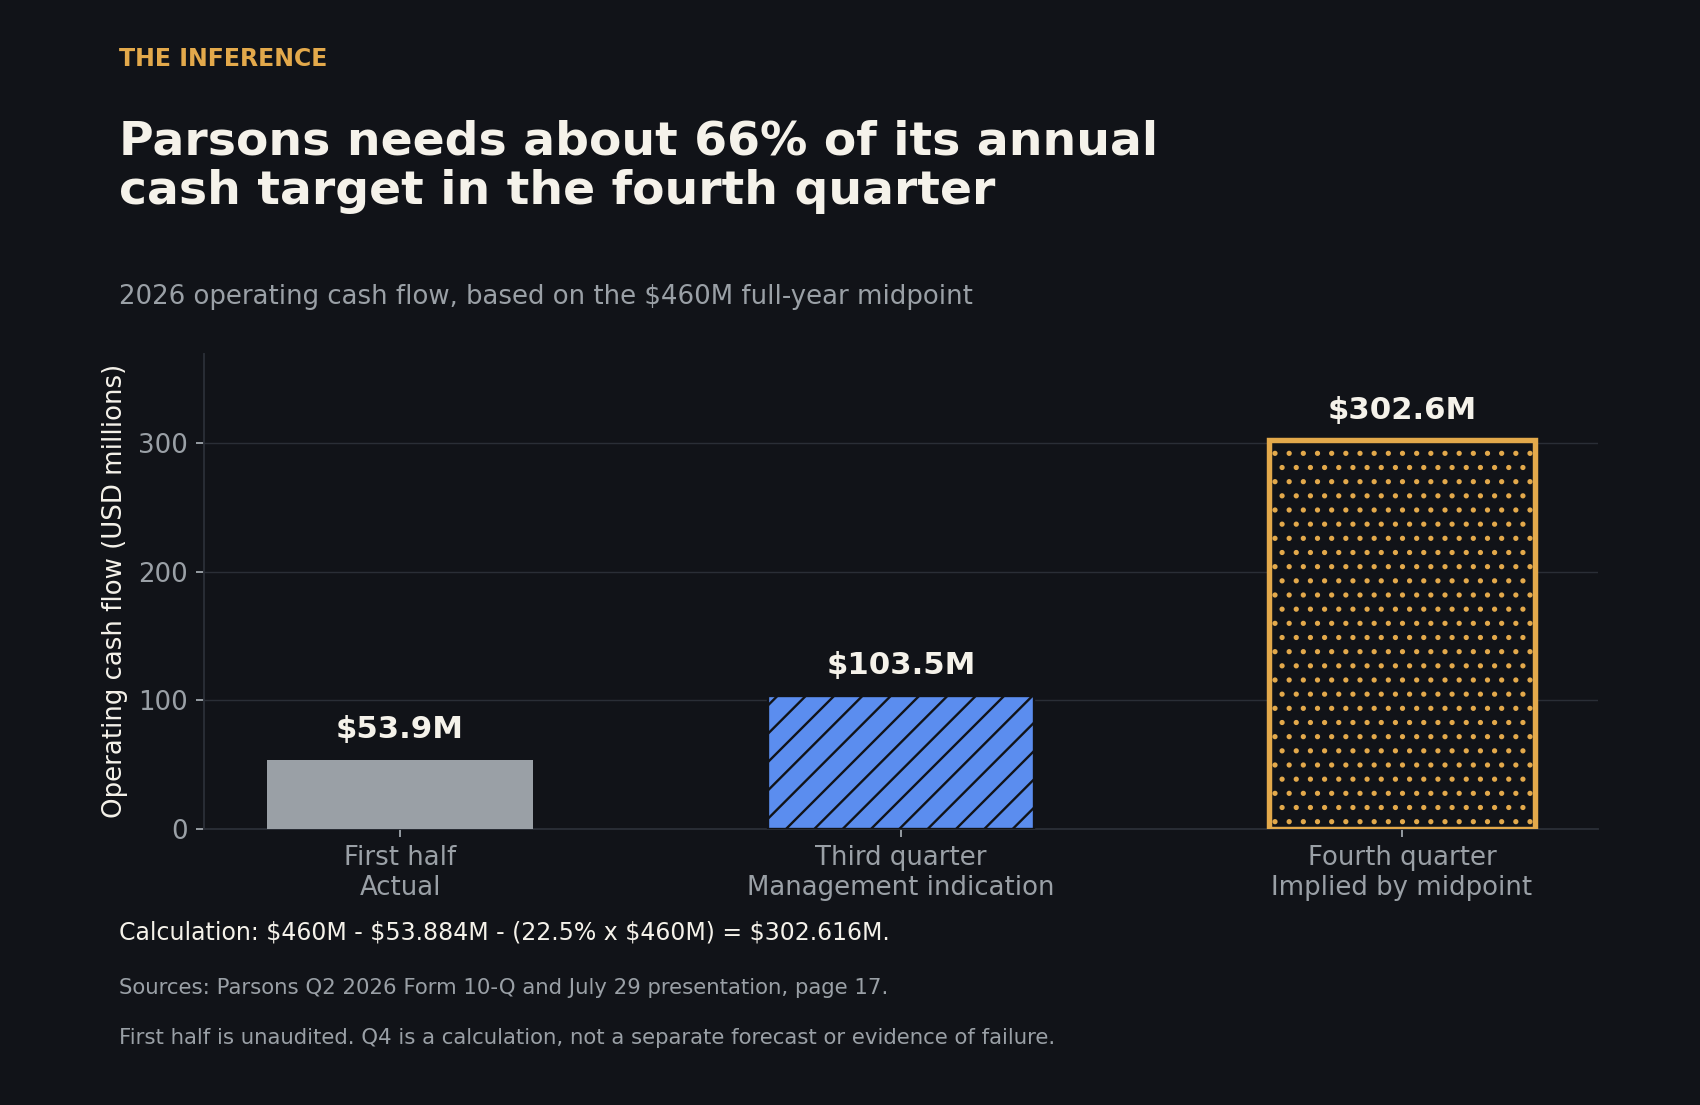
订单储备的质量,要用交付后剩下的现金来衡量。
这个时间表检验的是管理层的解释,并不证明前景会落空。在7月电话会上,首席财务官 Matt Ofilos 将现金压力部分归因于内存和存储库存的采购,以及客户付款时间。产品可能改善利润率,但需要在客户付款前先投入现金。增长和现金消耗可能同时到来。1
清理之后,业务可能更好
最有力的看多逻辑是,退出联邦项目能剥离不合适的工作,而遗留基础设施项目正走向完工。管理层将基础设施费用归因于异常降雨和工期延误,并表示 Parsons 早在2019年就不再追逐类似的联合体项目。1
截至6月30日,Parsons 93亿美元订单储备中约66亿美元已有资金支持。扣除合资企业费用后,基础设施业务的调整后 EBITDA 增长18%,正常化利润率达到11.9%。联邦业务正常化利润率较低,为8.2%。因此,持续业务确实有实力,只是改善并不均衡。14
史密斯不需要每个新产品都变成巨型平台。更好的合同选择、可重复的网络交付和更少的施工义务,合在一起可以改善盈利质量。如果收入基数更小,但所需资本更少、意外也更少,反而可能更值钱。
尚未解决的问题是,清理是否止于这些合同。投资者需要证据表明,下一代项目在完成过程中能有更好的经济效益。
盯紧回款和退出收尾
下一份财报应当验证第三季度经营现金流是否接近管理层约1.04亿美元的指引。若低于这个数字,除非全年指引改变,否则第四季度需要完成的金额会更高。
接着还要关注计划中的合同出售能否如财报文件所预期,在年底前转移剩余义务;同时要留意现有项目收尾期间是否会出现新的费用。3
对史密斯而言,下一个有说服力的结果,是工作完成后真正收回现金。
How this brief was made
01Gathered & sourced409 channels · 2,256 articles▾
Agents swept 409 channels and ingested 2,256 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated14 claims · 32 data feeds▾
Every one of 14 load-bearing claims was checked against primary sources, with 32 live data feeds reconciling the figures and charts.
- 1The Motley Fool, Parsons (PSN) Q2 2026 earnings call transcript, Aug 7 2026, reproducing the Jul 29 call (primary-speaker evidence: Smith on the remote contracts and rainfall; CFO Matt Ofilos on inventory purchases and payment timing). Weather causation is attributed, not independently proved; this host is not counted as independent company verification.
- 2Parsons, Q2 2026 results, Jul 29 2026 (unaudited reported results, non-GAAP reconciliations, funded backlog, bookings, and the $195M of the MDA extension already booked in Q2).
- 3Parsons, Form 10-Q for the quarter ended Jun 30 2026, filed Jul 29 2026 (primary unaudited filing: cash flows, programs held for sale, JV completion estimates, backlog, and the Jul 21 share count). Company-hosted filing used because direct SEC HTML retrieval was intermittent.
- 4Parsons, announcement of nine solutions designated eligible for defense marketplace awards, Sep 14 2026 (primary record; no order value established).
- 5Parsons, COMET contract-vehicle position announcement, Aug 26 2026 (primary record: a shared multiple-award vehicle with a combined ceiling exceeding $14B, not a $14B Parsons order).
- 6PeopleTec, COMET contract-vehicle position announcement, Sep 8 2026 (another awardee's primary announcement, confirming COMET access is shared; does not identify Parsons' future task-order share).
- 7Parsons, Missile Defense Agency contract-option announcement, Aug 24 2026 (primary record: $514M two-year extension; $195M of it already disclosed as booked in Q2 results).
- 8Defense Innovation Unit, prototype-selection announcement, Mar 20 2025 (primary customer account: fragmented equipment and interoperability problems, three prototype suppliers selected from 92 submissions, including SealingTech). Evidence of the customer need and prototype procurement, not of the subsequent production award's funding or SealingTech's unit economics.
- 9Parsons, SealingTech Joint Cyber Hunt Kit production-award announcement, Aug 25 2026 (primary record: five-year sole-source production OTA with a $750M ceiling, a maximum rather than guaranteed sales).
- 10Windsor-Detroit Bridge Authority, owner's-engineer appointment record, Mar 5 2018 (primary record of Parsons' oversight role and scope, distinct from the design-build prime).
- 11Windsor-Detroit Bridge Authority, bridge-opening record, Sep 1 2026 (primary confirmation of the Jul 27 opening; does not identify this bridge as the source of the Q2 JV loss).
- 12US Government Accountability Office, Amentum Parsons Logistics Services decision, Feb 4 2026 (primary adjudication: denied the JV's challenge to an Army extension of KBR's European logistics work on continuity and transition grounds).
- 13Stock Analysis, PSN historical prices, identifying S&P Global Market Intelligence as its data provider, Sep 14 2026 close of $46.94 (primary market-data series reproduced through a distribution site).
- 14Parsons, Q2 2026 investor presentation, Jul 29 2026 (pages 8-9 explain normalization; pages 16-18 present guidance and assumptions, including Q3 operating cash at approximately 22.5% of the full-year midpoint). Normalized measures are management's supplemental presentation, not independently certified recurring earnings.
03Reviewed & edited1 human editor▾
One editor read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.