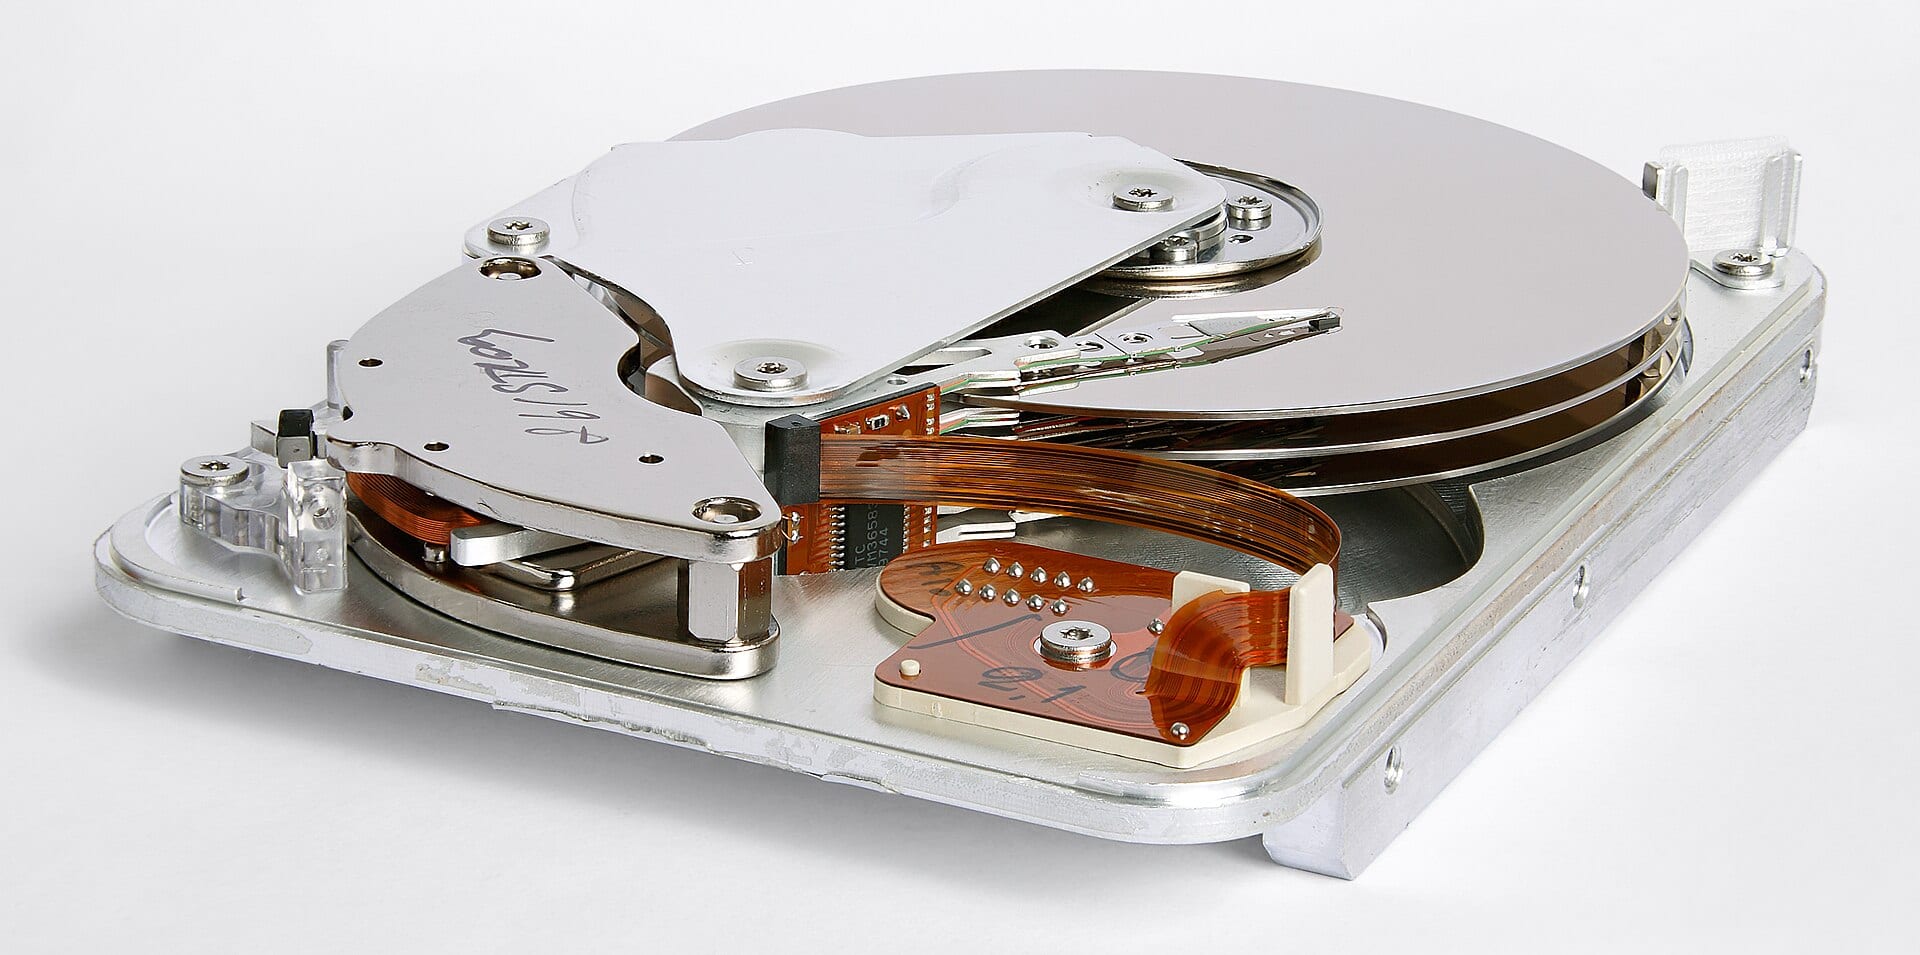
Seagate reportedly bids billions for TDK's drive-head unit, outbidding Toshiba, which cannot build without it
Seagate has reportedly topped Toshiba's offer for TDK's hard-drive head unit, the only independent maker of a part all three drive producers need. The report landed two trading days after Toshiba's capacity plan knocked a tenth off Seagate, and Toshiba calls it wrong.
 Vincent Jiang · 3 min read
The bid answers the report that cost Seagate 10%
Seagate has reportedly outbid Toshiba for TDK's magnetic-head business in a deal that people familiar with the matter put at several billion dollars 1. Toshiba opened talks in the spring; Seagate returned with a higher offer over the summer 1. TDK closed 5.25% higher in Tokyo, and Seagate finished Monday at $887.09, up 4.49% 17.
Friday's Toshiba capacity report, which The Inference covered on October 3, knocked 10.2% off Seagate and 12% off Western Digital 15.
Three customers, one independent supplier
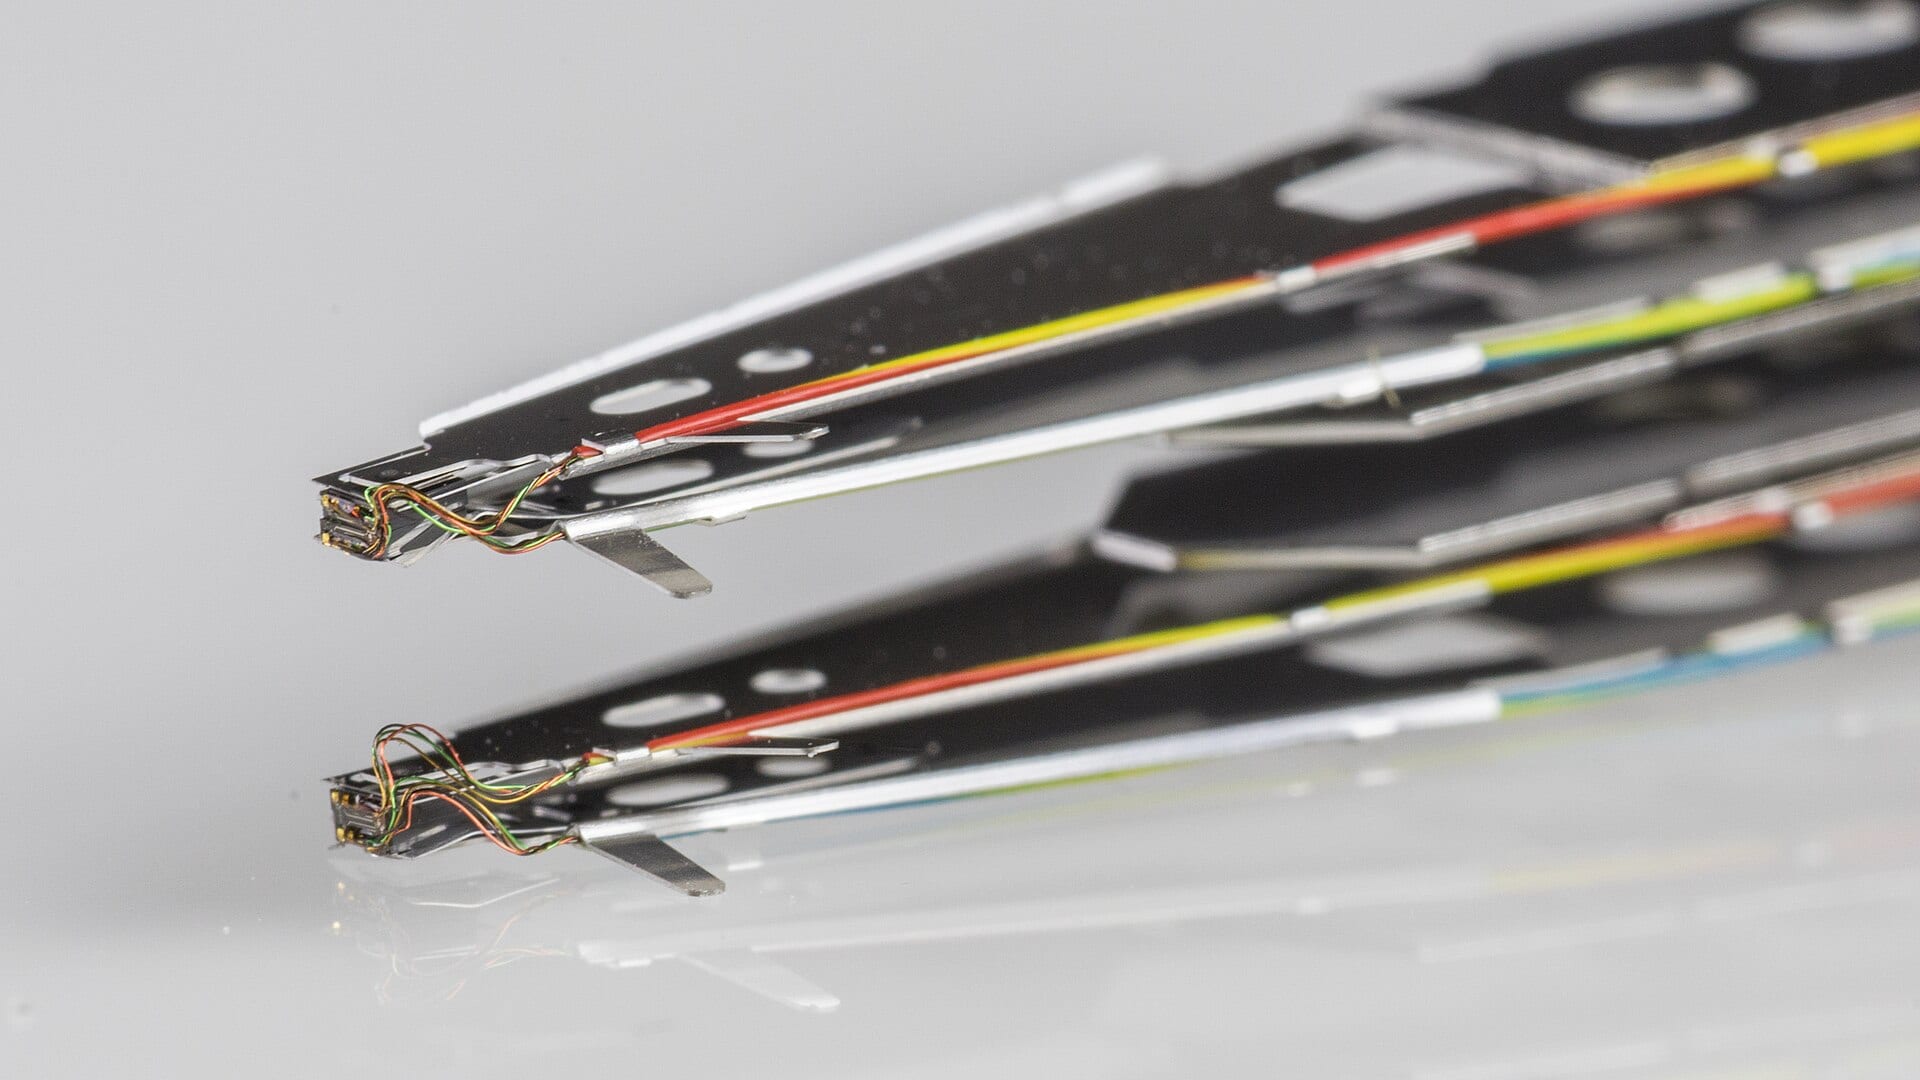
TDK is the only independent maker of the heads that write to and read from a drive's platters 14. Seagate and Western Digital build heads in-house and turn to TDK when demand spikes; Toshiba buys every head from TDK, and its plan to mass-produce HAMR drives leans on TDK's technology 14.
Citi analyst Asiya Merchant argued Toshiba's $380 million plan to double capacity by fiscal 2027 stays capped unless outside suppliers of heads and media expand too 56. TrendForce projects Western Digital at 48% of the 2026 drive market, Seagate at 42%, Toshiba at 10% 4.
Two companies hold 90% of the drive market Toshiba wants to enter
- Estimate
Data
| Value | |
|---|---|
| Western Digital (estimate) | 48% |
| Seagate (estimate) | 42% |
| Toshiba (estimate) | 10% |
A 223% year has priced the scarcity
Seagate is up more than 223% this year and sits about 22% below its June 18 record 1. The numbers behind the move: revenue of $3.629 billion last quarter, up 48.5% year over year, an operating margin of 43%, and 2026 output sold out under agreements running into 2027 and 2028 68.
A several-billion-dollar check strains a balance sheet holding $1.704 billion of cash against $3.565 billion of debt 8; Seagate's last two storage deals, Intevac and Xyratex, cost $119 million and $376 million 1. Western Digital, the third customer, has $527 million of net cash, a $441.76 stock and no bid on the table 2.
Seagate's cash hit $1.7 billion as debt fell $2.1 billion over eight quarters
- Cash
- Debt
Data
| Cash | Debt | |
|---|---|---|
| Q3 '24 | $1.24B | $5.68B |
| Q4 '24 | $1.24B | $5.68B |
| Q1 '25 | $0.81B | $5.15B |
| Q2 '25 | $0.89B | $5B |
| Q3 '25 | $1.11B | $4.99B |
| Q4 '25 | $1.05B | $4.5B |
| Q1 '26 | $1.15B | $3.86B |
| Q2 '26 | $1.7B | $3.57B |
Seagate's operating margin more than doubled in two years of sold-out supply
Data
| Operating margin | |
|---|---|
| Q3 '24 | 18.6% |
| Q4 '24 | 21% |
| Q1 '25 | 20% |
| Q2 '25 | 23.2% |
| Q3 '25 | 26.4% |
| Q4 '25 | 29.8% |
| Q1 '26 | 32.1% |
| Q2 '26 | 43% |
Toshiba denies the auction exists
A Toshiba spokesperson called the report inconsistent with the company's understanding; Japan Industrial Partners, its main backer, said the same, and Toshiba denied any three-way talks on future head supplies 3. No agreement is confirmed by any of the three companies 3.
The report itself anticipates close antitrust scrutiny of any sale 4, and LYNX Equity Strategies reads Toshiba's investment as protection against a domestic shortage rather than a share grab 5.
What TDK's choice decides
TDK is weighing an exit to fund batteries, sensors and passive components; its magnetic-application segment returns 4% on invested capital, the group's lowest 4.
If Seagate wins the unit, Toshiba's doubling runs through a part owned by the competitor whose capacity report just repriced its stock, and Western Digital's swing supply would come from that same rival 14. If Toshiba wins, Seagate and Western Digital buy their swing supply from a unit their competitor owns 4.
Watch TDK's pick, Toshiba's next statement and the antitrust review the report already anticipates 34. Toshiba can build the plants; the heads decide whether they run.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.