서비스나우, AI는 묶었는데 청구서는 못 묶었다
나우 어시스트(Now Assist)는 새로 선보인 요금제 3개에 모두 기본 탑재됐고 사용량은 풀(pool)을 기준으로 과금된다. 추가 과금 단가는 공개돼 있지 않고, 계약 서명 전에만 협상할 수 있다.
 Vincent Jiang · 3 min read
직무 이름을 내건 요금제
1차(L1) 서비스데스크 좌석이 이제 가격표에 품목 하나로 올라 있다. 서비스나우가 4월 9일 판매를 시작한 요금제 3개 중 최상위인 '프라임(Prime)'은 업무 전체를 떠맡는 에이전트를 단위로 팔리는데, 이 요금제가 이름을 붙인 직무가 바로 서비스데스크다.1
미터가 이미 벌어들인 액수
AI 사업은 6월 분기에 연간 계약 가치(ACV) 10억 달러를 넘어섰다. 같은 분기 구독 매출은 38억7700만 달러로 24.5% 늘었다.2 9월 9일에는 연간 목표가 15억 달러로 상향됐다.3
'포함'은 '무료'가 아니다
기존 패키지 5개는 3개로 통합됐고, 나우 어시스트는 별도 추가 구매 옵션으로 곁에 두는 대신 세 요금제 모두에 들어갔다.1 각 요금제에는 어시스트 풀이 딸려 있다. 풀을 넘어선 사용량은 추가 과금(탑업)으로 청구되고, 에이전트가 한 번 돌아갈 때 차감되는 어시스트는 요약 한 번보다 훨씬 많다.4
자문사들은 업무 처리 담당자(퍼필러) 1인당 풀을 1500~6000어시스트로 보고 있다. 추가 과금 단가는 갱신 시점에 협상할 수 있을 뿐 그 이후에는 불가능하다. 계약서에 빠뜨리면 풀이 빌 때 공급사가 단가를 정한다.4,5 두 항목 모두 공개된 달러 금액은 존재하지 않는다.4
번들은 공짜가 아니다. 번들은 계량 과금이다.
계약 양쪽에 모두 돌아가는 비용
어시스트를 제공하는 데 드는 비용은 플랫폼 자신의 마진에 그대로 드러난다. 비-GAAP 구독 매출총이익률은 6월 분기 80.5%로, 1년 전 83.0%에서 떨어졌고 연간 가이던스는 81.0%다.2 회사는 하락 원인으로 하이퍼스케일러 사용량과 AI 도입을 꼽는다.6,10
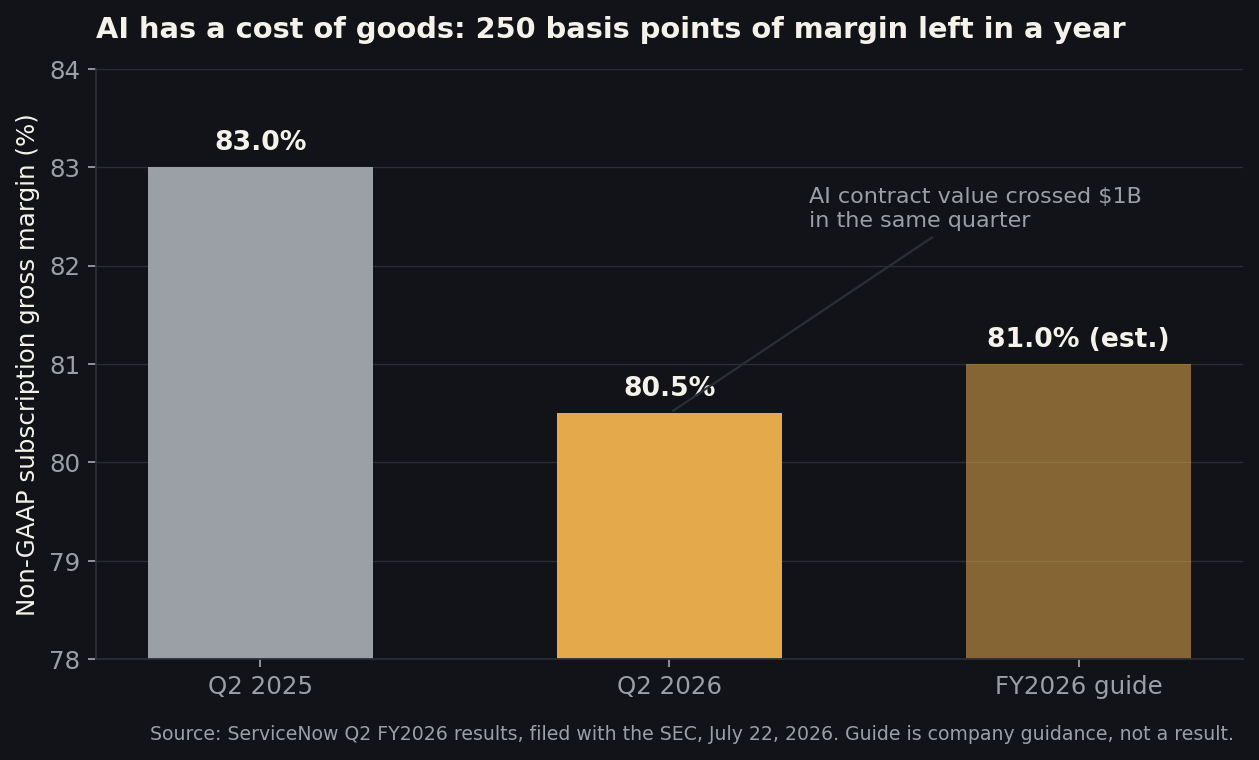
구매자 쪽도 같은 방향이다. 어시스트를 한 건도 세기 전에 갱신 시 단가는 8~12% 오르고 연 3% 복리 인상 조항이 붙는다.5,7,11 풀을 차감하는 그 에이전트는 직접 만든 게 아니라 산 것이다. 지난 12월 거래가 마무리된 28억5000만 달러짜리 무브웍스 인수가 그것으로, 지금 같은 번들 안에 들어가 나오고 있다.8
계량 과금에도 논리는 있다
계량 과금에는 나름의 논거가 있다. 고객이 다 쓰지 못하는 풀은 추가 비용을 낳지 않는다. 한 애널리스트는 이 구조를 통행료가 아니라 '써 보고 사는' 길로 해석한다.1 투자자들은 올해 내내 정반대의 위험에 값을 매겨 왔다. AI 에이전트가 좌석 기반 소프트웨어의 속을 빼 놓을 것이란 전망에서 주가를 52주 최고점 대비 약 51% 아래로 쳐 놓은 것이다.9,12 빌 맥더못 서비스나우 CEO는 영업 주기에 지연이 없다고 말한다.10
두 시각 모두 성립할 수 있다. 그러나 어느 쪽도 초과 사용 비용이 얼마인지 구매자에게 알려주지 않는다. 위험 노출은 서명 다음 날부터 시작된다.
주목할 대목
3개 요금제 체계에서 첫 갱신 물량이 어떻게 되는지, 그리고 풀이 바닥나는 분기들에서 81% 가이던스가 버티는지를 지켜야 한다. 승부를 가르는 숫자는 AI의 가치가 아니다.
미터가 가리키는 숫자다.
How this brief was made
01Gathered & sourced373 channels · 1,899 articles▾
Agents swept 373 channels and ingested 1,899 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated12 claims · 31 data feeds▾
Every one of 12 load-bearing claims was checked against primary sources, with 31 live data feeds reconciling the figures and charts.
- 1TechTarget, Apr 2026 (the three AI-native tiers, what is bundled, Prime sold on role replacement; independent trade coverage quoting named analysts at Moor Insights & Strategy and IDC).
- 2ServiceNow Q2 FY2026 results, filed with the SEC, Jul 22 2026 (primary record: $3,877M subscription revenue, 24.5% growth, 80.5% non-GAAP subscription gross margin against 83.0%, AI ACV past $1B, 81% full-year margin guide; guidance is not a result).
- 3Ad-hoc News market report, Sep 2026 (AI contract-value target raised to $1.5B at an investor conference on Sep 9; company-claimed target, not a booking).
- 4Redress Compliance, Now Assist licensing white paper, 2026 (assist pools of 1,500 to 6,000 per fulfiller, top-up negotiable only at renewal, no published unit rate; named licensing advisory with a commercial interest in negotiation work, figures are estimates).
- 5Redress Compliance, ServiceNow cost creep report, 2026 (8 to 12% unit-price rises and 3% compounding uplift clauses at renewal; advisory estimate, unaudited).
- 6Investing.com, Jul 22 2026 (Q2 slide coverage attributing the margin decline to hyperscaler partnerships and AI consumption; editor-reviewed market report).
- 7UpperEdge, 2026 (negotiation timing advisory on consumption terms; commercially interested, not an audit).
- 8CX Today, Dec 2025 (Moveworks acquisition completed for $2.85B in cash and stock; independent trade coverage).
- 9The Motley Fool, Jul 20 2026 (shares roughly 51% below the 52-week high on AI-disruption fears; market commentary, not a valuation opinion this desk endorses).
- 10ServiceNow Q2 FY2026 earnings call transcript, Jul 22 2026 (management on model mix and cost optimisation; company-claimed, speaker text).
- 11NPI, 2026 (buyer-side negotiation benchmarks for the same renewals; commercially interested advisory).
- 12TIKR, 2026 (the counter-case that the 2026 selloff misreads the category; market commentary, single outlet).
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.