SK Hynix fell 10% by midday on an unverified Nvidia HBM4 rumor the shipment record contradicts
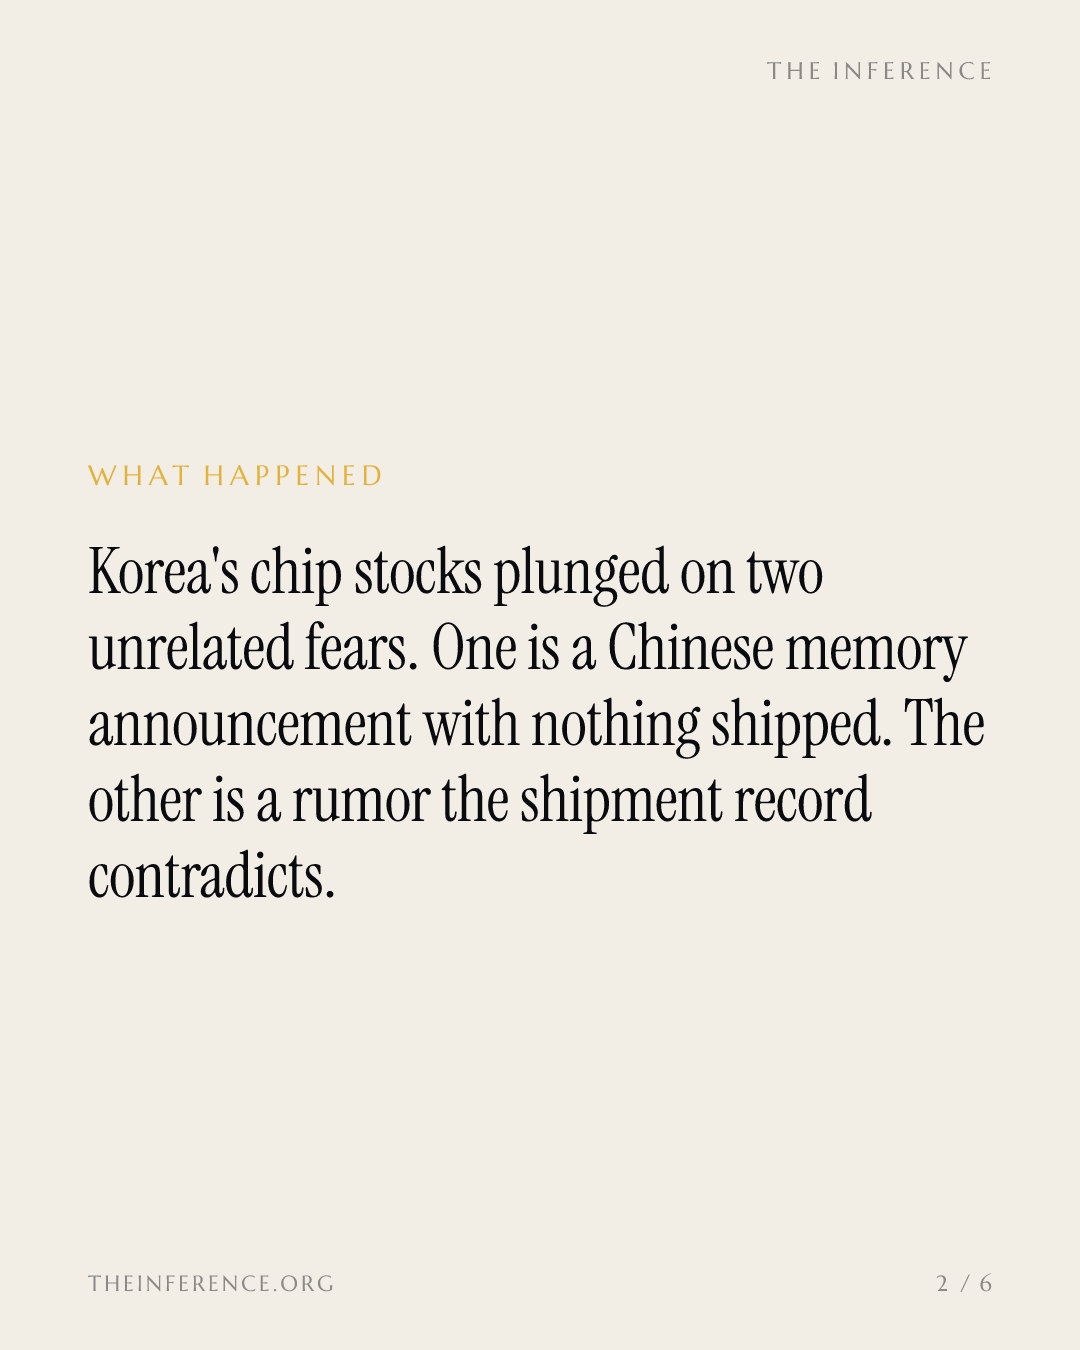
Korea's chip complex fell 7% on a Chinese memory announcement that has shipped nothing, while the HBM4 despec rumor behind SK Hynix's slide points the wrong way against the shipment record.
 Vincent Jiang · 3 min read
Two fears went into one basket on Tuesday
Seoul's Kospi fell more than 7% intraday on October 13, its lowest level since July 31, with Samsung Electronics−7.39% — Samsung Electronics, down 7.39 percent today down 9% and SK Hynix−3.66% — SK Hynix, down 3.66 percent today down 10% by midday 2. The day before, CXMT's memory announcement−2.79% — CXMT's memory announcement, down 2.79 percent today had already taken Samsung down 3.6% and SK Hynix 3.4% in won terms 6. SanDisk slid 2.8% premarket even though the Chinese advance concerns DRAM, not the NAND market it sells into 3. One basket, two very different fears, and only one of them has shipped anything.
What China actually announced
On October 10 at a Shanghai conference, CXMT president Cao Kanyu unveiled progress on a 4F² DRAM cell, a vertical-gate transistor layout that packs roughly 30% to 50% more density into the same silicon area, and promised a DDR5 server RDIMM by year-end 57. That is the whole announcement. No speeds, no capacities, no named customers, no volume commitments; Korean reporting suggests the first products may only partly use 4F², and volume production is a separate hurdle 5. Cantor Fitzgerald called the reaction a case of "the headline is worse than reality" 3. The scoreboard says the same: CXMT holds 9.5% of global DRAM revenue, fourth place, against Samsung's 39.4% 7.
CXMT is the number four in DRAM at 9.5% of revenue, not yet the incumbent killer
Data
| DRAM revenue share | |
|---|---|
| Samsung | 39.4% |
| SK hynix | 24.9% |
| Micron | 23.3% |
| CXMT | 9.5% |
What the HBM4 record shows while the rumor mill spins
The rumor behind SK Hynix's slide says Nvidia+0.23% — Nvidia, up 0.23 percent today cut HBM4 stacks from 12-high to 8-high. Here is the documented sequence instead. The JEDEC HBM4 standard sat at 8 gigabits per pin; SK Hynix designed for 10 on its proven MR-MUF bonding process, which it says lifts productivity about 3 times and heat dissipation 2.5 times; Samsung, beaten in HBM3, gambled in 2024 on newer 1c dies over its own 4nm base die 1. Nvidia then raised Rubin's requirement to 10 gigabits and past 11 in the third quarter of 2025, forcing all three makers to resample, and Samsung announced mass-production shipments at 11.7 gigabits in February 1. The gamble bought headroom. But headroom is not share: supply-chain tracker Silicon Analysts reports SK Hynix mass-producing a 48GB, 16-layer HBM4 stack for Rubin in the third quarter, while Samsung's 12-layer HBM4 sits in final qualification 4. In June, Jensen Huang named all three suppliers for Rubin, with analysts estimating SK Hynix at 60 to 70% of the volume 8.
Nvidia raised Rubin's HBM4 speed bar twice, above what either maker first designed for
Data
| HBM4 pin speed | |
|---|---|
| JEDEC standard | 8 Gbps |
| SK Hynix design | 10 Gbps |
| Nvidia requirement | 11 Gbps |
| Samsung shipped | 11.7 Gbps |
The counterpoint, stated fairly
The 12-high reversal claim comes from a reconstruction by Damnang Research, an ex-AMD+1.04% — AMD, up 1.04 percent today engineer's own modeling, and the decisive part sits behind a paywall 1. Hock Tan warned on Monday that capital, not chips or electricity, could become the AI industry's binding constraint, and that fear is legitimate 2. CXMT's DRAM share did jump from 7.6% to 9.5% in a single quarter; the direction is real even if the level is not yet 7.
The dated things that settle it
Three readings: CXMT's year-end RDIMM, 11 weeks out, will show whether volume follows the announcement 5; Samsung's 12-layer HBM4 qualification result 4; and SanDisk's October 29 earnings call on whether memory margins hold 3. The rumor said SK Hynix lost HBM4. The shipment tracker says it is the only one shipping the hardest part of it.
More about NVIDIA
NVDA · Fiscal Q2 2027Revenue rose 106% to $96.2B, 92.5% of it from Data Center, “driven by the ramp of our Blackwell Ultra infrastructure”. Gains on equity stakes of $7.8B lifted net income to $59.7B.
Show as a table
| Line | Value |
|---|---|
| Revenue | $96.2B |
| Gross margin | 75.0% |
| Operating margin | 66.2% |
| Net income | $59.7B |
| Hyperscale | $48.7B |
| AI clouds & enterprise | $40.3B |
| Data Center | $89.0B |
| Edge Computing | $7.2B |
| Gross profit | $72.1B |
| Cost of revenue | $24.1B |
| Other income | $7.8B |
| Operating income | $63.7B |
| Operating expenses | $8.4B |
| Tax | $11.8B |
| R&D | $7.1B |
| SG&A | $1.4B |
Deepdive
AI-generated from this story and its cited sources. Not investment advice.