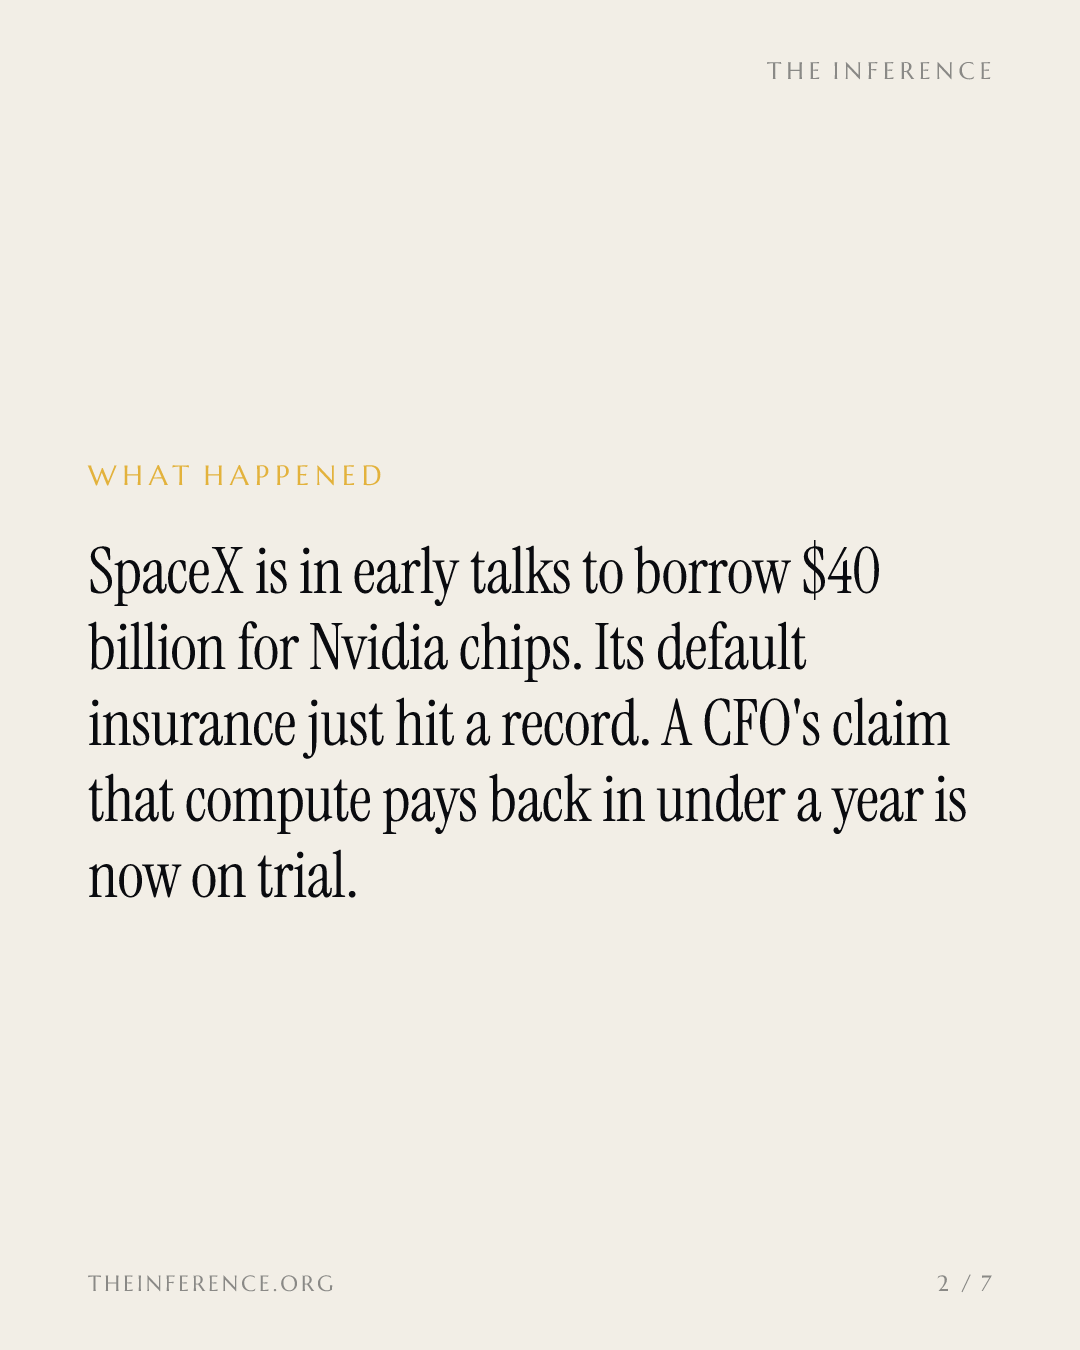
SpaceX wants $40 billion more for Nvidia chips as its default insurance hits a record 194 basis points
Default insurance on SpaceX debt hit a record this week and its 50-year bonds slipped to 85 cents, before the reported $40 billion chip financing. Whether CFO Bret Johnsen's sub-one-year payback claim on compute holds decides who absorbs the cost.
 Vincent Jiang · 3 min read
The charge: a payback claim, priced in basis points
The sentence on trial belongs to CFO Bret Johnsen: "The current economics have translated into a less than one-year payback on our new capital deployments for compute" 1. The market that carries the loss if he is wrong moved first. Five-year default insurance on SpaceX+1.40% — SpaceX, up 1.40 percent today hit a record 194 basis points on October 7, up from 110 in June, and the 2056 bond yields 2.36 points over Treasuries, from 1.75 in June 3. The 50-year paper trades near 85 cents on the dollar 1.
The evidence: $18 billion out, $2.4 billion in
This week supplied the reason: SpaceX is in early talks to borrow $40 billion for Nvidia chips, roughly $10 billion of bank loans plus $30 billion of investment-grade debt, with Apollo expected to lead and Pimco among the lenders 2. The talks are preliminary and may not close 2.
The filings explain the appetite. Second-quarter capital spending was $18.4 billion against $2.4 billion of operating cash 58, and total debt has climbed from $13.8 billion at the end of 2024 to $39.4 billion at the end of June 8.
Interest expense ran $629 million in the quarter, up 53 percent in a year 5. Debt, not operations, is bridging the gap.
Capital spending has left operating cash flow far behind
- Capital spending
- Operating cash flow
Data
| Capital spending | Operating cash flow | |
|---|---|---|
| Q1 2025 | $4.14B | $0.73B |
| Q2 2025 | $2.83B | -$0.38B |
| Q1 2026 | $10.11B | $1.05B |
| Q2 2026 | $18.37B | $2.42B |
The company's exhibits: $39 billion contracted, $61 billion to go
The bull case is contractual. Anthropic$350B — Anthropic, private, latest valuation $350B pays $1.25 billion a month through May 2029, Alphabet+0.98% — Alphabet, up 0.98 percent today pays $920 million a month from this October, and a new deal disclosed on September 10 starts December 1 at $1.11 billion a month 246.
That is more than $3.2 billion a month, which annualizes to about $39 billion; roughly $61 billion of the $100 billion run rate Johnsen has promised for year-end is still to be contracted 6. Goldman's Eric Sheridan lifted his target to $230 from $220 on capacity and margin forecasts through 2028 9. Musk's reply to talk of slower builds: "False, we are accelerating rapidly" 1.
Three contracts promise $3.2 billion a month, and $61 billion of the target is still unsigned
Data
| Value | |
|---|---|
| Anthropic | $1.25B a month |
| New deal (Sept 10) | $1.11B a month |
| Alphabet | $0.92B a month |
The reported $40 billion chip borrowing would double the debt again
- Estimate
Data
| Value | |
|---|---|
| Q4 2024 | $13.8B |
| Q4 2025 | $22.9B |
| Q1 2026 | $30.3B |
| Q2 2026 | $39.4B |
| If the $40 billion closes (estimate) | $79.4B |
The prosecution: read the termination clauses
The Alphabet contract let Google walk if SpaceX failed to deliver the committed GPUs by September 30, 2026 4. That deadline passed ten days ago; whether SpaceX met it is unreported, and the deal is still set to bill from this month 14. What is live now is the exit clause: after this year, either party can leave on 90 days' notice, on compute deals that typically run about six months 46.
The arithmetic: $18 billion due back inside twelve months
A one-year payback on last quarter's spend means roughly $18 billion of cash inside twelve months, 2.6 times what the whole company generated from operations in fiscal 2025 1. The AI segment lost $1.3 billion last quarter while connectivity, 55 percent of revenue, earned $1.7 billion 57. FT Lex's John Foley: the market "is saying this company's getting riskier by the minute" 1.
The cross-examination: the chips sell either way
Nvidia−0.47% — Nvidia, down 0.47 percent today books this demand regardless. Apollo, expected to lead the deal, is one of six financiers Nvidia partnered with in August to mobilize more than $500 billion for AI infrastructure, and it previously financed $7 billion of chips for xAI$200B — xAI, private, latest valuation $200B 2.
The compute risk sits on SpaceX's balance sheet, behind which shareholders now queue. Even the $100 billion cash pile is spoken for: two more quarters at the capex level Johnsen has guided means roughly $37 billion, before up to $8.5 billion for EchoStar spectrum in 2027 5. The chips sell either way; the debt stays home.
The verdict watch: October's billings
The Alphabet meter starts running this month, alongside $6.7 billion of contracted cloud revenue that begins ramping now 14. The next two quarters of cash flow will show whether the payback line is arithmetic or aspiration. Beneath it sits the rating: BBB today, and every number above reprices if it goes 3.
More about NVIDIA
NVDA · Fiscal Q2 2027Revenue rose 106% to $96.2B, 92.5% of it from Data Center, “driven by the ramp of our Blackwell Ultra infrastructure”. Gains on equity stakes of $7.8B lifted net income to $59.7B.
Show as a table
| Line | Value |
|---|---|
| Revenue | $96.2B |
| Gross margin | 75.0% |
| Operating margin | 66.2% |
| Net income | $59.7B |
| Hyperscale | $48.7B |
| AI clouds & enterprise | $40.3B |
| Data Center | $89.0B |
| Edge Computing | $7.2B |
| Gross profit | $72.1B |
| Cost of revenue | $24.1B |
| Other income | $7.8B |
| Operating income | $63.7B |
| Operating expenses | $8.4B |
| Tax | $11.8B |
| R&D | $7.1B |
| SG&A | $1.4B |
Deepdive
AI-generated from this story and its cited sources. Not investment advice.