The Customers Walk; CATL's Suppliers Carry the Float
Li Auto, Xiaomi and XPeng are pulling battery volume out of CATL, which ended 2025 owing suppliers ¥263.6bn against the ¥121bn its customers owed it. Its answer to the defections is a 100 GWh plant in Hungary.
 Vincent Jiangthree-minute read
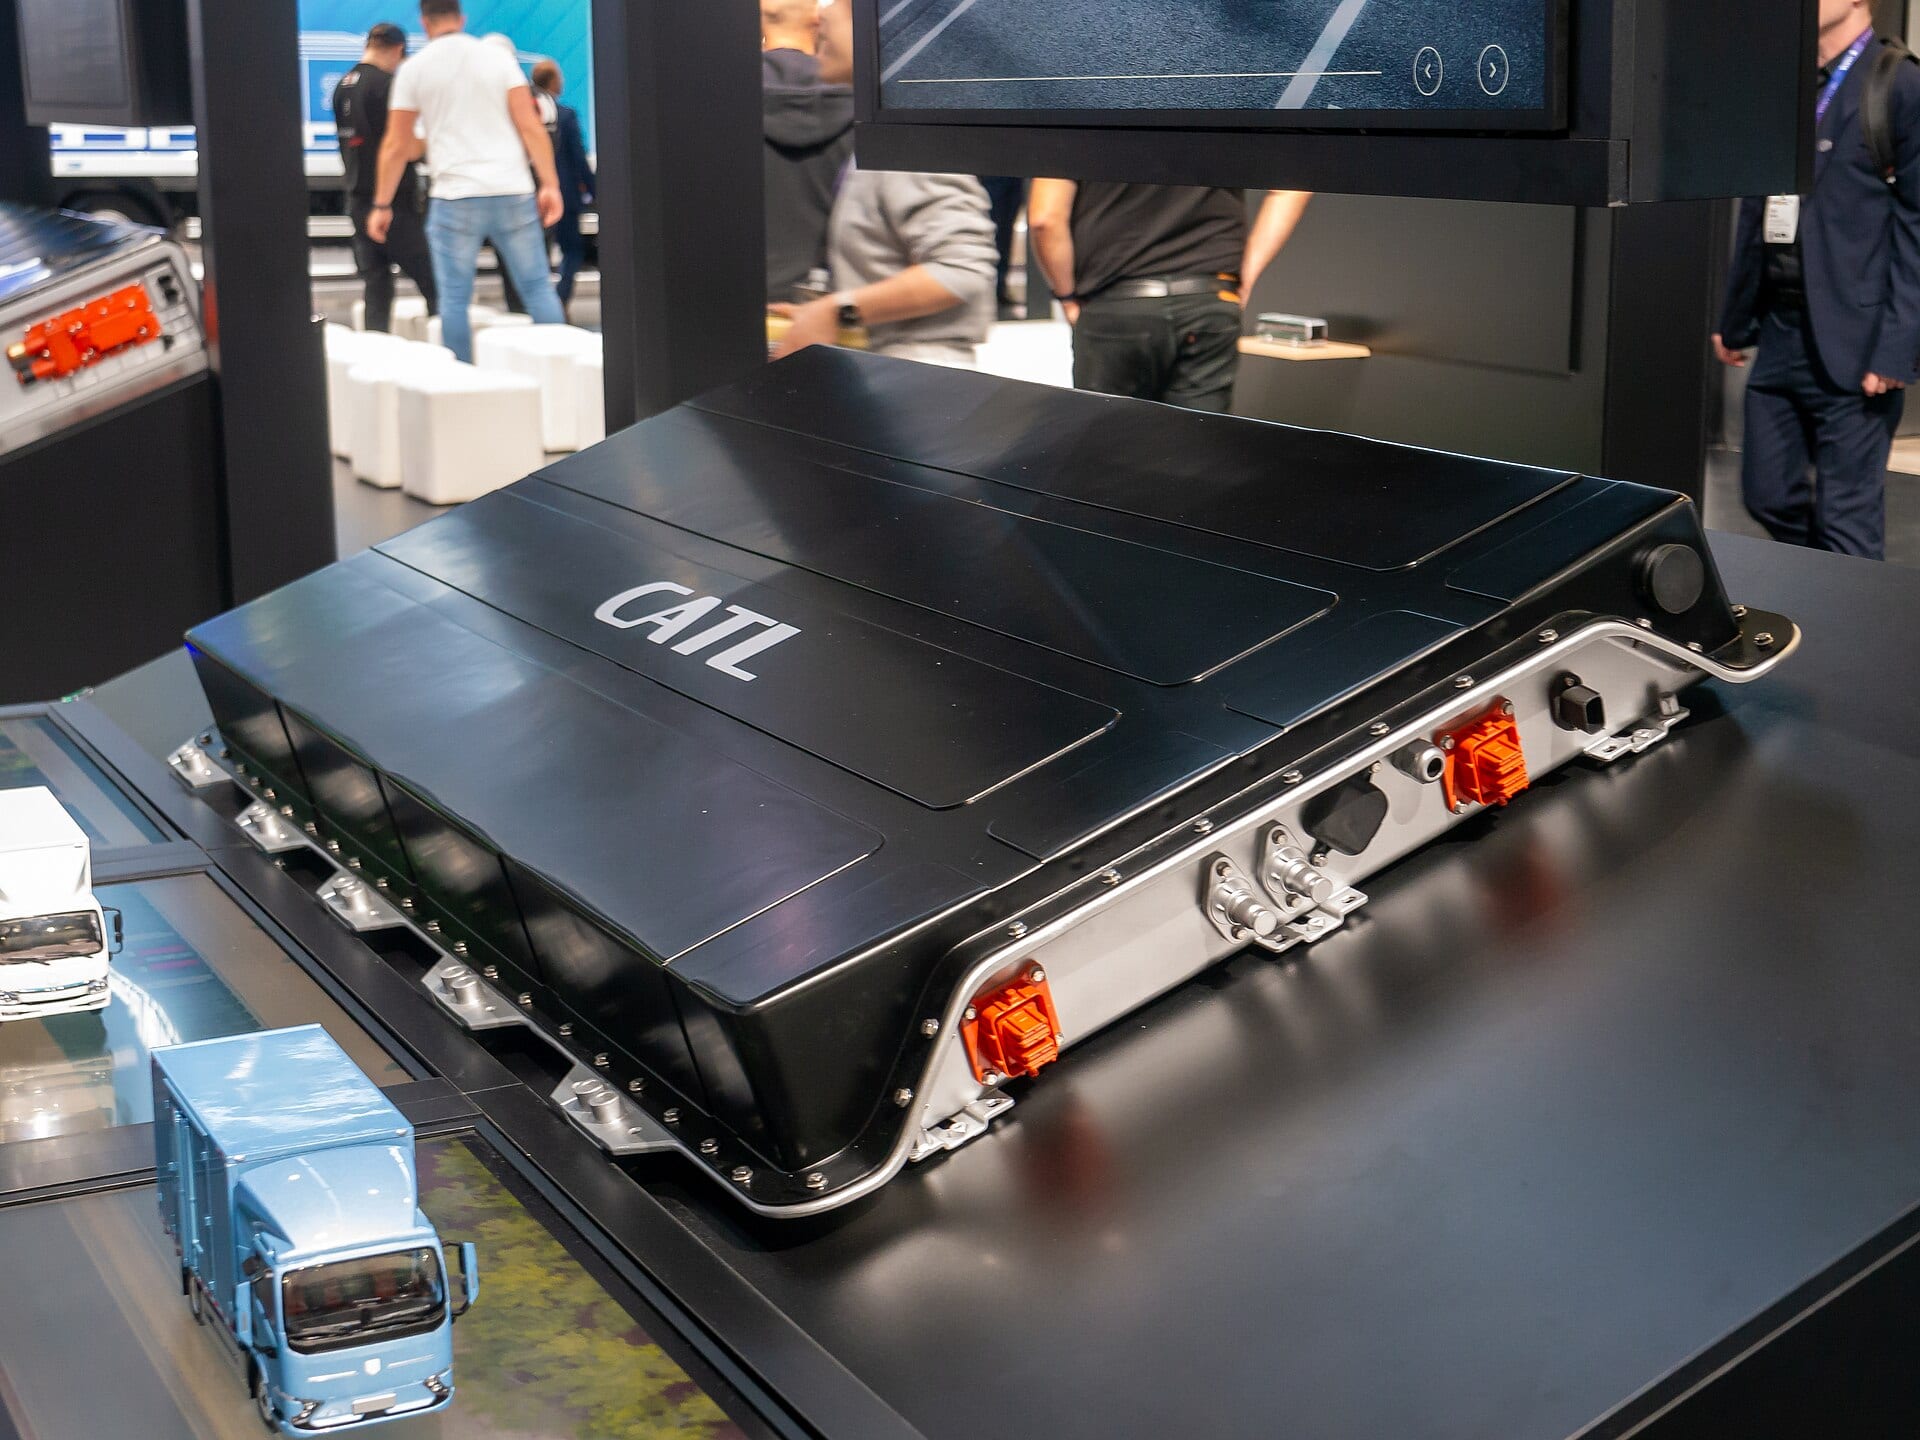
3 p.m. on 7 September: Li Auto stops buying the MEGA's cell from CATL
Orders for the new-generation MEGA locked after 3 p.m. that day no longer get CATL's+1.18% — CATL's, up 1.18 percent today 5C cell.12 They get a cell whose anode, cathode and electrolyte Li Auto defined itself, with Sunwoda and CALB running the machines.1 The i9 Home followed on 17 September, and in-house cells were already in mass production on the L8, L6 and i8.12
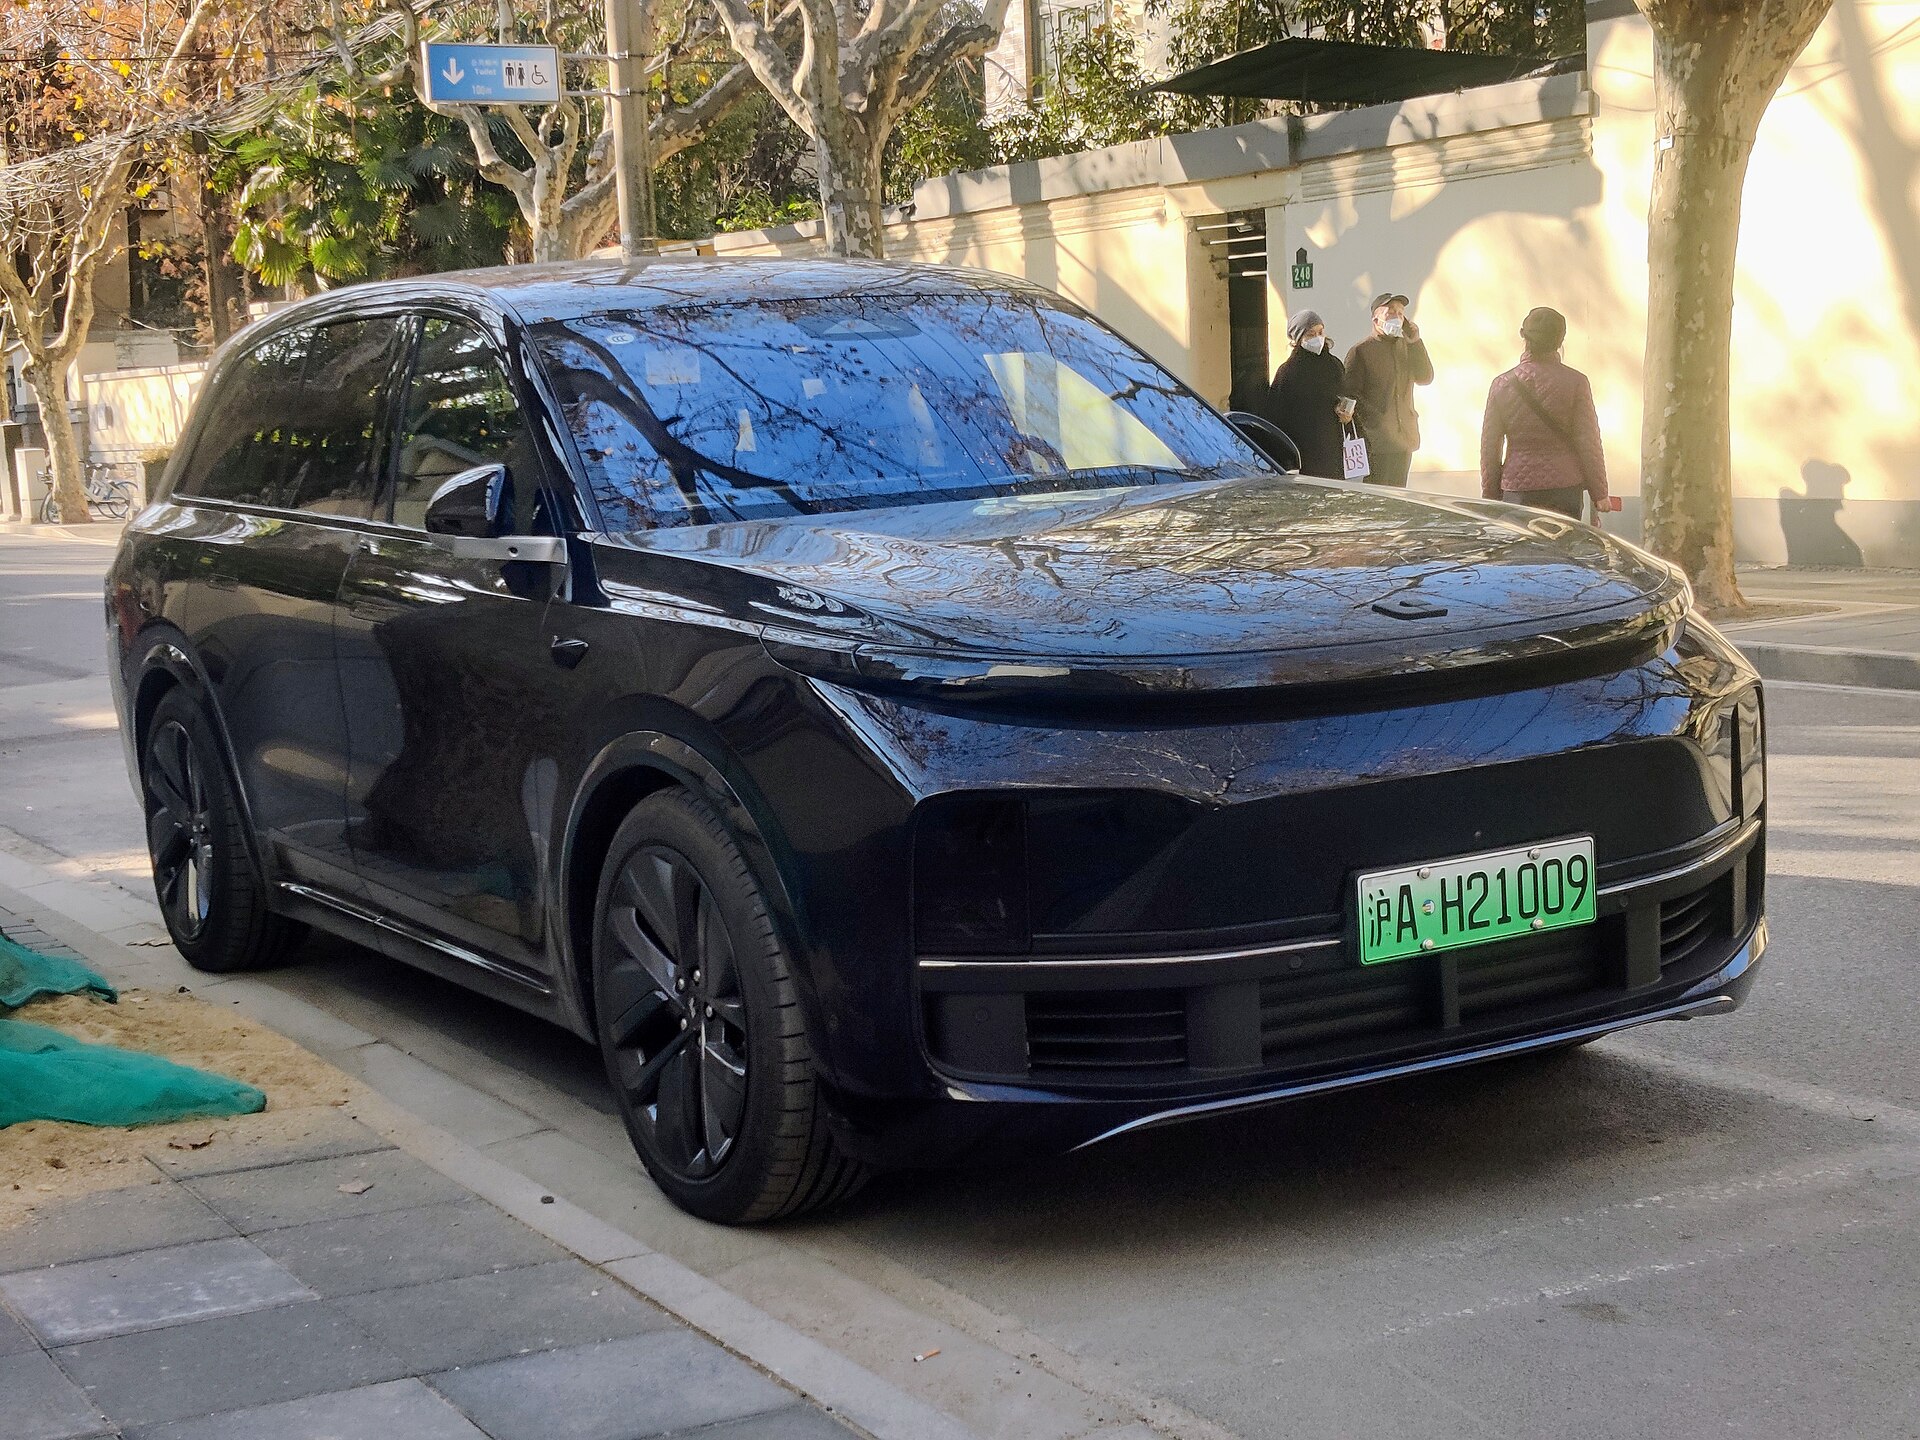
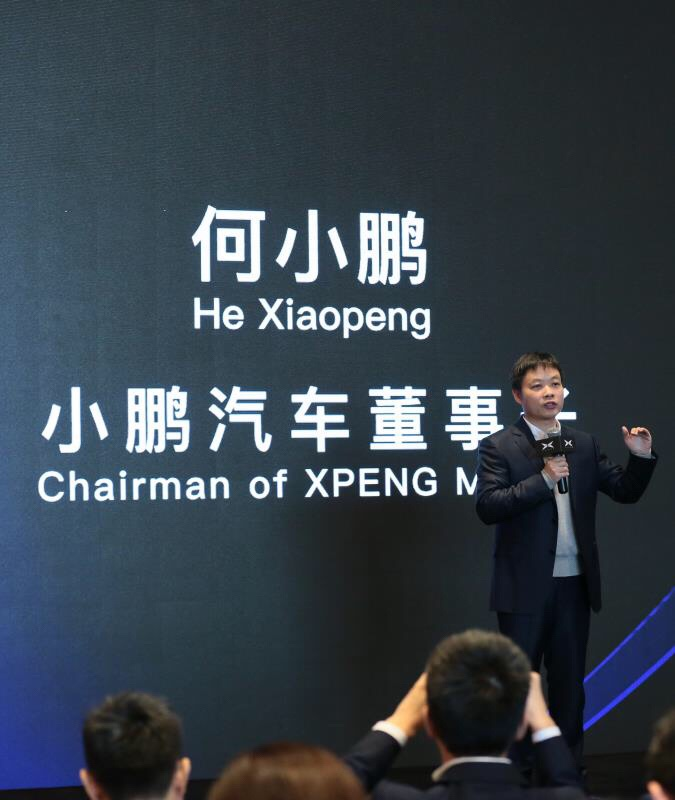
CATL's market value fell 3.65% the next day.1 Xiaomi+0.76% — Xiaomi, up 0.76 percent today put CALB and Sunwoda on exclusive lines for its Dragon Armor battery and left CATL off the Pengcheng N70 and N90 supplier lists, and XPeng's He Xiaopeng says his company will develop "all batteries" itself, cells excepted.1 Li Auto president Ma Donghui has gone furthest: every product after 2026 carries Li Auto-defined cells.3
The customers leave, the suppliers keep carrying the float
Supply-chain surveys put CATL near 70% of Li Auto's battery supply before the switch, falling toward 50% for 2026.1 Sunwoda and CALB take the defecting volume, and Sunwoda takes more: ¥2.65bn of Li Auto capital for 8.79% of its EV-battery unit, 11.17% counting affiliates.4 CATL's own suppliers get vouchers they can discount for cash, and a payment date.1
CATL's ledger is the part nobody prices. At end-2025 it owed suppliers ¥263.6bn against the ¥121bn customers owed it, a 2.18x gap that widened to 2.52x by H1 2026, with ¥57.8bn of payables sitting in supplier-financing vouchers, per a 36kr teardown of its books.1
CATL owed suppliers ¥263.6bn at end-2025; customers owed it ¥121bn
Data
| Value | |
|---|---|
| Owed to suppliers, end-2025 | ¥263.6B |
| Owed by customers, end-2025 | ¥121B |
| Supplier-financed payables, H1 2026 | ¥57.8B |
The buyback does not touch the float
Alongside the float, CATL plans a ¥20-40bn buyback of its own A-shares, capped at ¥573 apiece, every repurchased share to be cancelled.5 Nothing in the filings traces the float to the buyback; what they show is who holds the exposure while both run.
CATL's defense: share and profit still climbing
Chief manufacturing officer Ni Jun's line at CATL's Global Quality Open Month: "Those who can make cars may not necessarily make batteries."1 The half-year numbers carry some of it: 46.7% of China's passenger-car installs, 75.2% of ternary, revenue up 54.8% at ¥276.9bn, net profit up 42% at ¥43.28bn.5 The stock closed 24 September just 0.2% above its 52-week low.6
The next 100 GWh rises a continent away from the defectors
Trial production began on 22 September at the first two Debrecen lines: 34 GWh in phase one, 100 GWh planned, CATL's largest site outside China once built out.78 The cells are spoken for: Mercedes plants in Germany and Hungary, and the BMW iX3 built a few kilometres away, from 2027.7 The carmakers taking volume out are Chinese; the replacement capacity is rising in Hungary, for German customers.7
The toll they are revolting against is size. When one supplier's battery runs to roughly 40% of a car's bill of materials, 36kr's reading is blunt: the car company is a wage earner.1 Watch the payables ratio in the annual report: a gap that keeps widening means CATL's defense is still financed by the people with the least say in it.
Get Power by email, free
How AI's hunger for electricity moves utilities, power plants and the grid. In our daily email, every weekday.
Reader comments
0 comments